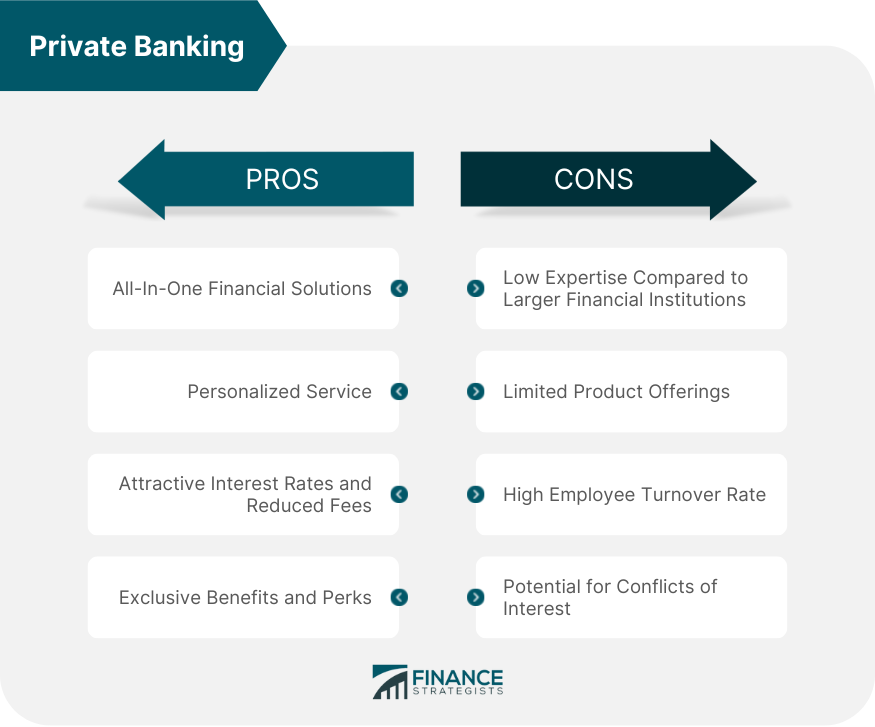
7 Things Worth Knowing About Private Banking Institutions
The allure of private banking institutions lies in their ability to offer what retail banks cannot: personalized, confidential, and often discreet financial solutions. But behind the polished facades of Swiss châteaux and Mayfair townhouses, a complex ecosystem operates—one built on trust, risk, and the quiet movement of vast sums. Here’s what sets them apart.1. They Serve a Niche, Not a Market
Private banking institutions don’t chase volume. Their client base is tightly curated—typically individuals with net assets exceeding $1 million, though the threshold varies by institution. The largest players, like UBS and Credit Suisse, manage trillions in assets, but their profits come from a relatively small pool of clients who demand bespoke services. This exclusivity isn’t just about wealth; it’s about access to a network of lawyers, tax advisors, and even private equity deal flow that retail clients can’t tap into. The numbers underscore this: private banking institutions account for roughly 10-15% of global banking assets, yet their revenue margins often exceed those of traditional banks. Their business model thrives on high-touch relationships, where a single client might generate fees equivalent to a retail bank’s annual profit from thousands of accounts.2. Secrecy Is Their First Line of Defense
The reputation of private banking institutions is inseparable from their culture of confidentiality. While regulations like FATCA (Foreign Account Tax Compliance Act) and CRS (Common Reporting Standard) have forced greater transparency, loopholes persist. Institutions in jurisdictions like Liechtenstein, Singapore, and the Cayman Islands still attract clients seeking anonymity, even if the days of numbered accounts are largely over. This secrecy isn’t just about hiding money—it’s about protecting strategies. A family office might use private banking institutions to structure trusts in ways that minimize inheritance taxes across multiple jurisdictions. The challenge for regulators is that these structures are often legal, even if their intent is to exploit gaps in tax laws.3. They’re Not Just Banks—they’re Ecosystems
Private banking institutions don’t stop at deposits and loans. They offer full-service financial orchestration, including: - Wealth structuring (trusts, foundations, family offices) - Private equity and venture capital access - Art and luxury asset advisory - Philanthropic and impact investing - Succession planning for dynasties For example, a client might deposit cash with a private bank in Geneva, then use the same institution to invest in a vineyard in Bordeaux, a tech startup in Berlin, and a charitable foundation in Monaco—all while maintaining a single point of contact. This integrated approach is what justifies the premium fees.4. Fees Are Negotiated, Not Standardized
Unlike retail banking, where fees are published, private banking institutions operate on customized fee schedules. A management fee might start at 0.5-1.5% of assets under management, but clients with larger balances often negotiate rates as low as 0.25%, especially if they bring significant business to the bank. Additional charges apply for transactions, legal services, or specialized investments.
The catch? Hidden costs accumulate. A client might pay a flat fee for portfolio management but incur separate charges for custody, tax planning, or even travel arrangements for family meetings. Transparency varies—some institutions provide itemized breakdowns, while others leave clients guessing until the annual bill arrives.
5. They Navigate Geopolitical Risks Better Than Most
Private banking institutions excel in crisis scenarios. When sanctions hit a country, they help clients restructure holdings. When a currency collapses, they facilitate conversions without triggering capital controls. Their global reach means a client in Hong Kong can access liquidity in Zurich while their family in Dubai manages real estate in London—all under one umbrella.
This agility comes at a price: reputational risk. Institutions caught facilitating sanctions evasion or money laundering face severe penalties. The 2020 case where HSBC Private Banking was fined $1.9 billion for AML failures is a stark reminder that even elite players aren’t above scrutiny.
6. Technology Is Transforming—but Not Disrupting—Them
Private banking institutions were slow to adopt digital tools, but now they’re leveraging AI, blockchain, and cybersecurity to enhance discretion. For instance:
- Biometric authentication replaces physical signatures for high-value transactions.
- Predictive analytics help advisors spot market shifts before they happen.
- Private blockchain networks enable secure, auditable transfers without exposing client identities to public ledgers.
Yet the human element remains critical. A client might use a mobile app to monitor investments, but major decisions still hinge on relationships with trusted advisors—not algorithms.
"Private banking isn’t about technology; it’s about trust. If a client can’t pick up the phone and speak to someone who understands their family’s legacy, no app will save the relationship."
— Former Head of Wealth Management, European Private Bank
7. They’re Under Siege—But Not Going Anywhere
Private banking institutions face three existential threats:
1. Regulatory pressure (tax transparency, AML laws)
2. Competition from fintechs (digital wealth managers like Nutmeg)
3. Client demands for ESG alignment (environmental, social, governance investing)
Yet their resilience lies in adaptation. They’ve already absorbed digital tools, expanded into ESG products, and even partnered with fintechs to offer hybrid services. The ultra-wealthy aren’t abandoning them—they’re demanding more from them.
How These Facts Connect
Private banking institutions thrive at the intersection of wealth preservation, legal ambiguity, and elite access. Their ability to blend discretion with sophistication ensures they remain the go-to for those who can’t afford—or don’t trust—alternatives. The secrecy isn’t just about hiding money; it’s about controlling narratives, whether financial, familial, or political.
The table below contrasts three core pillars of their business model:
| Pillar | Strength | Weakness |
|---|---|---|
| Exclusivity | High-net-worth clients pay premium fees for bespoke services. | Limited scalability; reliant on a small, wealthy client base. |
| Global Reach | Cross-border transactions and tax optimization unmatched by retail banks. | Exposure to geopolitical risks and regulatory crackdowns. |
| Discretion | Confidentiality attracts clients prioritizing privacy over transparency. | Vulnerability to money-laundering allegations and reputational damage. |
Conclusion
Private banking institutions are more than financial intermediaries—they’re guardians of legacy. Their ability to straddle legal, technological, and ethical boundaries ensures they’ll remain relevant, even as the world changes around them. For their clients, the appeal isn’t just about returns; it’s about security, control, and continuity. Yet the sector’s future hinges on one question: Can they balance innovation with tradition? If they succeed, they’ll evolve into even more powerful tools for the ultra-wealthy. If they fail, they may find themselves replaced by more agile, transparent alternatives.Comprehensive FAQs
Q: Are private banking institutions only for the ultra-rich?
While the largest players focus on high-net-worth individuals (typically $1M+ in assets), some institutions offer private banking lite for affluent clients with smaller portfolios. Fees and services scale with the client’s needs, but the core premise—personalized, high-touch service—remains.
Q: How do private banking institutions make money?
Revenue streams include: - Management fees (0.5-1.5% of assets under management) - Transaction fees (for trades, currency exchanges, or legal services) - Commissions (from private equity, art sales, or insurance products) - Custody fees (for holding physical assets like gold or real estate) Most charge a combination of these, with fees negotiated annually.
Q: Can I open an account with a private bank if I’m not a citizen?
Yes, but residency or citizenship often helps. Many private banking institutions require proof of significant wealth (e.g., $1M+ in liquid assets) and may prioritize clients with ties to their jurisdiction. Non-residents can still open accounts, but due diligence is stricter, and some banks limit services for non-clients.
Q: Are private banking institutions legal everywhere?
Most operate within legal frameworks, but jurisdictions vary. Switzerland, Singapore, and the UAE are hubs due to strong banking laws and tax neutrality. However, institutions in offshore centers (e.g., Cayman Islands, Panama) face scrutiny over money-laundering risks. The OECD’s CRS has reduced secrecy, but loopholes remain for sophisticated structures.
Q: What’s the difference between private banking and wealth management?
Private banking is a subset of wealth management. While all private banks offer wealth management, not all wealth managers provide private banking services. The key difference: - Private banking = personalized, relationship-driven service with high-touch advisors. - Wealth management = broader term covering investment advisory, financial planning, and asset allocation (often digital or hybrid).
Q: Do private banking institutions invest my money, or just hold it?
They do both, but the approach depends on the client’s goals. Some prefer passive custody (holding assets securely with minimal intervention), while others opt for active management (stocks, bonds, private equity, or alternative assets like wine or rare art). The bank’s role shifts from safekeeper to strategist based on the client’s needs.
Q: How do I know if a private bank is reputable?
Look for: - Regulatory licenses (e.g., Swiss FINMA, UK FCA, or Singapore MAS approval). - Client testimonials (though these can be curated). - Transparency reports (how they handle AML, tax compliance, and conflicts of interest). - Independence (family offices or independent advisors often have fewer conflicts than universal banks). Avoid institutions with frequent regulatory fines or ties to controversial figures.
Q: What happens if my private bank goes bankrupt?
Most private banking institutions are separate legal entities from their parent banks, meaning client assets are ring-fenced. However, in extreme cases (e.g., Credit Suisse’s 2023 collapse), governments may step in to protect deposits. Custody accounts (holding physical assets) are generally safer than investment portfolios, which carry market risk. Always confirm deposit insurance limits in your jurisdiction.
