The Complete Overview of Income Percentile Age
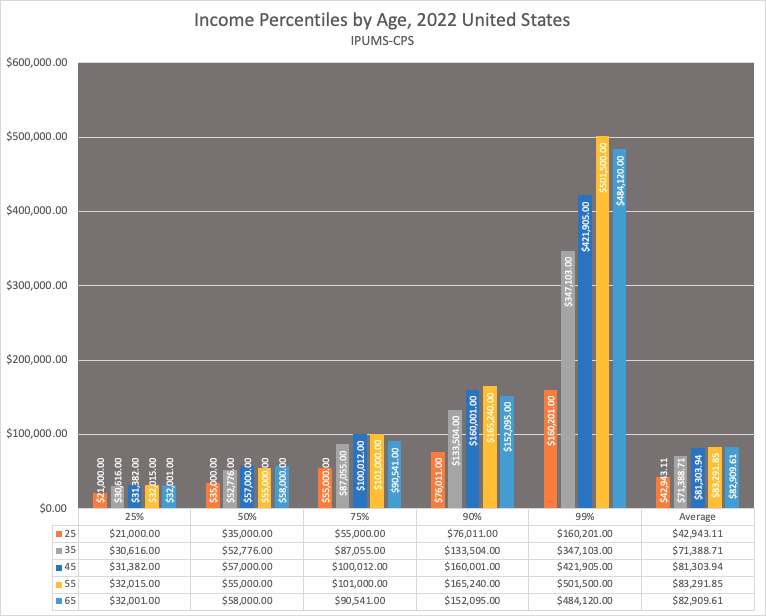
Income percentile age isn’t a static number but a dynamic snapshot of where someone stands in the economic hierarchy at a specific life stage. Unlike raw salary figures, which can fluctuate with industry, location, or career pivots, this metric adjusts for age-related benchmarks. A software engineer in San Francisco at age 32 might earn $180,000 but rank in the 90th percentile for their age group, while a similarly paid lawyer in Birmingham could drop to the 60th percentile due to higher cost of living or different career trajectories. The distinction matters because financial security isn’t just about absolute income—it’s about whether that income aligns with the expectations of your age cohort. The power of income percentile age lies in its ability to predict long-term outcomes. Research from the Federal Reserve and OECD consistently shows that those in the top quartile by age 35 are far more likely to achieve wealth accumulation by retirement, not because they earn more in absolute terms, but because their income trajectory allows for earlier investments in assets like real estate or equities. Conversely, someone in the bottom quartile at 35 faces a steep uphill battle, as the compounding effects of delayed savings, higher debt burdens, and limited access to high-yield opportunities widen the gap over time. This isn’t just about personal responsibility—it’s about structural advantages that begin in early adulthood.Historical Background and Evolution
The concept of income percentile age gained traction in the late 20th century as economists sought to measure economic mobility beyond traditional GDP metrics. Early work by Thomas Piketty and other inequality researchers highlighted how wealth distribution became increasingly skewed toward the top percentiles, but the focus remained on static snapshots rather than age-adjusted comparisons. The turning point came in the 2000s, when the Great Recession exposed how deeply income percentile age influenced recovery rates. Those in the top 20% by age 40 saw their net worth rebound within five years; those in the bottom 40% often took a decade or more to return to pre-crisis levels. Today, the metric is embedded in financial planning tools, from robo-advisors like Betterment to employer-sponsored retirement calculators. Banks use variations of it to assess mortgage risk, while wealth managers incorporate percentile benchmarks into client portfolios. Even dating platforms like Hinge have reportedly experimented with income percentile age filters, though privacy concerns have limited widespread adoption. The shift reflects a broader recognition that financial health isn’t a one-size-fits-all concept—it’s tied to generational context, regional economies, and the timing of life decisions like marriage or parenthood.Core Mechanisms: How It Works
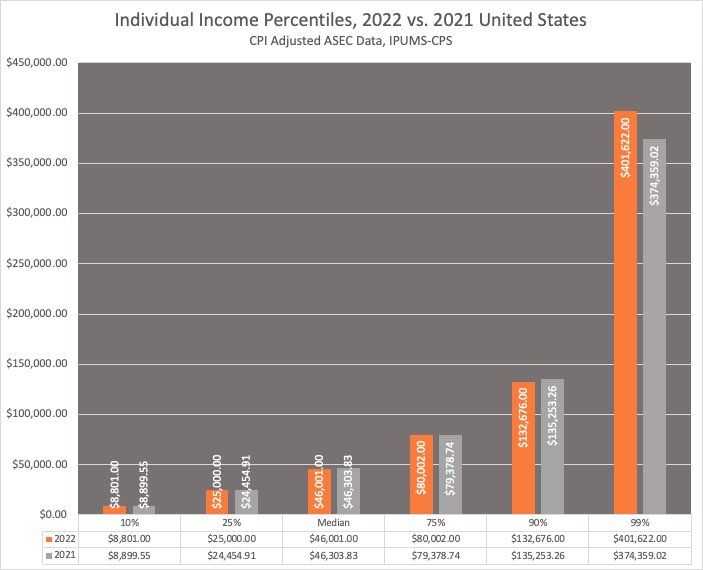
At its core, income percentile age is calculated by comparing an individual’s earnings to a standardized distribution of incomes for their specific age group, typically adjusted for geographic location and inflation. For example, a 38-year-old in London earning £75,000 might rank in the 65th percentile, while the same salary in Manchester could place them in the 80th percentile due to lower regional averages. The data often comes from sources like the Office for National Statistics (ONS) or the U.S. Census Bureau, which publish age-specific income distributions annually. What makes this metric unique is its focus on relative standing rather than absolute figures. A £100,000 salary in your 30s might feel luxurious, but if you’re in the 30th percentile for your age group, it signals potential future instability—perhaps due to high debt, lack of career advancement, or industry-specific risks. Conversely, someone earning £50,000 in the same age bracket but in the 70th percentile may have a stronger financial foundation, thanks to lower living costs, asset ownership, or a more stable career path. The key insight is that percentile rank often correlates with access to wealth-building tools, from employer pension contributions to inheritance patterns.Key Benefits and Crucial Impact
Understanding your income percentile age isn’t just about vanity—it’s a strategic tool for navigating economic uncertainty. For young professionals, it reveals whether their career choices are aligning with industry standards or leaving them vulnerable to stagnation. For mid-career individuals, it highlights whether they’re on track to build generational wealth or risk falling into the "squeezed middle" trap. Even retirees use this metric to assess whether their savings align with expected drawdown rates for their age cohort. The impact isn’t limited to personal finance; it shapes policy debates on wage growth, student debt, and housing affordability. The most compelling argument for tracking income percentile age is its predictive power. Studies from the Brookings Institution show that those in the top 25% by age 30 are three times more likely to own a home by age 40, while those in the bottom 25% often face delayed milestones or none at all. This isn’t just about money—it’s about social mobility. Children of parents in the top quartile for income percentile age are far more likely to attend university, while those in the bottom quartile confront a cycle of limited opportunity. The metric forces a conversation about whether the system is fair—and what individuals can do to tilt the odds in their favor."Income isn’t just a number; it’s a story about where you stand in the economic narrative of your generation. The percentile age tells you whether you’re writing a success story or getting lost in the margins." — Rachel West, Senior Economist at the Resolution Foundation
Major Advantages
- Career Clarity: Identifies whether your salary growth matches industry benchmarks, helping you negotiate raises or pivot careers before falling behind.
- Wealth Accumulation: High percentile ages correlate with earlier access to high-yield investments, homeownership, and retirement savings.
- Risk Mitigation: Low percentile ages signal potential debt traps or stagnant wages, prompting proactive financial planning.
- Policy Advocacy: Highlights systemic inequalities, giving individuals leverage to push for wage transparency or education reforms.
Comparative Analysis
| Metric | Income Percentile Age |
|---|---|
| Focus | Relative standing within age cohorts |
| Key Use Case | Long-term financial planning and mobility |
| Limitation | Doesn’t account for one-time windfalls (inheritance, bonuses) or regional outliers |
Future Trends and Innovations
As artificial intelligence integrates into financial services, income percentile age will likely become more personalized. Banks may offer dynamic benchmarks tailored to an individual’s career field, education level, and geographic mobility. Meanwhile, employers could use anonymized percentile data to identify skill gaps within their workforce, offering targeted upskilling programs. The biggest disruption may come from algorithm-driven financial coaching, where apps like YNAB or Mint provide real-time percentile feedback, suggesting adjustments to spending or saving habits based on age-adjusted goals. The metric’s evolution will also depend on how societies address inequality. If wage stagnation persists, income percentile age could become a rallying cry for policy changes—such as stronger union protections or student debt relief—designed to lift entire cohorts out of the lower percentiles. For individuals, the trend suggests a shift toward proactive financial identity management, where tracking percentile age isn’t just about keeping up with peers but actively shaping their economic destiny.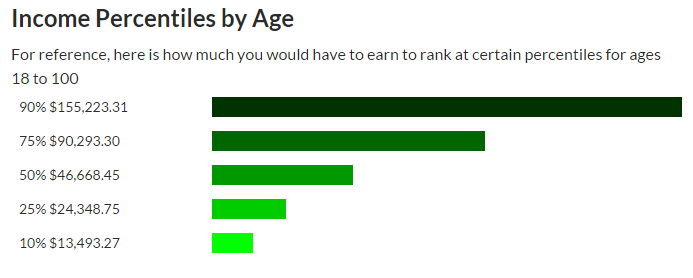
Conclusion
Income percentile age is more than a financial statistic—it’s a lens through which to view the opportunities and constraints of modern life. Ignoring it means risking the assumption that hard work alone guarantees progress, when in reality, the system often rewards those who start in the right percentile. The good news is that this metric isn’t fixed; with deliberate career choices, debt management, and strategic investments, individuals can shift their standing over time. The challenge lies in recognizing that financial success isn’t just about earning more—it’s about earning in the right way, at the right time, relative to your peers. For policymakers, the takeaway is clear: economic mobility requires more than GDP growth—it demands structures that help people move up the percentile ladder. For individuals, the lesson is simpler: know your number, understand the rules of the game, and play to win.Comprehensive FAQs
Q: How often should I check my income percentile age?
Annually is ideal, especially after major life events like career changes, marriage, or parenthood. Many financial platforms now offer real-time percentile tracking, but even a manual check using government income distribution data provides valuable insights.
Q: Does income percentile age vary by country?
Yes. For example, a 35-year-old in Sweden earning €50,000 might rank in the 70th percentile, while the same salary in Poland could place them in the 40th percentile due to differences in average wages and cost of living. Always use locally adjusted benchmarks.
Q: Can I improve my income percentile age if I’m currently in the bottom quartile?
Absolutely. Strategies include negotiating higher salaries, switching to higher-paying industries, reducing high-interest debt, or investing in skills that command premium wages. Some studies suggest that those who move from the 20th to the 60th percentile by age 40 see a 20% increase in lifetime wealth compared to peers who stay stagnant.
Q: How do student loans affect income percentile age?
Student debt can depress percentile rankings for years, especially if repayments consume a large portion of take-home pay. For example, a 28-year-old with £30,000 in student loans might earn £40,000 but rank in the 30th percentile due to high monthly obligations, while a peer with no debt could rank in the 50th percentile with the same salary.
Q: Is income percentile age the same as net worth percentile?
No. Income percentile age measures earnings relative to peers, while net worth percentile accounts for assets (home, investments) minus liabilities (debt). Someone in the 80th percentile for income might rank in the 40th percentile for net worth if they’ve spent aggressively on lifestyle costs, while a frugal earner in the 50th percentile could climb into the top quartile for net worth through disciplined saving.
