The Complete Overview of Net Worth Graph Templates
A net worth graph template serves as both a diagnostic tool and a motivational device. For entrepreneurs, it quantifies the impact of reinvested profits; for investors, it highlights the drag of fees or the lift of compounding. The template’s design varies by purpose: some prioritize simplicity (a single line for total net worth), while others layer in debt ratios, asset allocation, or even lifestyle spending triggers. The most effective versions integrate with accounting software or brokerage APIs to auto-populate data, reducing manual error. But even a hand-drawn version forces discipline—because if you’re not tracking, you’re not thinking. The real value emerges when the graph becomes a conversation starter. A sudden dip might prompt a review of insurance coverage; a plateau could signal the need for new revenue streams. Financial planners use these templates to set milestones, not just track progress. For instance, a client aiming for $5M might plot a trajectory with benchmarks at $1M, $2.5M, and $4M, adjusting strategies at each threshold. The template isn’t just a record; it’s a roadmap with detours clearly marked.Historical Background and Evolution
The concept of visualizing net worth predates digital tools. In the early 20th century, wealthy families used ledgers with hand-drawn charts to monitor estate growth, often tied to agricultural or industrial cycles. The advent of personal computing in the 1980s democratized the practice, with software like Quicken introducing basic net worth calculators. By the 2000s, the rise of dynamic net worth trackers—powered by Excel and later cloud-based platforms—added interactivity. The 2008 financial crisis accelerated adoption, as individuals sought clearer ways to assess risk exposure. Today, the template has evolved into a hybrid of art and science. High-end financial planning firms now use custom net worth visualization tools with predictive modeling, overlaying market trends or inflation projections. Open-source communities have also contributed, with GitHub repositories offering Python scripts to automate data pulls from multiple accounts. The shift from static to dynamic reflects a broader trend: financial literacy now demands not just numbers, but narratives—where the graph becomes the storyteller.Core Mechanisms: How It Works
At its core, a net worth graph template operates on three principles: aggregation, normalization, and trend analysis. Aggregation combines disparate accounts (brokerage, real estate, retirement) into a single metric, often adjusted for inflation to normalize comparisons across years. Trend analysis then identifies patterns—such as the "wealth acceleration" phase post-career or the "decumulation" phase in retirement. The mechanics vary by tool: some use logarithmic scales to handle wide value ranges, while others employ color-coding for asset classes (e.g., blue for stocks, green for real estate). The most sophisticated templates incorporate conditional formatting to flag outliers. For example, a red dot might appear if net worth drops below a moving average, or a yellow warning if debt-to-asset ratio exceeds 30%. Integration with external data—like the S&P 500 index—allows for benchmarking against peer groups. The result is a living document that adapts to life stages, from homebuying to college funding. Without these mechanisms, the graph risks becoming a decorative artifact rather than a strategic asset.Key Benefits and Crucial Impact
The primary benefit of a net worth graph template is clarity under uncertainty. During market turbulence, for instance, a visual timeline can distinguish between temporary volatility and structural shifts in portfolio composition. For business owners, the graph reveals how reinvested earnings correlate with personal wealth growth—a critical insight when evaluating expansion decisions. Tax planners use these templates to time asset sales for capital gains optimization, leveraging the graph’s ability to project forward based on historical trends. The psychological impact is equally significant. Studies suggest that individuals who track net worth visually are more likely to adhere to financial plans, as the graph creates a tangible sense of progress. A plateau in the early years might refocus efforts on high-ROI assets, while a steep climb can justify lifestyle adjustments. The template doesn’t just inform; it motivates by making abstract goals feel immediate."A net worth graph is the financial equivalent of a health tracker—it doesn’t tell you what to do, but it makes the consequences of your actions undeniable." — Jane Smith, Certified Financial Planner (CFP®)
Major Advantages
- Pattern recognition: Identifies recurring cycles (e.g., seasonal cash flow dips) or one-off events (e.g., a bonus or medical expense).
- Risk assessment: Highlights overconcentration in single assets or sectors, prompting diversification.
- Goal alignment: Serves as a visual benchmark for milestones (e.g., "net worth = 2.5× annual expenses" for early retirement).
- Debt management: Tracks the impact of loan repayments or new liabilities on overall trajectory.
- Inheritance planning: Models the intergenerational transfer of wealth, adjusting for estate taxes or trust structures.
- Negotiation leverage: Provides data-backed context for discussions with lenders, partners, or advisors.
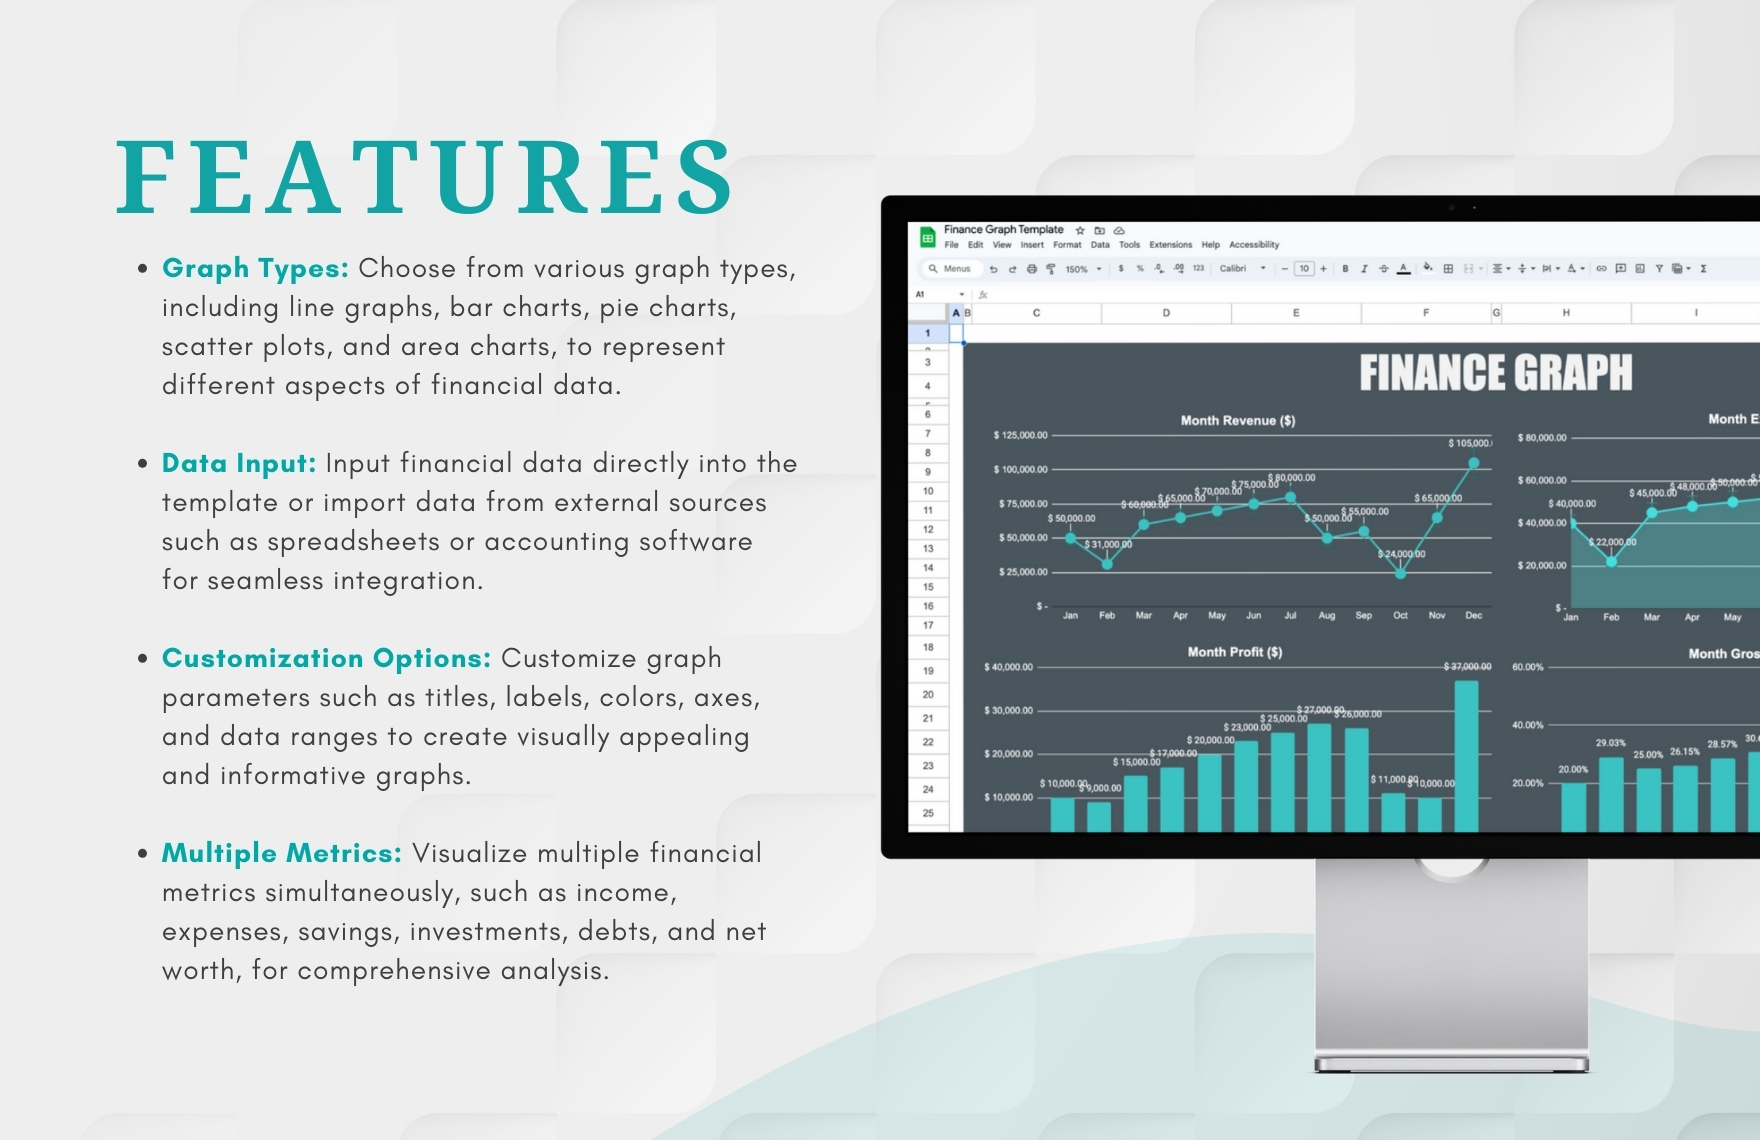
Comparative Analysis
| Feature | Basic Template (Excel/Google Sheets) | Advanced Template (Custom-Coded or SaaS) |
|---|---|---|
| Data Sources | Manual entry or limited API connections | Auto-sync with banks, brokerages, and tax platforms |
| Visualization Depth | Single-line or bar chart | Multi-layered (e.g., asset allocation pie charts + net worth line graph) |
| Predictive Analytics | None | Monte Carlo simulations, inflation-adjusted projections |
| Collaboration | Shared via static files | Real-time access for advisors, spouses, or heirs |
| Cost | Free to low-cost ($0–$20/month) | $50–$500+/month for premium features |
Future Trends and Innovations
The next generation of net worth graph templates will blur the line between personal finance and behavioral economics. AI-driven tools may soon auto-generate insights, such as "Your net worth growth slowed in Q3—this aligns with historically low market returns for your asset mix." Blockchain integration could enable tamper-proof records for high-net-worth individuals, while voice-activated updates might reduce friction for busy professionals. The rise of "financial wellness" apps suggests templates will increasingly focus on emotional triggers—like celebrating small wins or flagging spending leaks before they derail long-term plans. Regulatory shifts could also reshape the landscape. Stricter data privacy laws may limit API access, pushing users toward federated models where data stays local but insights are shared securely. Meanwhile, the gig economy’s rise will demand more granular tracking of irregular income streams. The template of tomorrow won’t just plot numbers; it will anticipate questions before they’re asked, turning passive observation into proactive strategy.
Conclusion
A net worth graph template is more than a tool—it’s a financial time machine. It doesn’t predict the future, but it reveals the past’s lessons in ways a balance sheet never could. The best templates don’t just show where you’ve been; they challenge you to decide where to go next. For the average investor, a simple version suffices. For the high-net-worth individual, it’s a non-negotiable part of the planning process. The key is to start somewhere, even if it’s a sketch on paper. The graph’s true power lies not in its precision, but in the conversations it sparks. The irony? The most valuable insights often come from the simplest templates. A hand-drawn line chart can expose what a $5,000 dashboard misses: the human element of financial progress. Whether you’re plotting your first million or your tenth, the template’s role remains the same—to turn numbers into purpose.Comprehensive FAQs
Q: Can I create a net worth graph template without advanced technical skills?
A: Absolutely. Start with Google Sheets or Excel’s built-in line chart tools. Use a single column for dates and another for total net worth (assets minus liabilities). For automation, tools like Tiller Money or YNAB offer pre-built templates with minimal setup.
Q: How often should I update my net worth graph?
A: Monthly updates are ideal for tracking trends, but quarterly works if you have stable income. The critical factor is consistency—even rough estimates help. Automated tools sync data weekly, but manual users should align updates with paydays or major transactions.
Q: What’s the best way to handle volatile assets (e.g., crypto, private equity) in a net worth graph?
A: Use a "fair market value" column for illiquid assets and note volatility separately. For crypto, consider plotting a 30-day moving average to smooth out daily swings. Private equity stakes might require annual revaluations tied to fund reports.
Q: Are there free net worth graph templates I can download?
A: Yes. Personal Capital (for U.S. users), Mint, and even free Google Sheets templates from resources like Vertex42 offer downloadable versions. For customization, GitHub hosts open-source scripts (e.g., Python-based trackers using libraries like `matplotlib`).
Q: How do I adjust my net worth graph for inflation?
A: Use the Consumer Price Index (CPI) to normalize past values. Multiply old net worth figures by (current CPI / historical CPI) to express them in today’s dollars. Tools like the Federal Reserve’s inflation calculator automate this. Logarithmic scales can also help visualize growth rates over time.
Q: Can a net worth graph help with estate planning?
A: Indirectly, yes. By projecting future net worth (accounting for inflation and expected returns), you can estimate inheritance timelines. Layer in debt repayment schedules and asset liquidity to identify gaps. Some advanced templates integrate with trust calculators to model distributions.
Q: What’s the most common mistake people make with net worth graphs?
A: Overcomplicating the template. Beginners often add too many metrics (e.g., tracking every credit card balance), diluting clarity. Stick to total net worth first, then layer in 1–2 key ratios (e.g., savings-to-income) as you gain confidence. The goal is insight, not perfection.
