
The Complete Overview of High and Ultra High Net Worth Individuals
The term "high and ultra high net worth" isn’t just a financial label—it’s a gateway to a parallel economy. While the lower tiers of wealth (say, $1 million to $5 million) often rely on traditional banking and public markets, those at the top operate in a system where private banks, family offices, and bespoke legal structures dictate the terms. The transition from "wealthy" to "ultra high net worth" typically occurs when an individual’s assets exceed $30 million, but the real inflection point is when their wealth becomes too large to manage through conventional channels. At this stage, wealth preservation isn’t just about growth; it’s about protection from systemic risks—currency devaluations, political instability, or even the whims of a single market crash. What distinguishes this cohort isn’t just the scale of their assets but the velocity of their capital. High net worth individuals might hold liquid investments in stocks or bonds, but ultra high net worth families often deploy wealth into illiquid, high-control assets: private equity stakes, vineyard holdings in Bordeaux, or even entire sports teams. The latter group doesn’t just invest—they acquire influence. A single purchase of a majority stake in a biotech firm can reshape an industry overnight. Meanwhile, the ultra-wealthy’s children are often groomed not just to inherit but to operate within these systems, often through trustee roles or seats on corporate boards before they turn 30.Historical Background and Evolution
The modern era of high and ultra high net worth individuals traces back to the post-WWII financial revolution, when tax laws, deregulation, and the rise of private banking created the conditions for exponential wealth accumulation. The 1970s and 1980s saw the emergence of the first true "family offices"—private entities designed to manage the complex portfolios of the ultra-wealthy. Before then, wealth was often tied to land, industry, or royal bloodlines. But as capital markets globalized, so did the strategies of those who controlled it. The offshore boom of the 1990s and 2000s further accelerated this shift, allowing high and ultra high net worth individuals to decouple their assets from national taxation through jurisdictions like the Cayman Islands, Luxembourg, and Singapore. Today, the landscape is dominated by three primary wealth structures: the self-made entrepreneur (think tech founders or hedge fund managers), the inherited dynasty (old money families like the Rockefellers or Rothschilds), and the hybrid model—where new wealth is layered onto existing family trusts. The most successful of these groups don’t just preserve capital; they engineer it. A 2023 study by UBS and PwC found that the global population of ultra high net worth individuals grew by 9.3% annually over the past decade, but the real growth is in the illiquid asset class—where private equity, real estate, and alternative investments now account for nearly 60% of their portfolios. This shift reflects a fundamental truth: liquidity is a luxury the ultra-wealthy can no longer afford.Core Mechanisms: How It Works
The operational framework for high and ultra high net worth individuals is built on three pillars: legal structuring, asset diversification, and access to exclusive capital. At the legal level, trusts—particularly dynasty trusts that can last for generations—are the cornerstone. These entities allow wealth to bypass estate taxes, remain private, and even avoid forced heirship laws in certain jurisdictions. A single trust can hold assets across multiple countries, with discretionary powers granted to trustees who may never be related to the beneficiaries. This isn’t just tax avoidance; it’s wealth immortality. Diversification, however, extends beyond stocks and bonds. The ultra-wealthy deploy capital into non-traditional assets with high barriers to entry: rare art (where a single Picasso can outlast a portfolio), wine collections (certain vintages appreciate at rates unmatched by public markets), and even digital assets—though the latter remains a contentious play. The key insight is that these assets aren’t just investments; they’re status symbols with liquidity controls. A high net worth individual might sell a stake in a company; an ultra high net worth family might wait decades for a rare book or vintage to reach its peak value before monetizing it.Key Benefits and Crucial Impact
The advantages of operating within this financial ecosystem are structural, not just financial. High and ultra high net worth individuals don’t just earn more—they move differently. Their wealth isn’t static; it’s a dynamic force that shapes industries, politics, and even culture. A single donation to a university’s endowment fund can secure a family’s legacy for centuries. A quiet investment in a startup can preemptively reshape an entire sector before it goes public. The impact isn’t just in the balance sheet; it’s in the invisible levers of power that most never see. The psychological dimension is equally critical. For those who have spent decades building or inheriting wealth, the primary goal shifts from accumulation to control. It’s not about getting richer; it’s about ensuring that wealth never leaves the family. This mindset explains why so many ultra high net worth individuals are willing to pay premiums for privacy—whether through anonymous shell companies or discreet residences in low-key locales. The game isn’t about being seen; it’s about being untouchable. > "Wealth at this level isn’t about money. It’s about the freedom to operate outside the rules that bind everyone else." > — A former senior partner at a Swiss private bank, speaking off the recordMajor Advantages
- Tax Optimization Through Jurisdictional Arbitrage: High and ultra high net worth individuals leverage multiple legal systems to minimize liabilities. Trusts in Delaware, foundations in Liechtenstein, and holding companies in the British Virgin Islands create layers of protection that retail investors can’t replicate.
- Access to Exclusive Investment Vehicles: From private credit funds to pre-IPO stakes in unicorn startups, the ultra-wealthy gain entry to deals decades before they hit public markets. This isn’t just early access; it’s structural advantage.
- Generational Wealth Engineering: Tools like grantor retained annuity trusts (GRATs) and intentionally defective grantor trusts (IDGTs) allow families to transfer wealth across generations with minimal tax impact, effectively turning a $50 million fortune into a $200 million dynasty over three lifetimes.
- Political and Regulatory Influence: While not all high net worth individuals engage in direct lobbying, those at the ultra level often fund think tanks, political action committees, or even sovereign wealth funds to shape policies that protect their assets. The line between philanthropy and influence is deliberately blurred.
- Liquidity Control: Unlike public investors, high and ultra high net worth individuals dictate the terms of their exits. They don’t need to sell; they choose when to sell. This allows them to weather market downturns while others panic.
- Global Mobility Without Borders: The ultra-wealthy aren’t tied to a single country. Citizenship by investment programs (like those in Malta or the Caribbean) allow them to opt into jurisdictions that offer residency, tax breaks, and even passports—without ever setting foot in a consulate.

Comparative Analysis
| High Net Worth Individuals ($1M–$30M) | Ultra High Net Worth Individuals ($30M+) |
|---|---|
| Primary wealth sources: Public stocks, real estate, business ownership. | Primary wealth sources: Private equity, family trusts, alternative assets (art, wine, rare collectibles). |
| Wealth management: Traditional banks, robo-advisors, basic estate planning. | Wealth management: Family offices, private banks, bespoke legal structures (e.g., Swiss trusts, Cayman LLCs). |
| Tax strategy: Standard deductions, retirement accounts, occasional offshore accounts. | Tax strategy: Jurisdictional layering, dynasty trusts, charitable remainder trusts, and anonymous entities. |
| Liquidity profile: Most assets are marketable within weeks. | Liquidity profile: Illiquid assets dominate (60%+ of portfolio), with exits timed over decades. |
| Influence: Limited to local business networks or niche industries. | Influence: Global—shaping policy, funding research, acquiring controlling stakes in strategic sectors. |
Future Trends and Innovations
The next decade will see two major shifts in how high and ultra high net worth individuals deploy capital. First, digital assets—particularly tokenized real estate and private equity—are poised to become a core component of their portfolios. While cryptocurrencies remain volatile, blockchain-based securities (where a fraction of a luxury property or a startup can be traded like a stock) offer the ultra-wealthy fractional ownership at scale. Second, AI-driven wealth management is already being adopted by family offices to predict market shifts with precision unseen in traditional finance. These tools don’t just analyze data; they anticipate regulatory changes, geopolitical risks, and even cultural trends that could impact asset values. The second trend is the privatization of wealth itself. As governments increase scrutiny on offshore accounts and capital controls tighten, high and ultra high net worth individuals are moving assets into harder-to-trace structures—such as private credit funds, agricultural land in emerging markets, or even space-related ventures. The goal isn’t just growth; it’s insulation. The days of holding a single currency or relying on a single market are fading. The future belongs to those who can diversify risk across time, geography, and asset classes—while keeping it all opaque.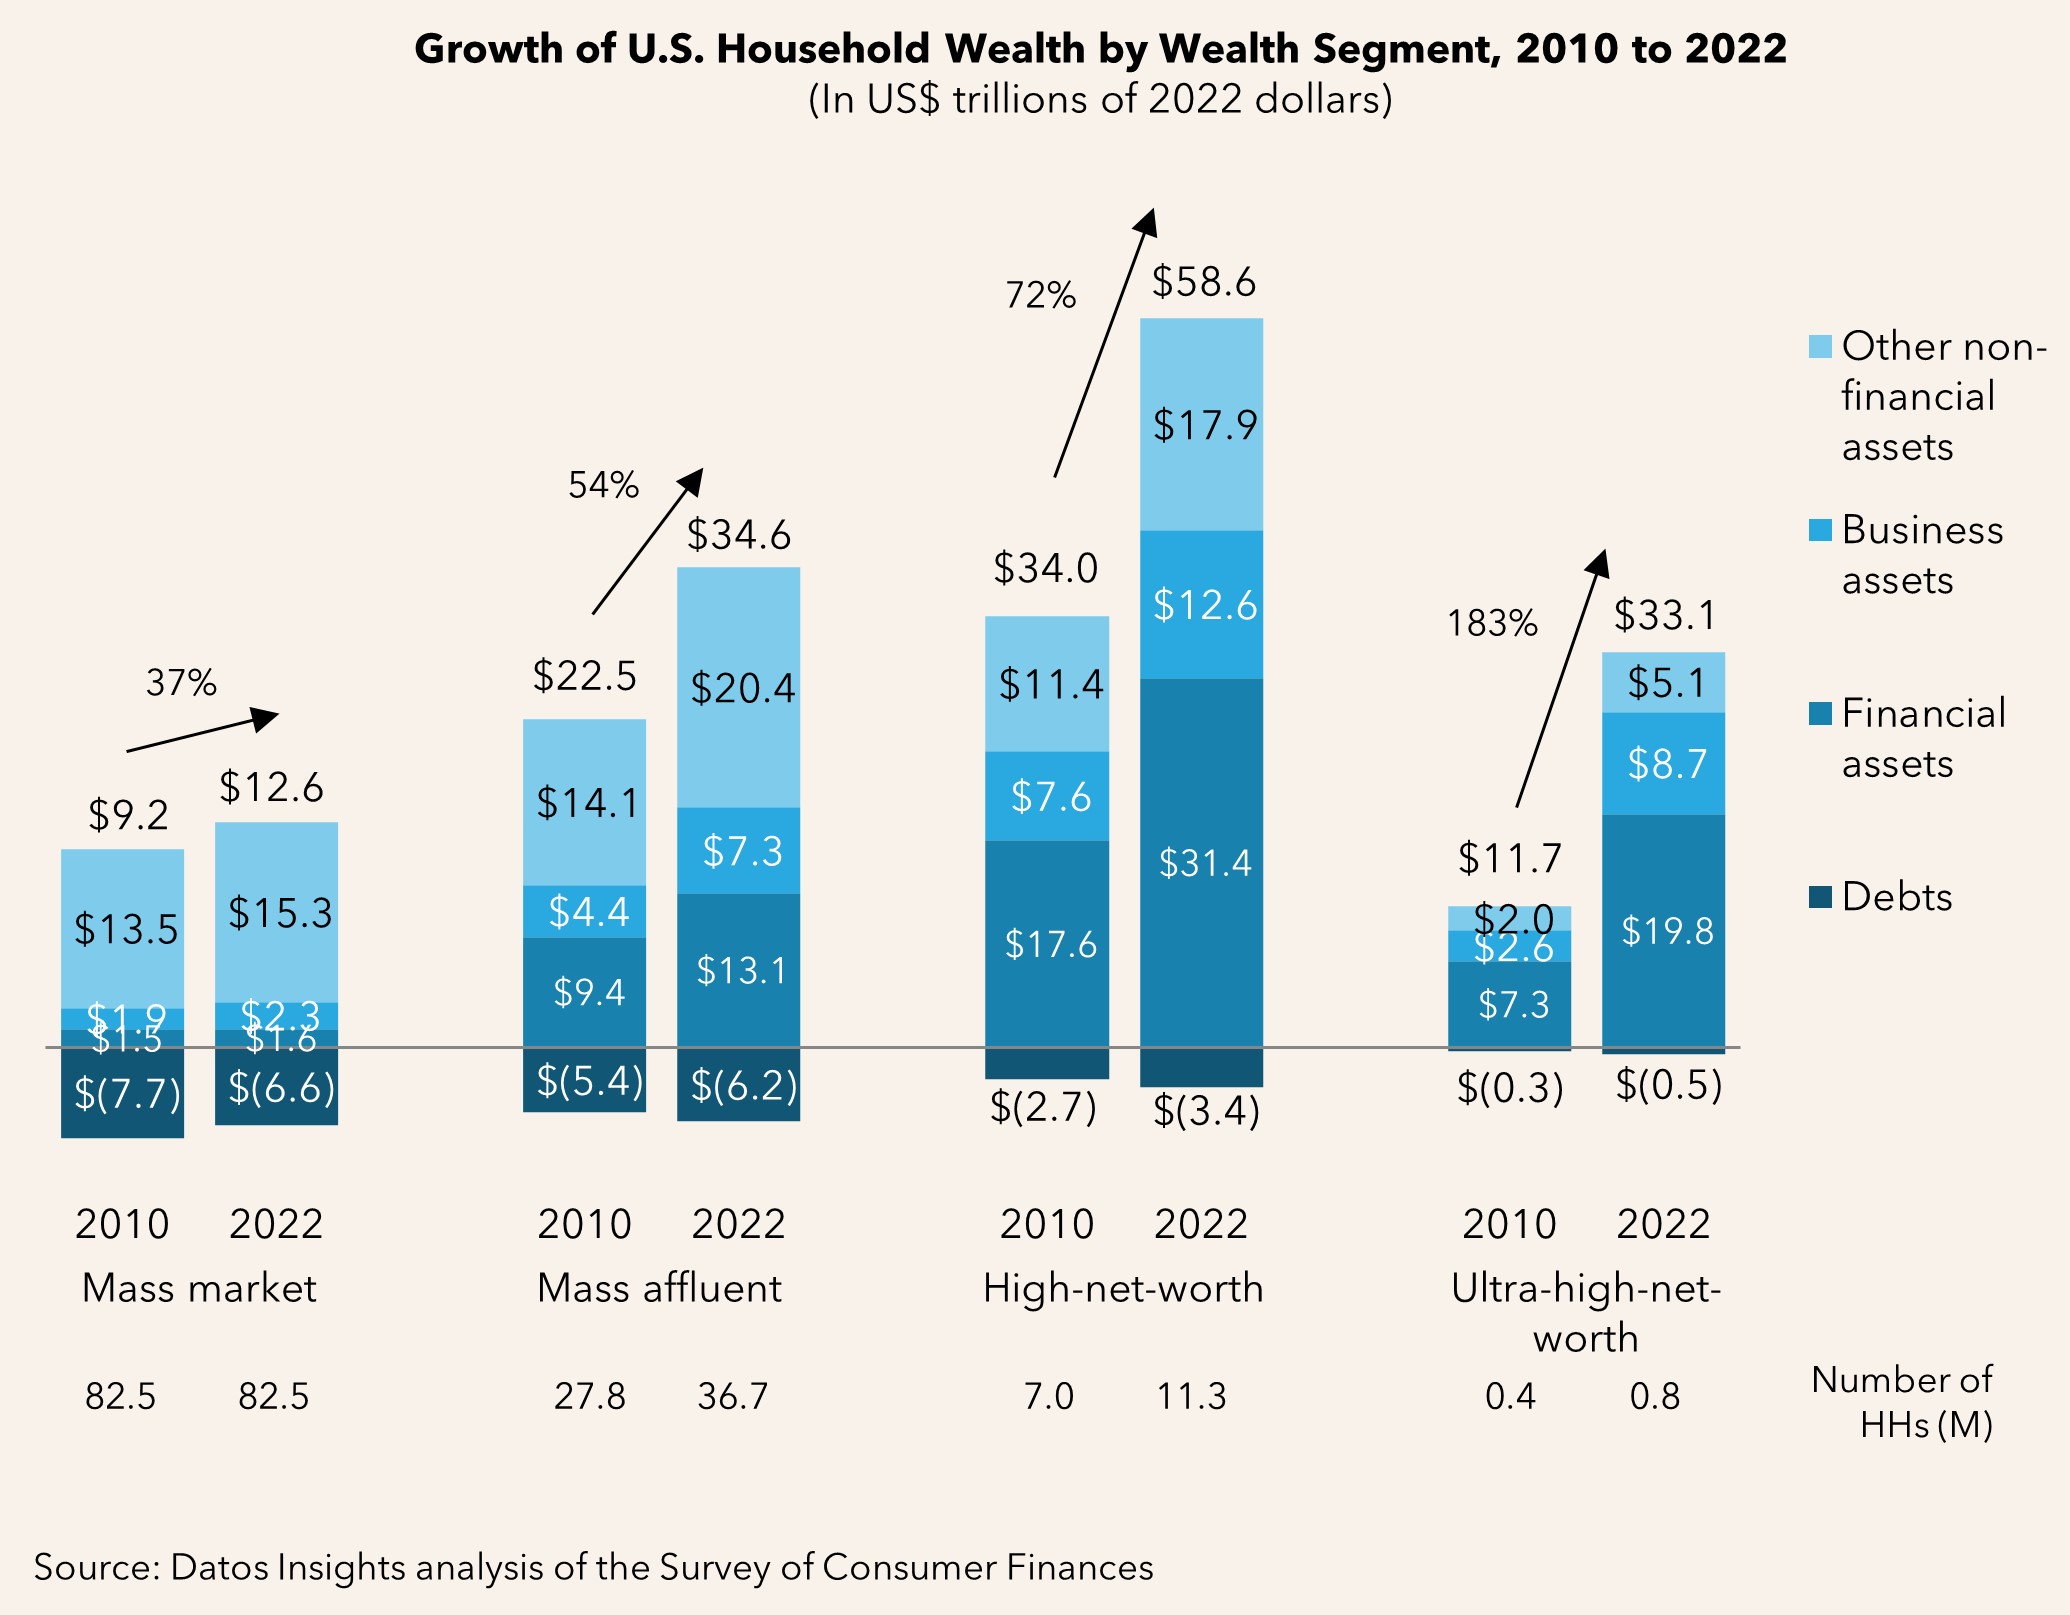
Conclusion
High and ultra high net worth individuals don’t just represent the top of the financial pyramid—they define its architecture. Their strategies aren’t about getting rich; they’re about staying rich. The tools they use—trusts, private banks, alternative investments—aren’t just financial instruments; they’re weapons of persistence. For the rest of the population, wealth is a destination. For them, it’s a fortress. The most striking realization is that this isn’t a static group. The barriers to entry are rising, but so are the costs of failure. A single misstep—whether in tax compliance, asset allocation, or succession planning—can unravel decades of work. This is why the ultra-wealthy don’t just hire advisors; they build ecosystems. Their wealth isn’t in a bank account; it’s in the people, laws, and structures they’ve spent lifetimes constructing.Comprehensive FAQs
Q: What’s the difference between a high net worth individual and an ultra high net worth individual?
A: The threshold is typically $30 million in liquid and illiquid assets. High net worth individuals (HNWIs) often rely on public markets and traditional banking, while ultra high net worth individuals (UHNWIs) deploy capital into private equity, trusts, and alternative assets—often with multi-generational planning. The latter also have access to exclusive investment vehicles and legal structures that HNWIs can’t replicate.
Q: How do high and ultra high net worth individuals protect their wealth from taxes?
A: They use a combination of jurisdictional layering (holding assets in low-tax countries), dynasty trusts (which can last for generations), and charitable structures (like donor-advised funds) to reduce taxable exposure. Some also employ grantor retained annuity trusts (GRATs) or intentionally defective grantor trusts (IDGTs) to transfer wealth tax-efficiently across generations.
Q: Are most ultra high net worth individuals self-made or born into wealth?
A: The data varies by region, but studies suggest that about 60% of ultra high net worth individuals are self-made, while the remaining 40% come from inherited wealth or a combination of both. However, even self-made billionaires often preserve wealth through trusts and family offices, ensuring it remains within the family for decades.
Q: What’s the most common mistake high net worth individuals make when managing their wealth?
A: Overconcentration in liquid assets (like public stocks) and underestimating estate taxes. Many HNWIs assume their wealth is safe until they face probate battles or unexpected tax liabilities. Ultra high net worth families avoid this by diversifying into illiquid, high-control assets and using trusts to bypass inheritance taxes.
Q: How do high and ultra high net worth individuals access investments that aren’t available to the public?
A: Through private placement memorandums (PPMs), family office networks, and exclusive fund offerings. Many UHNWIs gain access to pre-IPO startups, private credit deals, or rare asset auctions through relationships with private bankers, venture capital firms, or auction houses like Sotheby’s. Some even create their own investment vehicles to deploy capital into niche markets.
Q: Is it possible for a high net worth individual to transition into the ultra high net worth category?
A: Yes, but it requires strategic scaling. Most who make the jump diversify into private equity, real estate, or alternative assets—areas where illiquidity allows for higher long-term returns. However, the transition isn’t just about growing wealth; it’s about structuring it in ways that preserve and multiply capital across generations. Many hire family office managers or private bankers to facilitate this shift.
Q: What role does privacy play in wealth management for the ultra-rich?
A: Privacy is a core pillar. Ultra high net worth individuals use anonymous shell companies, trust structures, and discreet residences to minimize public exposure. This isn’t just about avoiding paparazzi; it’s about protecting assets from legal risks, political instability, or even kidnapping threats (a real concern for some global families). Jurisdictions like Switzerland, Monaco, and the British Virgin Islands are favored for their legal secrecy and asset protection laws.
Q: How do high and ultra high net worth individuals handle succession planning?
A: They start decades in advance. The most effective strategies involve dynasty trusts, education funds for heirs, and structured exit plans for business owners. Many also pre-train their children—often by placing them in trustee roles or board seats—to ensure the next generation understands wealth preservation, not just spending. Without proper planning, even multi-billion-dollar fortunes can disappear in a single generation due to poor management or legal challenges.
