
The Complete Overview of Ultra High Net Worth Investment
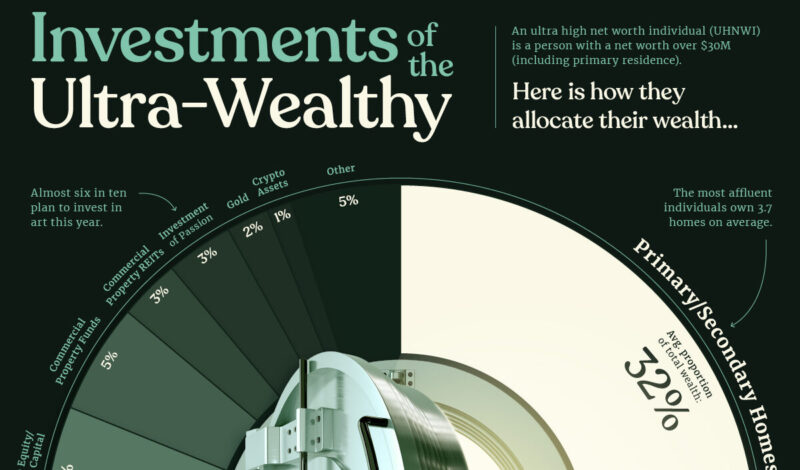
Ultra high net worth investment thrives in the shadow markets—where private equity, real estate syndications, and alternative assets dominate. Unlike passive index investing, this approach demands active ownership: board seats, operational oversight, or even co-investment with sovereign funds. The wealthiest individuals don’t just allocate capital; they architect financial ecosystems. For example, a single family might control a $15 billion war chest deployed across three private equity funds, a vineyard in Bordeaux, and a stake in a biotech firm—each asset class serving a distinct purpose in their long-term preservation strategy. The psychology behind these moves is as critical as the mechanics. Liquidity isn’t the goal; optionality is. A UHNW investor might hold a $1 billion stake in a distressed airline not for dividends, but because they believe in the long-term consolidation of global aviation. The trade-off? Illiquidity for asymmetric upside. This isn’t gambling—it’s high-stakes chess, where each move is calculated to outlast economic cycles.Historical Background and Evolution
The modern era of ultra high net worth investment traces back to the 1980s, when deregulation and the rise of private equity allowed families like the Rockefellers and Rothschilds to diversify beyond public markets. The 1990s tech boom accelerated the trend, as fortunes built on Silicon Valley IPOs were reinvested into early-stage startups and venture capital. By the 2000s, the globalization of capital—coupled with the emergence of family offices—created a new class of investors who could deploy billions in illiquid assets without public scrutiny. The financial crisis of 2008 acted as a catalyst. While public markets crashed, private assets like commercial real estate and distressed debt became goldmines for those with the capital to act swiftly. Post-crisis, alternative investments—hedge funds, private credit, and even art and wine collections—became staples of UHNW portfolios. Today, the average ultra high net worth investor allocates 60% of their portfolio to alternatives, a stark contrast to the 10-15% typical of institutional investors.Core Mechanisms: How It Works
At its core, ultra high net worth investment relies on three pillars: access, expertise, and patience. Access comes from exclusive networks—whether through private bankers, family offices, or direct relationships with fund managers. Expertise isn’t just financial; it’s operational. Many UHNW investors sit on advisory boards or deploy capital with hands-on management in sectors like agriculture, infrastructure, or renewable energy. Patience is non-negotiable: illiquid assets require 5-10 year horizons, and exits often hinge on strategic sales to other institutions rather than public markets. The mechanics extend beyond traditional asset classes. Structured notes, synthetic investments, and even insurance-linked securities are tools in their arsenal. For instance, a $20 billion endowment might use derivatives to hedge against currency fluctuations while simultaneously betting on inflation-linked assets like timber or farmland. The result? A portfolio that adapts to macroeconomic shifts without the volatility of public equities.Key Benefits and Crucial Impact
The primary allure of ultra high net worth investment lies in its non-correlation to public markets. While the S&P 500 fluctuates, a diversified portfolio of private equity, real estate, and collectibles often moves on its own trajectory—shielding wealth from systemic risks. The secondary benefit? Tax optimization. Offshore structures, private placement bonds, and dynasty trusts allow UHNW families to minimize estate taxes while maintaining control over assets across generations. Yet the impact extends beyond personal finance. These investors drive economic shifts—funding entire industries from space tourism to cell-based meat production. Their capital doesn’t just grow; it reshapes global supply chains."The richest families don’t invest in markets—they invest in the future." — A former CIO of a $50 billion family office
Major Advantages
- Illiquidity premiums: Private assets often outperform public markets over long horizons due to lower valuation volatility.
- Tax-efficient structures: Offshore entities, private trusts, and customized legal entities reduce exposure to capital gains and inheritance taxes.
- Industry influence: Direct stakes in strategic sectors (e.g., semiconductors, AI) allow investors to shape policy and competition.
- Legacy preservation: Multi-generational wealth strategies ensure capital remains intact despite market cycles or geopolitical instability.
Comparative Analysis
| Ultra High Net Worth Investment | Traditional Wealth Management |
|---|---|
| Asset allocation: 60-80% in private/alternative assets | Asset allocation: 70-90% in public equities, bonds, and ETFs |
| Liquidity horizon: 5-15 years per asset | Liquidity horizon: Days to months (public markets) |
| Risk profile: Concentrated in high-growth, high-risk sectors | Risk profile: Diversified across low-volatility assets |
Future Trends and Innovations
The next frontier in ultra high net worth investment lies in digital assets and geopolitical arbitrage. While Bitcoin and Ethereum remain speculative for most, institutional-grade crypto funds—backed by family offices and sovereign wealth funds—are emerging as liquidity hedges. Meanwhile, geopolitical fragmentation is creating new opportunities in sanctioned economies, where capital flows are restricted for traditional investors but accessible to those with discretionary networks. Another shift? Impact investing at scale. UHNW families are increasingly tying capital to ESG-driven ventures—not out of altruism, but because sustainable industries (renewables, biotech) offer long-term tailwinds. The result? A blurring of lines between profit and purpose in elite wealth strategies.
Conclusion
Ultra high net worth investment isn’t about beating the market—it’s about controlling the game. The strategies employed by the wealthiest individuals are decades in the making, built on access, expertise, and an acceptance of illiquidity. For those outside this circle, the barriers are high: minimum checks of $10 million+, years of due diligence, and relationships forged over generations. Yet the principles are universal: diversify beyond paper assets, prioritize optionality over liquidity, and think in multi-decade cycles. The ultra high net worth investor doesn’t follow trends—they create them.Comprehensive FAQs
Q: What’s the minimum capital required to participate in ultra high net worth investment?
A: While there’s no strict threshold, most private equity funds and family office opportunities require commitments of $10 million or more. Smaller allocations (e.g., $1-5 million) may be possible in secondary markets or syndicated deals, but access to primary offerings typically demands $50 million+.
Q: How do ultra high net worth investors mitigate risk in illiquid assets?
A: Diversification across unrelated asset classes (e.g., farmland + private credit + art) is key. Many also use structured vehicles like SPVs (Special Purpose Vehicles) to isolate risk. Additionally, long-term holding periods allow them to ride out volatility in sectors like infrastructure or biotech.
Q: Are there tax advantages specific to ultra high net worth investment?
A: Yes. Private placement bonds, offshore trusts, and dynasty trusts can defer or eliminate capital gains and estate taxes. Some jurisdictions (e.g., Mauritius, Singapore, Cayman) offer zero capital gains tax on certain structured investments. However, compliance with FATCA and CRS regulations is critical to avoid penalties.
Q: Can retail investors gain indirect exposure to ultra high net worth strategies?
A: Indirectly, yes—through funds of funds, ETFs tracking private markets, or high-net-worth platforms like Hedgeable or Titan. However, returns will be diluted compared to direct allocations. For true alignment, syndicated investments (e.g., via Republic or Wefunder) offer fractional access to pre-IPO startups—though with higher risk.
Q: What’s the biggest misconception about ultra high net worth investment?
A: The myth that it’s only for gamblers or those chasing quick returns. In reality, most UHNW strategies are conservative—focused on capital preservation and controlled growth over decades. The "high risk" perception comes from illiquidity and concentration, not speculative trading. Patience, not recklessness, defines success in this space.
