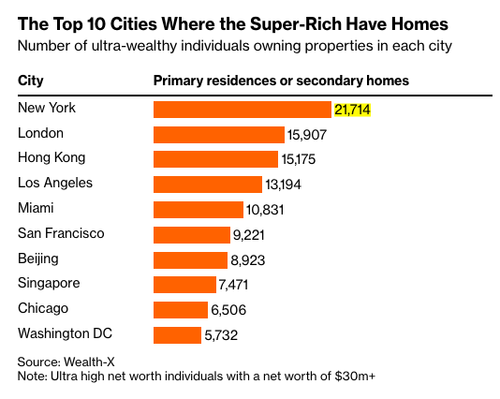
Where It All Began
The origins of U.S. high-net-worth client acquisition as a distinct discipline trace back to the 1970s, when the first wave of post-WWII wealth—oil barons, industrialists, and old-money dynasties—began fragmenting. The Kennedy family’s financial struggles in the 1960s, for example, forced the firm that would later become Brown Brothers Harriman to innovate. They stopped treating clients as passive investors and started treating them as partners in legacy preservation. The result? A playbook that would define the industry for decades: identify the next generation’s pain points, solve them before they become problems, and charge premium fees for the privilege. The early signs of this approach were subtle but telling. In 1978, a small Boston-based trust company quietly hired a former Harvard Law School professor to advise on estate planning for clients with assets over $20 million. The professor’s fee? $150 an hour. The firm’s revenue from that single practice? $3 million in its first year. Word spread. By 1985, every major bank had a "private client group," even if their strategies were still rooted in 19th-century relationship banking. The difference between the leaders and the laggards? The leaders understood that wealth wasn’t just about money—it was about control. Control over taxes, control over succession, control over the narrative of one’s legacy.The Early Signs
The first major crack in the old model appeared in the late 1980s, when a wave of corporate raiders and tech entrepreneurs began accumulating fortunes that dwarfed traditional dynasties. These new clients didn’t want trust officers—they wanted dealmakers. The firms that adapted fastest were the ones that could offer more than asset allocation: they could introduce a client to a private equity GP, help structure a leveraged buyout, or connect them to a discreet buyer for a struggling family business. The result? A feedback loop where the ultra-wealthy became the primary drivers of their own wealth growth, and the firms that served them became indispensable. The second early sign was the rise of the "family office" as a distinct entity. Before the 1990s, wealthy families handled their affairs through trust departments or ad-hoc committees. But as fortunes grew more complex—and more sensitive—families began hiring dedicated teams to manage everything from philanthropy to real estate. The first modern family office, launched by the Walton family in 1990, wasn’t just a wealth vehicle; it was a client acquisition machine. By employing former bankers and lawyers, it created a pipeline of high-net-worth individuals who would later seek out similar services from external advisors.The Turning Point
The real inflection point arrived in the early 2000s, when the first generation of tech billionaires—many of whom had never dealt with traditional wealth managers—began hitting critical mass. These clients didn’t care about quarterly reports or market commentary. They wanted speed, discretion, and innovation. The firms that couldn’t deliver were left behind. The ones that could? They rewrote the rules. A single example: in 2003, a Silicon Valley-based wealth manager offered a client—then worth just $1.2 billion—a dedicated team of tax attorneys, a private jet for family travel, and access to a network of art dealers. The client’s assets under management at that firm? $8 billion within five years."We used to think our clients were our customers. Now we know our clients are our product. The more we understand their psychology, the more we can charge for solving their problems—before they even know they have them." — Former Head of Private Wealth, Goldman Sachs (2015)The turning point wasn’t just about money. It was about psychology. The ultra-wealthy don’t just want financial advice—they want validation. They want to be told they’re smart, that their risks are calculated, that their legacy will endure. The firms that mastered this dynamic didn’t just acquire clients; they cultivated dependencies.

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1995–2000 | The rise of "concierge wealth management." Firms like Credit Suisse and J.P. Morgan introduced 24/7 access, dedicated concierge services, and even personal shopping assistants for clients. The message was clear: your time is more valuable than your money. |
| 2001–2007 | The post-9/11 era saw a surge in "discretionary" accounts, where clients handed over full control to advisors in exchange for guaranteed returns. This period also marked the first major use of data analytics to predict which high-net-worth individuals were most likely to switch advisors—often before they even considered it. |
| 2008–2015 | The crisis accelerated the shift to "outcome-based" fees, where advisors were paid based on achieving specific goals (e.g., "preserve $500M for the next generation") rather than asset size. This era also saw the first major forays into digital wealth platforms for HNWIs, though trust remained low—until firms like Wealthfront proved they could secure ultra-high-net-worth clients with algorithmic advice. |
Lessons From the Journey
- Wealth is a lifestyle, not a balance sheet. The most successful firms don’t sell products—they sell membership in an exclusive ecosystem where clients feel understood.
- Legacy anxiety is the ultimate driver. Clients don’t just want to grow money; they want to control its narrative for future generations.
- Discretion isn’t just a feature—it’s a moat. The ultra-wealthy will pay more to keep their affairs private than to maximize returns.
- Network effects matter more than scale. A single connection to a private equity fund or a tax arbitrage opportunity can outweigh years of relationship-building.
- The biggest risk isn’t losing clients—it’s losing relevance. Firms that fail to innovate in areas like crypto custody or impact investing risk being seen as obsolete.
- Emotional intelligence beats financial acumen. The ability to read a client’s unspoken fears (e.g., "Will my kids squander this?") is more valuable than any CFA designation.
Where Things Stand Today
Today, U.S. high-net-worth client acquisition is a $1.5 trillion industry, but the game has changed in ways few predicted. The old model—where a charismatic banker would schmooze a client into a lifetime relationship—has been replaced by data-driven prospecting. Firms now use predictive analytics to identify which high-net-worth individuals are most likely to divorce, inherit, or start a business in the next 18 months. They track social media for signs of financial distress (e.g., a sudden interest in "offshore trusts" on LinkedIn). And they’ve weaponized referral networks, where a single satisfied client can unlock a pipeline of 50 others through discreet introductions. Yet for all the technology, the core remains the same: trust. The ultra-wealthy still want what they’ve always wanted—a partner who understands their world, anticipates their needs, and never makes them feel like just another number. The firms that get this right aren’t the ones with the biggest ad budgets or the fanciest offices. They’re the ones that can make a $10 billion client feel like they’re the only one in the room.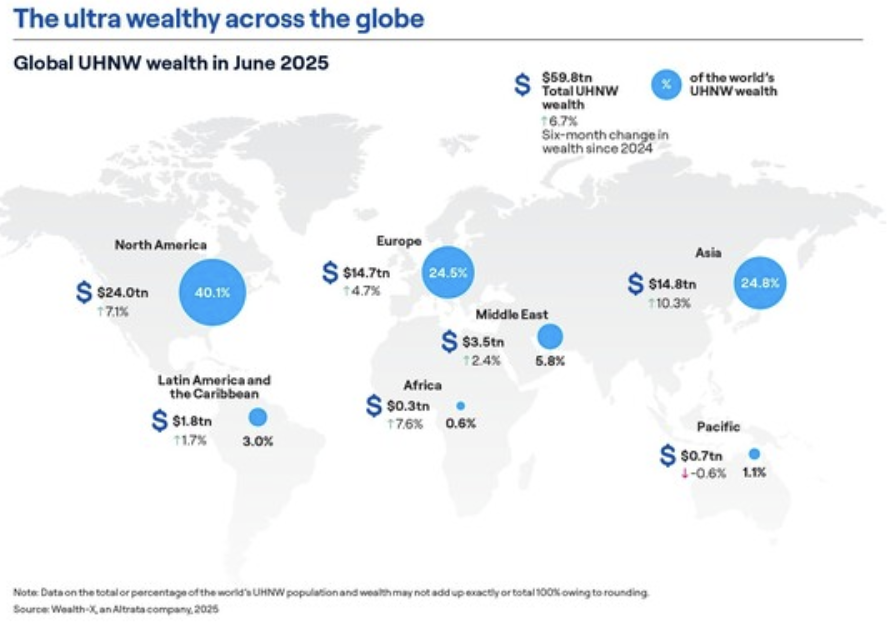
Conclusion
The evolution of U.S. high-net-worth client acquisition is a story of adaptation—from old-money trust to new-money discretion, from product sales to problem-solving, from relationship banking to psychological engineering. The firms that thrive today aren’t the ones with the deepest pockets or the flashiest brands. They’re the ones that have learned to speak the language of the ultra-wealthy: not in terms of returns, but in terms of control, legacy, and belonging. The next decade will test this model like never before. As wealth becomes more concentrated in fewer hands—and as those hands grow more diverse—the firms that succeed will be the ones that can anticipate the next shift before it happens. Whether that’s through AI-driven personalization, deeper integration with family offices, or entirely new models of wealth structuring, one thing is certain: the playbook is being rewritten in real time.Comprehensive FAQs
Q: What’s the biggest misconception about acquiring high-net-worth clients?
The biggest myth is that it’s about money. In reality, it’s about access—access to networks, expertise, and solutions that most advisors can’t provide. A $10 million client isn’t impressed by a 10% return; they’re impressed by a tax strategy that saves them $50 million over a decade.
Q: How do firms identify potential high-net-worth prospects?
Modern firms use a mix of public records, private databases, and behavioral signals. For example, tracking real estate purchases in luxury markets, monitoring divorce filings in high-net-worth jurisdictions, or analyzing social media for keywords like "trust planning" or "offshore structuring." Some even use predictive modeling to flag individuals likely to inherit or receive a windfall.
Q: Is cold outreach still effective for HNW client acquisition?
Direct outreach works, but only if it’s hyper-personalized. A generic email about "wealth management" will get ignored. The most effective cold touches reference a specific pain point (e.g., "I noticed you recently acquired a vineyard in Bordeaux—here’s how we’ve helped other clients with similar assets navigate French inheritance laws").
Q: What’s the role of technology in modern HNW acquisition?
Technology is used at every stage: CRM systems track client interactions, AI identifies prospects, and blockchain analytics help uncover hidden assets. However, the most successful firms still rely on human judgment—especially when it comes to assessing a prospect’s psychological profile and legacy motivations.
Q: How do firms compete with robo-advisors for HNW clients?
Robo-advisors can’t compete on discretion, customization, or legacy planning. The ultra-wealthy will pay premium fees for white-glove service, but they won’t tolerate impersonal algorithms. The best firms use tech to enhance relationships—not replace them.
Q: What’s the most underrated skill in HNW client acquisition?
Active listening. The ability to hear what a client isn’t saying—whether it’s fear of a market crash, concern about family infighting, or anxiety over succession—is far more valuable than any financial model. The best advisors don’t just solve problems; they preempt them by reading between the lines.
Q: How has the rise of family offices changed the game?
Family offices have become both competitors and clients. Some ultra-wealthy families now manage their own affairs, reducing demand for external advisors. Others outsource specific needs (e.g., tax planning, real estate) to firms that can’t compete on scale. The result? A fragmented landscape where firms must specialize in niches—like "philanthropy structuring" or "crypto custody"—to remain relevant.
Q: What’s the future of HNW client acquisition?
The next frontier lies in predictive legacy planning. Firms that can anticipate a client’s needs before they arise—whether it’s structuring a trust for a grandchild before they’re born or identifying a tax loophole before Congress closes it—will dominate. Expect more AI-driven scenario modeling, deeper integration with private equity and venture networks, and an even greater focus on emotional and psychological alignment over pure financial metrics.
