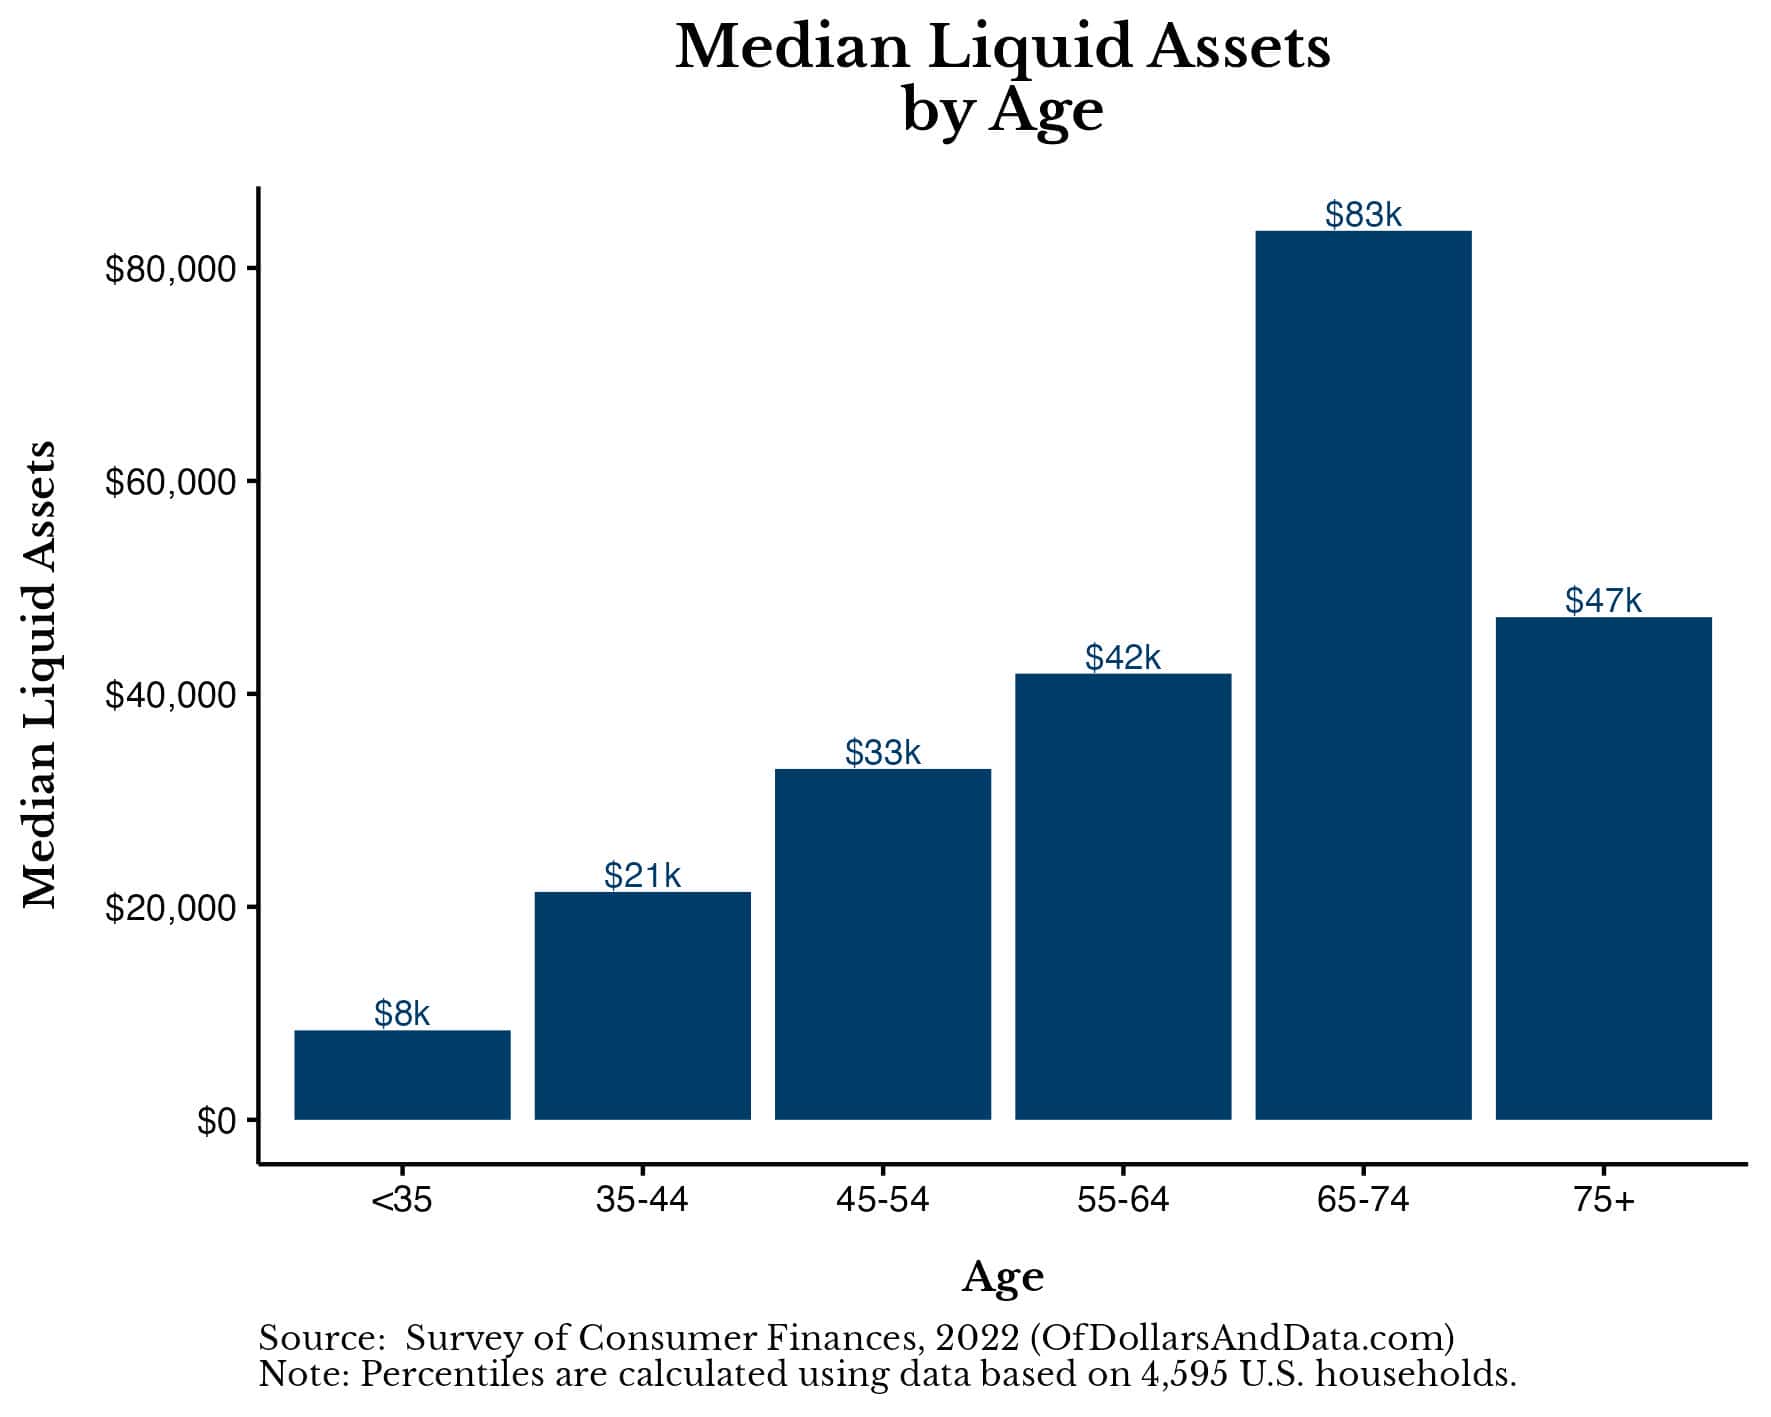
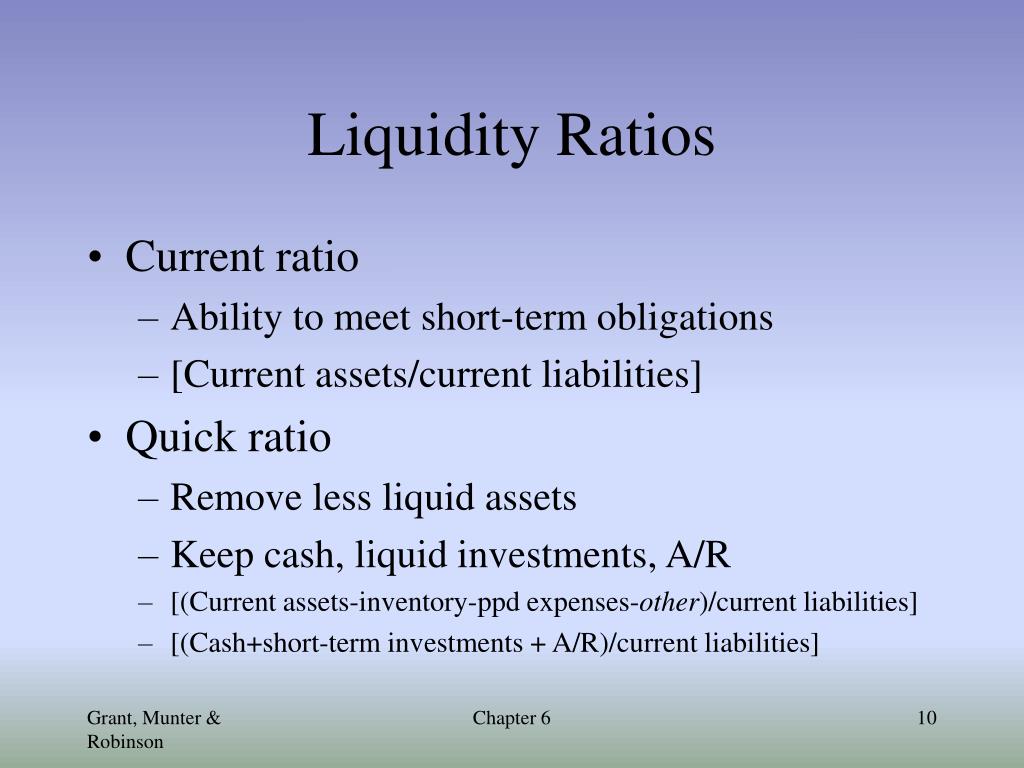
 The ratio’s power lies in its simplicity and its ability to cut through noise. It doesn’t require complex modeling or access to proprietary data. You calculate it by dividing your highly liquid assets (cash, money market funds, short-term bonds, easily tradable stocks) by your total net worth, then multiplying by 100. The result? A percentage that tells you, at a glance, how much of your wealth is actually working for you in the short term. For high-net-worth individuals, this can mean the difference between maintaining lifestyle during a market correction or being forced into fire sales. For average earners, it’s the difference between bouncing back from a setback or spiraling into debt.
Common Myths About What Is Liquid Assets to Net Worth Ratio
The liquid assets to net worth ratio is frequently misunderstood, often because financial advice defaults to broad strokes. One persistent myth is that a high net worth automatically translates to financial flexibility. The reality is that net worth is a static number—it doesn’t account for how quickly assets can be converted to cash. A family with a $3 million home and $1 million in retirement accounts might have a net worth of $4 million, but if their liquid assets are only $300,000, their ratio is a paltry 7.5%. That’s not flexibility; that’s a ticking time bomb. The ratio reveals that wealth concentration in illiquid assets can be just as risky as debt. Another misconception is that liquidity is only relevant for emergencies. While cash reserves are critical for unexpected expenses, the liquid assets to net worth ratio serves a broader purpose: it measures your ability to seize opportunities. A low ratio might force you to pass on a once-in-a-lifetime investment because you lack the liquidity to act. Conversely, a high ratio (say, 40% or above) signals that you’re positioned to navigate volatility without selling assets at depressed values. The ratio isn’t just about survival—it’s about agility. A third myth is that liquidity ratios are only useful for the ultra-wealthy. In truth, the principle applies at every income level. A young professional with $50,000 in net worth and $15,000 in liquid savings has a 30% ratio—a far healthier position than someone with the same net worth but only $5,000 in cash. The ratio adjusts for scale, making it a universal tool for assessing financial resilience. The key is recognizing that liquidity isn’t a binary concept (either you have cash or you don’t); it’s a spectrum that changes with your goals and risk tolerance.Myth 1: "A High Net Worth Means You’re Financially Secure"
The assumption that net worth alone equals security ignores the liquid assets to net worth ratio entirely. A net worth of $10 million might sound formidable, but if 90% of that is tied up in private equity, real estate, or hard-to-sell assets, you’re effectively operating with a $1 million liquid buffer. That’s why billionaire investors like Warren Buffett—despite their vast net worth—maintain portfolios with liquid assets to net worth ratios often exceeding 30%. The ratio exposes the cold truth: wealth concentration in illiquid assets can be just as paralyzing as debt. During the 2008 financial crisis, many high-net-worth individuals found themselves unable to access capital because their assets were locked in illiquid vehicles, forcing them into distressed sales or leveraged positions. The disconnect between net worth and liquidity is particularly stark in markets where asset classes diverge. Consider a scenario where a portfolio is heavily weighted in collectibles, fine art, or unlisted businesses. Even if the appraised value is high, converting those assets to cash can take months—or require steep discounts. The liquid assets to net worth ratio quantifies that risk. For example, a family with a $5 million home and $2 million in art collections might have a net worth of $7 million, but if their liquid assets are only $500,000, their ratio is a mere 7%. That’s not security; that’s exposure. The ratio forces a hard question: How much of your wealth can you actually put to work when you need it?Myth 2: "Liquidity Only Matters in Crises"
While emergencies are the most obvious use case for liquidity, the liquid assets to net worth ratio plays a quieter but equally critical role in opportunity capture. A low ratio can blindside you when market conditions shift. For instance, during the COVID-19 pandemic, companies with strong liquidity ratios were able to acquire distressed assets at fire-sale prices while others were forced to stand on the sidelines. The ratio isn’t just about damage control—it’s about being in the game. A high-net-worth individual with a 15% liquidity ratio might miss out on a $1 million investment opportunity because they lack the cash to deploy, even if their net worth is $50 million. The ratio also reflects your ability to adapt to changing priorities. Life stages demand different levels of liquidity. A young professional saving for a home might prioritize a lower ratio, while a retiree needs a higher one to cover living expenses without selling investments. The liquid assets to net worth ratio evolves with your goals. For example, a couple in their 50s with $3 million in net worth might aim for a 30% liquidity ratio to fund a child’s education or a career pivot, whereas a retiree with the same net worth might target 50% or higher to ensure they don’t need to tap into principal. Ignoring this dynamic can lead to over- or under-preparation.Myth 3: "All Assets Are Liquid If You’re Willing to Sell"
This is the most dangerous myth of all. Not all assets are liquid without cost. Selling a home quickly often means accepting a lower price, especially in a buyer’s market. Private equity stakes may require finding a buyer willing to pay a premium—or settling for a discount. Even publicly traded stocks can be illiquid if they’re thinly traded or subject to volatility. The liquid assets to net worth ratio accounts for these realities by focusing only on assets that can be converted to cash quickly and at fair market value. A portfolio heavy in illiquid assets might look robust on paper, but the ratio reveals the hidden drag. Consider the case of a tech entrepreneur with a $20 million net worth, but only $3 million in liquid assets—a 15% ratio. While the entrepreneur might feel secure, a sudden need for capital (a legal dispute, a business acquisition, or a personal emergency) could force them to sell underperforming assets at a loss. The ratio doesn’t just measure cash reserves; it measures financial freedom. Without it, you’re not just vulnerable to external shocks—you’re at the mercy of your own illiquidity.What Holds Up to Scrutiny
At its core, the liquid assets to net worth ratio is a measure of financial leverage—not in the sense of debt, but in terms of how quickly you can access your wealth. The ratio’s strength lies in its ability to normalize liquidity across different wealth levels. A young professional with $100,000 in net worth and $30,000 in liquid assets has a 30% ratio, which is far healthier than a retiree with $2 million in net worth but only $200,000 in cash (a 10% ratio). The ratio adjusts for scale, making it a fair comparator. What’s considered "good" varies by life stage, but benchmarks exist: financial planners often recommend a liquid assets to net worth ratio of 20–40% for most individuals, with higher targets for those nearing retirement or facing variable income streams."Liquidity isn’t just about having cash—it’s about having the right kind of cash at the right time. The ratio is the litmus test for whether your wealth is working for you or against you." — Jane B., Certified Financial Planner (CFP®)| Common Belief | What the Evidence Says | |--------------------------------------------|-------------------------------------------------------------------------------------------| | "A high net worth means I’m liquid." | Net worth includes illiquid assets; liquidity is a separate metric. | | "I don’t need much liquidity if I’m young."| Emergencies and opportunities don’t wait for retirement. | | "Real estate is always liquid." | Selling a home takes time and may require price concessions. | | "My retirement accounts are liquid." | Early withdrawals often incur penalties; the ratio focuses on immediately accessible cash.| | "A 10% liquidity ratio is fine." | Industry benchmarks suggest 20–40% is healthier for most life stages. |
Why the Confusion Persists
The liquid assets to net worth ratio remains underdiscussed because financial advice often prioritizes long-term growth over short-term flexibility. Advisors focus on asset allocation, diversification, and tax efficiency—all critical—but they frequently overlook the liquidity trade-off. This oversight is partly cultural. In many societies, homeownership and long-term investments are framed as good in absolute terms, without acknowledging their illiquidity. The ratio disrupts that narrative by asking: Good for what? A $5 million home might be a sound investment, but if it ties up 80% of your net worth, it’s not just an asset—it’s a constraint. The confusion also stems from the lack of standardized definitions. What counts as "liquid" varies by context. Some include high-yield savings accounts and CDs, while others exclude them, arguing they’re not immediately accessible. The ratio’s ambiguity allows it to be dismissed as "subjective." Yet, the core principle remains: the ability to convert assets to cash without penalty is the true measure of financial health. Until the industry adopts clearer liquidity benchmarks, individuals will continue to misjudge their own flexibility. The ratio isn’t just a number—it’s a mirror reflecting how well your wealth aligns with your needs.Conclusion
The liquid assets to net worth ratio is one of the most underrated tools in personal finance because it forces a conversation most people avoid: How much of my wealth can I actually use? Net worth is a starting point, but the ratio is the follow-up question that matters. It’s the difference between a balance sheet and a battle plan. For high-net-worth individuals, it’s a safeguard against overconfidence; for average earners, it’s a wake-up call about preparedness. The ratio doesn’t judge your asset choices—it simply reveals their practical implications. The next time you hear someone brag about their net worth, ask: What’s their liquidity ratio? The answer might surprise you. Wealth isn’t just about what you own; it’s about what you can do with it. And in an unpredictable world, that’s the metric that truly counts.Comprehensive FAQs
Q: How do I calculate my liquid assets to net worth ratio?
A: Start by identifying your highly liquid assets—cash, money market funds, short-term bonds, and easily tradable stocks (those that can be sold within 24–48 hours without significant loss). Add these up, then divide by your total net worth (total assets minus liabilities). Multiply the result by 100 to get your percentage. For example, if your liquid assets total $500,000 and your net worth is $2 million, your ratio is 25%.
Q: What’s a "good" liquid assets to net worth ratio?
A: There’s no one-size-fits-all answer, but financial planners often recommend a ratio between 20% and 40% for most individuals. Those nearing retirement or with variable income streams (e.g., entrepreneurs) may aim for 40–60%. The key is aligning the ratio with your risk tolerance and life stage. A young professional saving aggressively might target a lower ratio, while a retiree prioritizing capital preservation will need more liquidity.
Q: Does my home count as a liquid asset?
A: Generally, no. While a home is a valuable asset, selling it quickly often requires concessions (e.g., lower price, rushed sale). The liquid assets to net worth ratio focuses on assets that can be converted to cash without penalty or significant delay. Exceptions might include rental properties in strong markets, but even then, liquidity depends on demand and timing.
Q: Can I improve my liquid assets to net worth ratio without selling assets?
A: Yes. Strategies include:
- Diversifying liquid holdings: Shift a portion of investments to cash equivalents or short-term bonds.
- Reducing illiquid exposure: Gradually sell non-essential illiquid assets (e.g., collectibles) over time.
- Increasing income: Higher cash flow can boost liquid reserves without touching principal.
- Refinancing debt: Convert illiquid debt (e.g., home equity loans) into more manageable, liquid forms.
Q: How does the liquid assets to net worth ratio differ from the liquidity coverage ratio (LCR) used by banks?
A: The liquidity coverage ratio (LCR) is an institutional metric requiring banks to hold enough high-quality liquid assets (HQLA) to cover 30 days of net cash outflows under stress. It’s a regulatory tool designed for systemic stability. The liquid assets to net worth ratio, by contrast, is a personal finance metric focused on individual flexibility. While both measure liquidity, the LCR is about survival for an entire institution, whereas the ratio assesses your ability to adapt as an individual.
Q: What happens if my liquid assets to net worth ratio is too low?
A: A low ratio increases vulnerability to:
- Market downturns: Forced sales of illiquid assets at depressed values.
- Emergencies: Inability to cover unexpected expenses without debt.
- Opportunity costs: Missing out on time-sensitive investments or deals.
- Lifestyle risks: Difficulty maintaining standards during job loss or health crises.