Common Myths About Wealth Transfer for High Net Worth Clients
The first misconception is that wealth transfer for high net worth clients is primarily a legal exercise. In practice, it’s as much about psychology as it is about paperwork. Many assume that simply drafting a will or setting up a trust will preserve family wealth indefinitely. The truth is that without clear communication about values and expectations, even the most airtight legal structure can unravel. Families like the Rockefellers and the Vanderbilts didn’t maintain their fortunes through wills alone—they cultivated a culture of stewardship, where each generation understood not just how to manage wealth, but why it existed in the first place. Another persistent myth is that wealth transfer for high net worth clients is only relevant for those on the verge of retirement. The data tells a different story: the most effective transfers begin decades in advance. A 2022 study by UBS found that families who start planning by their late 40s or early 50s are 40% more likely to successfully pass wealth to the next generation. The reason? Time allows for tax optimization, education of heirs, and the gradual introduction of younger family members into decision-making roles. Waiting until the last minute often means missed opportunities to mitigate estate taxes or align assets with evolving family goals.Myth 1: Offshore accounts are the best way to protect wealth
The idea that wealth transfer for high net worth clients requires moving assets offshore persists, fueled by anecdotes about secret bank accounts in Switzerland or the Cayman Islands. While offshore structures can play a role—particularly for asset protection or diversification—they’re not a panacea. The Criminal Justice Act 2003 in the UK and the Foreign Account Tax Compliance Act (FATCA) in the U.S. have made opaque offshore holdings far riskier. What’s more, the reputational damage of being perceived as hiding wealth can outweigh the tax benefits, especially for families with public profiles. The reality is that modern wealth transfer for high net worth clients relies on a mix of domestic and international strategies, tailored to the client’s specific risks. For example, a U.S.-based family might use a domestic asset protection trust (DAPT) in Nevada or South Dakota for certain assets while holding others in a Swiss foundation—but only after a thorough analysis of tax treaties, reporting requirements, and potential legal challenges. The key is transparency within the family and compliance with local laws, not secrecy.Myth 2: Trusts are a one-size-fits-all solution
Many assume that setting up a trust is sufficient for wealth transfer for high net worth clients, regardless of family size or complexity. In truth, trusts are tools—not magic bullets. A poorly drafted trust can create more problems than it solves, particularly when family dynamics are volatile. For instance, a revocable living trust might simplify probate but offers no asset protection, while an irrevocable trust can shield assets but removes control from the grantor. The best approach depends on whether the goal is tax reduction, creditor protection, or simply ensuring heirs receive assets without court intervention. The most sophisticated families now use trust companies or private trust offices to manage structures dynamically. These entities can adjust trust terms over time, incorporate discretionary distributions based on heirs’ life stages, and even include incentive provisions (e.g., tying distributions to education or philanthropy). The result? A framework that evolves with the family, not a static document filed away and forgotten.Myth 3: Philanthropy is just a tax write-off
Some high net worth individuals view philanthropy as a side benefit of wealth transfer for high net worth clients—a way to reduce taxable estates by donating to charities. While charitable giving can indeed be tax-efficient, the most effective families integrate philanthropy into their wealth strategy as a values-driven engine. For example, the Ford Foundation didn’t just donate assets; it structured its giving to align with long-term social impact goals, ensuring wealth was deployed in a way that reflected the family’s legacy. Today, donor-advised funds (DAFs) and private family foundations are common vehicles, but the most innovative families go further. They use low-interest loans to nonprofits, program-related investments (PRIs), or even impact investing to generate both social returns and financial ones. The lesson? Wealth transfer for high net worth clients isn’t just about moving money—it’s about defining what that money should do in the world.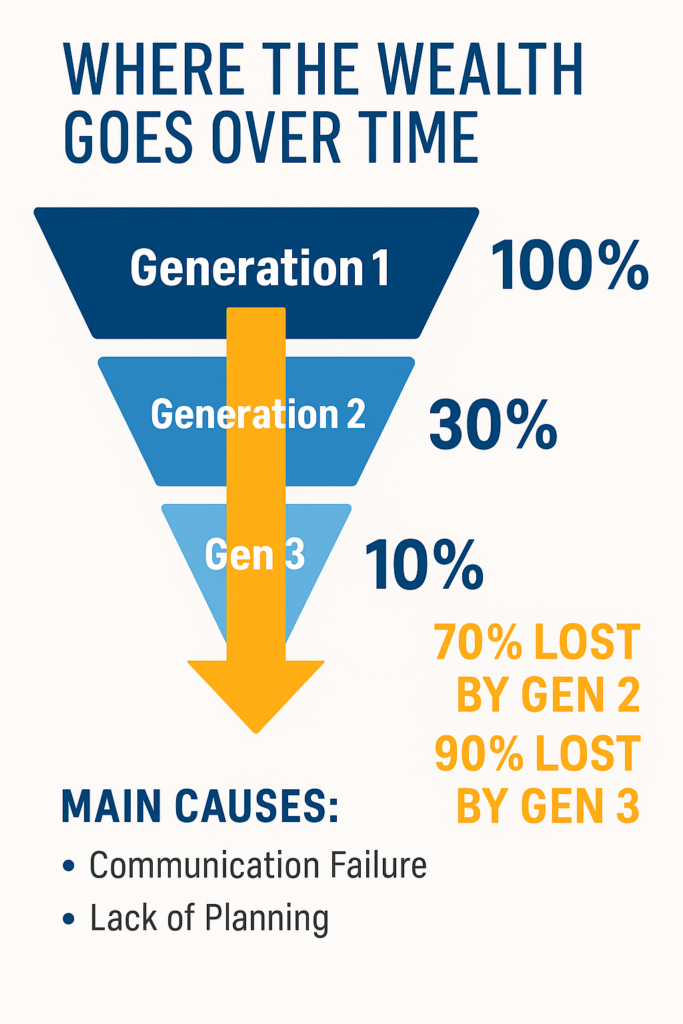
What Holds Up to Scrutiny
At its core, effective wealth transfer for high net worth clients hinges on three verifiable principles: liquidity management, tax arbitrage, and family governance. Liquidity is often the Achilles’ heel—illiquid assets like real estate or private equity can create cash-flow crises during transfers. The solution? Structuring sales or securitization in advance, or using private credit funds to provide liquidity without forcing asset sales. Tax arbitrage, meanwhile, involves leveraging structures like grantor retained annuity trusts (GRATs) or intentionally defective grantor trusts (IDGTs) to minimize estate taxes, but only when the math aligns with the family’s risk tolerance. Family governance is where many strategies fail. The most successful transfers include family constitutions, councils of trustees, and education programs to ensure heirs understand both the mechanics and the ethics of wealth. For instance, the Walton Family Foundation uses a multi-tiered governance model where each generation has a seat at the table, but decisions are made collectively—reducing the risk of reckless spending or internal conflicts."Wealth transfer isn’t about the money—it’s about the story you leave behind. The families that last are the ones who treat it as a narrative, not a transaction." — James E. Hughes Jr., former CEO of the Rockefeller Family Fund
| Common Belief | What the Evidence Says |
|---|---|
| Wealth transfer is a one-time event. | It’s an ongoing process. Families who update strategies every 3–5 years see 30% higher success rates in preserving wealth. |
| Offshore is the safest option. | Domestic structures with proper asset allocation often outperform offshore due to transparency and lower compliance risks. |
| Trusts eliminate family conflicts. | Poorly designed trusts increase conflicts. Families with clear governance models report 50% fewer disputes. |
| Philanthropy is optional. | Families that integrate giving into their wealth strategy see higher engagement from heirs and better long-term asset growth. |
Why the Confusion Persists
The noise around wealth transfer for high net worth clients stems from two factors: over-reliance on anecdotes and the complexity of modern finance. Many advisors still peddle outdated strategies because they’re easier to sell than customized, multi-disciplinary approaches. Meanwhile, the rise of private wealth management platforms has democratized access to some tools, but without the context to know when—or how—to use them. Add to that the psychological barriers—fear of loss, denial of mortality, or simply not wanting to confront the topic—and it’s clear why so many families stumble. The other issue is regulatory whiplash. Tax laws change frequently—see the SECURE Act 2.0 in the U.S. or the EU’s Anti-Money Laundering Directive—and what worked five years ago may now trigger penalties. Wealth managers who don’t stay ahead of these shifts leave clients exposed. The result? A cycle where families either overcomplicate their strategies or, worse, do nothing at all.
Conclusion
Wealth transfer for high net worth clients is no longer a back-office concern—it’s a cornerstone of family legacy. The families that thrive are those that treat it as a dynamic discipline, not a static checklist. That means moving beyond the myths of offshore secrecy or trust-as-savior and instead building a framework that combines legal precision, financial flexibility, and emotional intelligence. The goal isn’t just to move money; it’s to ensure that money moves purposefully—whether to fund the next generation’s ambitions, support a cause, or simply preserve the family’s influence. The most critical step? Starting early. The families who begin planning in their 40s or 50s aren’t just preparing for the future—they’re engineering it. And in a world where wealth is increasingly concentrated in fewer hands, that engineering matters more than ever.Comprehensive FAQs
Q: At what age should high net worth individuals begin planning for wealth transfer?
Ideally, 40s to early 50s—when there’s still time to optimize tax strategies, educate heirs, and adjust structures before major life transitions (retirement, health changes). Families who start later often face rushed decisions, higher fees, or missed opportunities for tax-efficient transfers.
Q: Are trusts the only way to transfer wealth?
No. While trusts are a cornerstone, other tools include private annuities, charitable remainder trusts, and direct gifting programs. The best approach depends on the family’s goals—whether it’s asset protection, tax minimization, or simply ensuring heirs receive wealth in a controlled manner.
Q: How do estate taxes affect wealth transfer for high net worth clients?
Estate taxes can erode 30–50% of an estate’s value, depending on jurisdiction. Strategies like GRATs, IDGTs, or life insurance trusts can mitigate this, but the most effective plans combine tax planning with asset diversification to reduce taxable exposure over time.
Q: Can wealth transfer be done without professional help?
Technically yes, but the risks outweigh the benefits. A DIY approach—such as drafting a will without legal review—often leads to contested estates, unintended tax liabilities, or family disputes. Professional advisors (estate attorneys, CPAs, wealth managers) bring expertise in jurisdictional nuances, tax law, and trust structures that DIY methods can’t.
Q: How do digital assets fit into wealth transfer for high net worth clients?
Cryptocurrency, NFTs, and private company shares now represent a significant portion of many HNW portfolios. These assets require specialized custody solutions, such as multi-signature wallets or private blockchain trusts, to ensure they’re transferable and tax-compliant. Ignoring them can leave heirs with unrecoverable losses or legal complications.
Q: What’s the biggest mistake families make in wealth transfer?
Assuming the process is finished once the will is signed. The most common pitfall is lack of communication—heirs may not understand their roles, values, or responsibilities. Families that succeed treat wealth transfer as an ongoing dialogue, not a one-time event.
Q: How can philanthropy be part of wealth transfer?
Philanthropy isn’t just a tax deduction—it’s a wealth-building tool. Families use donor-advised funds (DAFs), private foundations, or impact investing to align giving with long-term financial goals. For example, a DAF can provide immediate tax benefits while allowing the family to invest the funds strategically over decades.
Q: What happens if a family doesn’t plan for wealth transfer?
The consequences range from probate delays to family feuds to asset loss. Without a plan, heirs may face unexpected tax burdens, forced asset sales, or even legal battles over inheritance. The average contested estate costs $200,000+ in legal fees—money that could have been preserved with proper planning.
