
7 Things Worth Knowing About US Currency in Circulation
The Federal Reserve’s annual reports on currency in circulation often fly under the radar, but they hold clues about economic behavior, security challenges, and even cultural shifts. Here’s what the numbers reveal—beyond the surface-level figures.1. The $2.3 Trillion Figure Is a Moving Target
The total value of US currency in circulation isn’t static. It fluctuates with economic conditions, policy changes, and global demand. At its peak in 2020, the Fed’s holdings of currency in circulation surged past $2 trillion due to stimulus checks and small-business loans. By 2023, the figure had stabilized around $2.3 trillion, but the composition of that cash has shifted dramatically. The $100 bill now accounts for nearly 80% of the dollar value in circulation—a direct result of its use in international trade and black-market transactions. What’s less obvious is how seasonal patterns affect currency in circulation. During tax season, for example, the Fed observes a spike in lower-denomination bills (like $1s and $5s) as refunds are distributed. Conversely, holiday periods see a surge in $20s and $50s as consumers carry larger cash amounts. The Fed’s Cash Product Office monitors these trends to adjust production, but the lag between demand and supply can create temporary shortages—particularly in rural areas where ATMs are scarce.2. Counterfeiters Are Outpacing Security Upgrades
The U.S. Secret Service reports that counterfeit detection remains one of its top priorities, with losses from fake US currency in circulation estimated at hundreds of millions annually. While the Fed has introduced advanced features—like microprinting, color-shifting ink, and UV-reactive fibers—the gap between innovation and criminal adaptation is narrowing. High-quality counterfeiters now use 3D printing and digital scanning to replicate security threads with near-perfect accuracy. The problem is worse outside the U.S. In countries with weak banking infrastructure, $100 bills are the most frequently counterfeited denomination. The Fed’s response? A phased rollout of new $100 notes (expected by 2026) featuring enhanced tactile markers and a portrait watermark. Yet even these upgrades may not be enough. Some experts warn that AI-generated fakes could emerge within a decade, forcing the Fed to reconsider digital watermarks or blockchain-linked serial numbers.3. The $2 Bill Is Disappearing—And That’s a Problem
The $2 bill is the most underutilized denomination in US currency in circulation, with fewer than 1.2 billion notes in active use as of 2023. The Fed stopped producing them in 2002, yet they persist—often as collectibles or in foreign markets where they’re easier to launder. The irony? The $2 bill is the most durable denomination, with a lifespan of 8.5 years before it’s retired due to wear. Why does this matter? The Fed’s denomination mix directly impacts inflation tracking. If the $2 bill vanished entirely, it would force the Bureau of Engraving and Printing to reallocate production capacity—likely to higher-denomination notes. Some economists argue that reintroducing the $2 bill could reduce counterfeit risks for smaller transactions, but the political will to revive it remains low. Meanwhile, the $500, $1,000, and $10,000 bills—once common—have been phased out entirely, leaving a gap in the currency spectrum.4. Foreign Demand Keeps Billions of Dollars Abroad
"The U.S. dollar isn’t just American money—it’s the world’s money. When you see a $100 bill in Zimbabwe or a $5 bill in Venezuela, you’re seeing the same cash that fuels global trade." — Former Federal Reserve economist, 2022An estimated $1.5 trillion of US currency in circulation exists outside U.S. borders, according to the Fed’s latest data. Countries like Zimbabwe, Vietnam, and Argentina rely on dollar bills for daily transactions, while drug cartels and sanctions-evading entities use them to obscure financial flows. The Fed doesn’t control these reserves, but it tracks their movement through diplomatic channels and private-sector reports. This global circulation has unintended consequences. When the Fed retires damaged bills, foreign nations often hoard them to extend their lifespan. In 2021, the Philippines alone returned $1.2 billion in worn U.S. currency for reissue—a practice that keeps older bills in rotation longer than intended. The Fed’s Currency Education Program has tried to promote digital alternatives, but cash remains the default in 60% of low-income countries.
5. The Fed Burns $2 Billion in Damaged Bills Every Year
Most people assume shredded or torn cash is recycled—but 95% of retired US currency in circulation is incinerated. The Fed’s Currency Replacement Program destroys bills that are too damaged to reissue, a process that generates $2 billion in annual losses. The most common causes? Frayed edges, ink smudges, and chemical damage (from exposure to cleaning products or extreme heat). The environmental impact is significant. Burning cash releases carbon dioxide equivalent to 20,000 cars’ annual emissions, though the Fed offsets this by using biodegradable shredders in some facilities. Meanwhile, the $1 bill—the most frequently damaged denomination—has a lifespan of just 5.8 years, making it the Fed’s biggest financial drain. Some lawmakers have proposed recycling programs, but logistical challenges (like separating ink from paper) have stalled progress.6. The $1 Bill’s Future Is in Question
The $1 bill is the most produced denomination in US currency in circulation, yet its relevance is waning. The Fed minted 7.8 billion $1 coins in 2022—a record—but public adoption remains sluggish. Why? Inflation has eroded its value, and merchants often round up transactions to avoid handling coins. The result? The $1 bill’s share of currency in circulation has dropped 15% since 2010. The Fed’s dilemma: Phase out the $1 bill and risk inconveniencing cash-dependent populations, or keep producing it and waste resources on a shrinking market. Some suggest replacing it with a $0.50 coin, but the transition would require ATM upgrades and public education campaigns—costing billions. For now, the $1 bill lingers, a relic of a pre-digital era clinging to relevance.7. The Next Generation of Cash Is Already Here
The Fed’s next-generation currency isn’t just about anti-counterfeit tech—it’s about interactivity. Prototypes under development include RFID chips (to track bills without compromising privacy) and holographic overlays that change when tilted. The goal? Make US currency in circulation harder to fake but easier to authenticate for businesses. But the biggest shift may be digital cash. The Fed’s FedNow system allows real-time payments, but physical cash isn’t going away. Why? Financial inclusion. In the U.S., 7 million adults remain unbanked, and cash is their only option. The Fed’s 2023 Cash Study found that 40% of Americans still prefer cash for at least some transactions, particularly in healthcare and housing. The challenge? Balancing innovation with equity—ensuring that a cashless future doesn’t leave marginalized communities behind.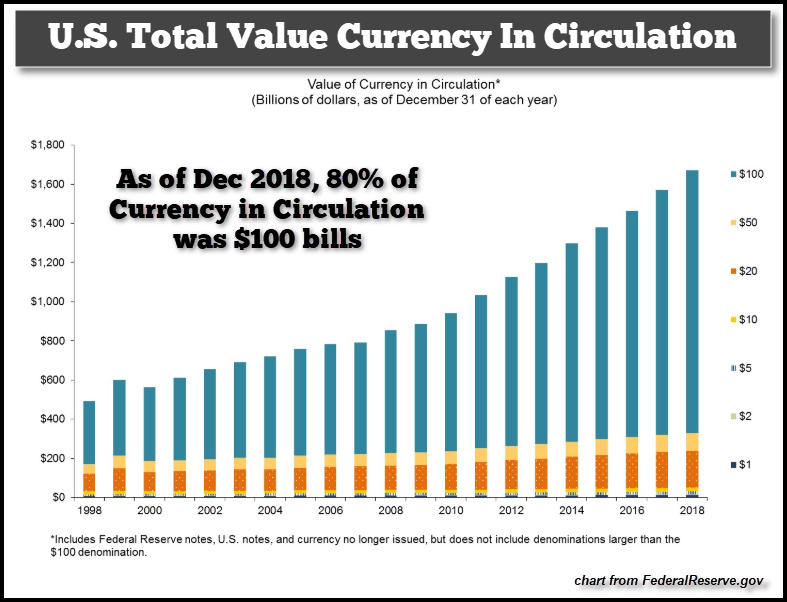
How These Facts Connect
The story of US currency in circulation is one of tension between tradition and transformation. The Fed’s struggle to modernize cash—while maintaining trust, security, and accessibility—mirrors broader economic debates. For example, the global demand for dollars isn’t just about trade; it’s a substitute for unstable currencies, revealing how cash remains a store of value in crises. Meanwhile, the counterfeit arms race shows that no matter how advanced security features become, criminals will adapt. The Fed’s denomination decisions also reflect deeper economic trends. The disappearance of the $2 bill and the dominance of $100s highlight how inflation and global trade reshape cash usage. And the environmental cost of burning bills forces a reckoning: Is cash sustainable in a climate-conscious world? These connections suggest that US currency in circulation isn’t just a financial tool—it’s a barometer of economic health, security risks, and cultural habits.| Factor | Impact on Currency in Circulation | Fed Response | Future Risk |
|---|---|---|---|
| Counterfeiting | AI-driven fakes could emerge within a decade. | New $100 bill with tactile markers (2026). | Public skepticism of digital cash. |
| Global Demand | $1.5T+ held abroad; hoarding extends bill lifespans. | Diplomatic tracking, no direct control. | Sanctions evasion via cash flows. |
| Denomination Shifts | $100 bills dominate; $2 bill vanishes. | No new denominations since 2002. | Inflation erodes smaller bills. |
| Environmental Costs | $2B in burned bills annually; CO2 emissions. | Biodegradable shredders; no recycling yet. | Public pressure for sustainable alternatives. |

Conclusion
US currency in circulation is far more than a collection of bills and coins—it’s a living system shaped by policy, crime, and global economics. The Fed’s ability to manage this system will determine whether cash remains a pillar of financial inclusion or becomes a relic of the past. As digital payments grow, the physical dollar’s role will hinge on three factors: security, accessibility, and adaptability. The challenge isn’t just technological; it’s political and cultural. For now, the trillions in US currency in circulation continue to flow—through black markets, foreign economies, and everyday transactions. The question isn’t whether cash will disappear, but how it will evolve. And that evolution will define the next chapter of America’s monetary identity.Comprehensive FAQs
Q: How does the Fed decide how much currency to print?
The Fed’s Currency Product Office uses a demand-driven model, analyzing trends like inflation, economic growth, and global demand. They also account for damaged bills (replacing ~$2 billion annually) and seasonal spikes (e.g., tax refunds). The goal is to minimize shortages while preventing excess cash from fueling inflation.
Q: Why are $100 bills the most counterfeited?
$100 bills dominate counterfeit markets because they’re high-value, portable, and widely accepted—both legally and illicitly. Their global circulation (especially in trade and sanctions evasion) makes them a prime target. The Fed’s new security features (like color-shifting ink) aim to deter this, but high-tech counterfeiters adapt quickly.
Q: Can I get my money back if I find a counterfeit bill?
Yes, but with conditions. The U.S. Secret Service investigates counterfeit cases, and victims can file a report via their website. However, most counterfeit bills are detected by businesses (which lose the money), not consumers. The Secret Service advises checking bills under UV light or using counterfeit detection pens—though these aren’t foolproof.
Q: What happens to old currency when it’s retired?
Most retired US currency in circulation is incinerated in secure facilities, but some is shredded for recycling (though paper recycling is limited due to ink separation costs). The Fed does not melt coins—they’re sent to private refiners. Damaged bills that can’t be reissued are burned in controlled environments to prevent counterfeiters from salvaging materials.
Q: Why doesn’t the Fed just issue a $200 bill?
The Fed has the authority to introduce a $200 bill, but it’s politically and logistically complex. Higher denominations increase counterfeit risks and storage costs for businesses. Additionally, the $100 bill already serves high-value transactions, and adding a $200 would require ATM and vending machine upgrades—costing billions. The last new denomination ($50 in 1999) took decades of planning.
Q: How does foreign demand for U.S. dollars affect the economy?
Foreign demand for US currency in circulation supports the dollar’s global dominance, reducing volatility. However, it also extends the lifespan of worn bills (since countries hoard them) and complicates Fed policy. For example, when the Fed retires damaged bills, foreign nations often return them for reissue, creating a secondary circulation cycle. This dynamic helps stabilize currencies in crisis but also fuels illicit financial flows.
