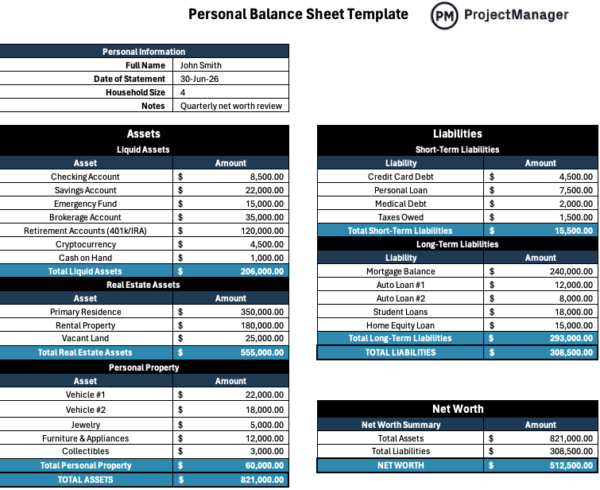
Breaking Down the Numbers
The core of a personal balance sheet net worth is simple: assets minus liabilities. But the devil is in the details. Assets include cash, investments, property, and even the value of a professional license (if transferable). Liabilities cover mortgages, credit card debt, and—less obviously—future obligations like alimony or deferred compensation. The challenge isn’t calculating these figures; it’s agreeing on their current value. A rental property’s worth might be its market appraisal, but its true contribution to net worth depends on vacancy rates and maintenance costs. Similarly, a 401(k) balance is clear, but its post-tax value after withdrawals isn’t. The second layer is timing. A personal balance sheet net worth snapshot is only useful if it’s tied to a specific moment—say, when applying for a loan or planning a career pivot. Inflation erodes the purchasing power of cash assets, while a stock market correction can slash paper wealth overnight. Even the most meticulous tracking becomes meaningless if the underlying assumptions (like expected retirement age or healthcare costs) shift. The key isn’t to chase an exact number but to understand how each component behaves under stress.The Verified Baseline
Publicly disclosed personal balance sheet net worth figures are rare, but they exist. For instance, when a celebrity or athlete files for bankruptcy or sells a stake in their brand, courts or media outlets often publish verified asset-liability breakdowns. These documents reveal hard truths: a musician’s net worth might be negative on paper due to tour debt, even if their streaming royalties suggest otherwise. Similarly, a real estate mogul’s net worth could be inflated by leveraged properties that require constant cash flow. The most reliable sources for verified personal balance sheet net worth are legal filings, tax assessments, or financial disclosures tied to high-stakes transactions. For example, when Elon Musk’s net worth dipped below $200 billion in 2022, it wasn’t just a media headline—it was calculated using Tesla stock holdings, debt levels, and reported liabilities. The numbers were real, but the volatility underscored how personal balance sheet net worth can fluctuate based on external factors beyond an individual’s control.What the Estimates Suggest
Beyond verifiable figures, estimates dominate personal balance sheet net worth calculations. A family doctor’s net worth might be estimated at figures around the £3–5 million range, but this includes assumptions about practice revenue, malpractice reserves, and the value of medical equipment. For entrepreneurs, estimates often rely on venture capital valuations or industry multiples—both of which can be arbitrary. A startup founder’s net worth might balloon overnight if their company raises a Series B, but without an exit, that equity remains illiquid. The danger of estimates isn’t their existence but their treatment as gospel. A personal financial advisor might project a client’s net worth growth at 7% annually, only for market downturns or personal expenses to derail those assumptions. The best estimates are stress-tested: What if the stock market drops 30%? What if a primary income source vanishes? The goal isn’t to predict the future but to identify the range of possible outcomes—and adjust behavior accordingly.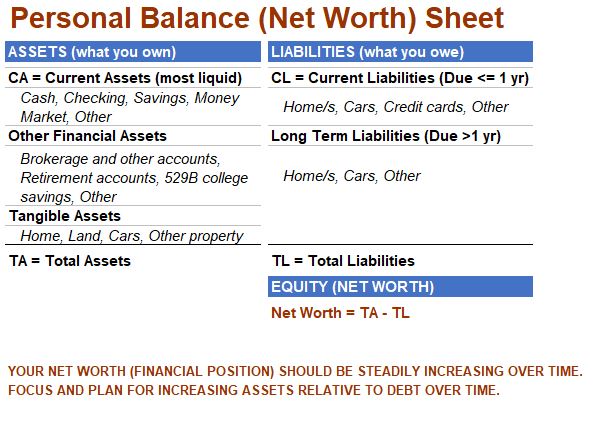
Case Study: A Closer Look
Consider the case of a mid-career software engineer in Berlin whose personal balance sheet net worth appeared solid on paper. Their assets included a €400,000 condo (mortgage-free), €150,000 in a diversified brokerage account, and €50,000 in a side business (a niche SaaS tool). Liabilities were minimal: a €20,000 student loan and €10,000 in credit card debt from a recent home renovation. On the surface, their net worth was €520,000—a figure that would qualify them for premium financial services. But the estimates told a different story. The SaaS business, while profitable, had no clear exit strategy; its value hinged on an unproven acquisition offer. The brokerage account’s growth rate assumed a 5% annual return, but historical data suggested it could stagnate in a low-interest-rate environment. Meanwhile, the engineer’s age (42) and industry (tech) introduced risks: layoffs, skill obsolescence, or a shift to remote work that reduced housing demand. Their personal balance sheet net worth wasn’t just a number—it was a ticking clock."Net worth is a snapshot, but financial health is a movie. The real question isn’t ‘How much do I have?’ but ‘How flexible is that number if my life changes?’" — Maria Rodriguez, Certified Financial Planner (CFP)
| Factor | Estimated Impact on Net Worth |
|---|---|
| SaaS Business Valuation | Could add €100,000–€300,000 if acquired; near-zero if stagnant. |
| Brokerage Account Growth | Projected 5% return may drop to 2% in a recession. |
| Tech Industry Risk | Layoffs could reduce income by 20–40% within 12 months. |
| Housing Market Shift | Condo value may decline 10–15% if remote work reduces Berlin demand. |
What This Means Going Forward
The lesson from this case study is clear: a personal balance sheet net worth is only as useful as the decisions it informs. Static numbers lead to complacency; dynamic tracking forces adaptation. For the engineer, this meant diversifying income streams, locking in higher brokerage yields, and exploring exit strategies for the SaaS business—even if it meant accepting a lower sale price. The goal wasn’t to maximize net worth at a single point but to build resilience against unknowns. This approach applies to everyone, not just high-net-worth individuals. A freelancer’s personal balance sheet net worth might show a modest figure, but if their skills are in demand and they reinvest profits wisely, that number can compound over time. The critical shift is from owning assets to optimizing them—whether that means paying off debt faster, converting illiquid assets to cash, or hedging against inflation.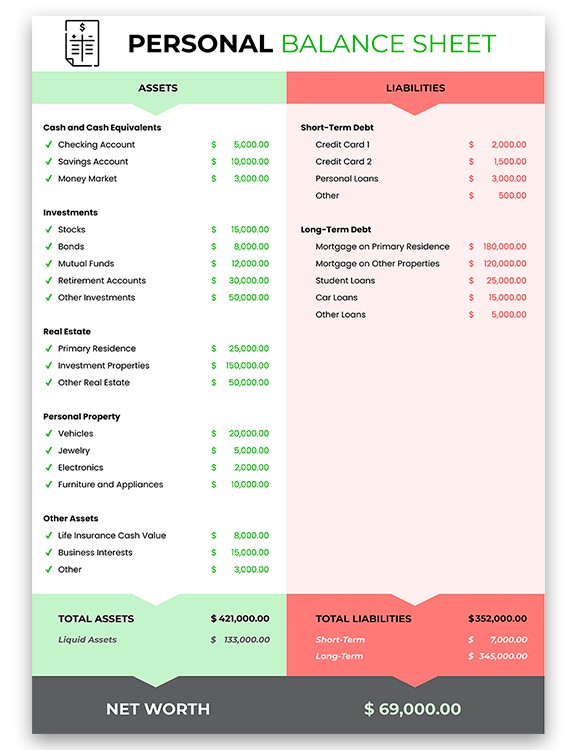
Conclusion
Personal balance sheet net worth is more than a financial metric; it’s a mirror reflecting priorities, risks, and trade-offs. The most successful individuals don’t obsess over the exact figure but use it as a tool for course correction. A sudden dip might signal the need to cut expenses or pivot careers. A spike could reveal overconcentration in a single asset class. The process isn’t about achieving a specific target but staying aware of how each decision—big or small—ripples through the balance sheet. The final irony? The more you focus on the number itself, the less control you have over it. True financial mastery comes from understanding the levers behind the figures: the tax implications of selling a property, the opportunity cost of early retirement, or the hidden fees in a "low-cost" investment. A personal balance sheet net worth isn’t just a scorecard; it’s a conversation starter about what you’re willing to sacrifice—and what you’re not.Comprehensive FAQs
Q: How often should I update my personal balance sheet net worth?
At a minimum, quarterly. Major life events—marriage, job changes, inheritance—require immediate updates. For investors, monthly tracking helps account for market volatility. The goal isn’t perfection but catching trends early.
Q: Do intangible assets (like skills or reputation) belong in a personal balance sheet net worth?
Indirectly. While you can’t assign a dollar value to a PhD or a strong personal brand, these assets influence earning potential and liquidity. Some advisors include a "human capital" estimate (e.g., projected lifetime earnings) to reflect their long-term impact.
Q: How do I handle assets with fluctuating values (e.g., cryptocurrency, art)?
Use conservative valuations. For crypto, track cost basis and market caps at purchase dates. For art, appraisals should be updated every 2–3 years. The rule: Never overstate an asset’s value in your personal balance sheet net worth—especially if it’s tied to debt.
Q: Can a negative personal balance sheet net worth be a good thing?
Yes, if it’s strategic. Students, entrepreneurs, and artists often operate at a net loss while building assets. The key is ensuring the debt or expenses are investments in future wealth (e.g., a mortgage on income-generating property).
Q: How do taxes affect my personal balance sheet net worth?
Significantly. Capital gains, property taxes, and estate duties can erode net worth faster than market changes. For example, selling a home might yield a profit, but after transaction costs and taxes, the net gain could be minimal. Always model tax impacts before major transactions.
Q: What’s the biggest mistake people make with personal balance sheet net worth?
Treating it as a static number. Many assume their net worth will grow linearly, ignoring inflation, lifestyle creep, or black swan events. The fix? Regular stress tests—simulating scenarios like job loss, divorce, or a market crash—to see how the balance sheet holds up.
