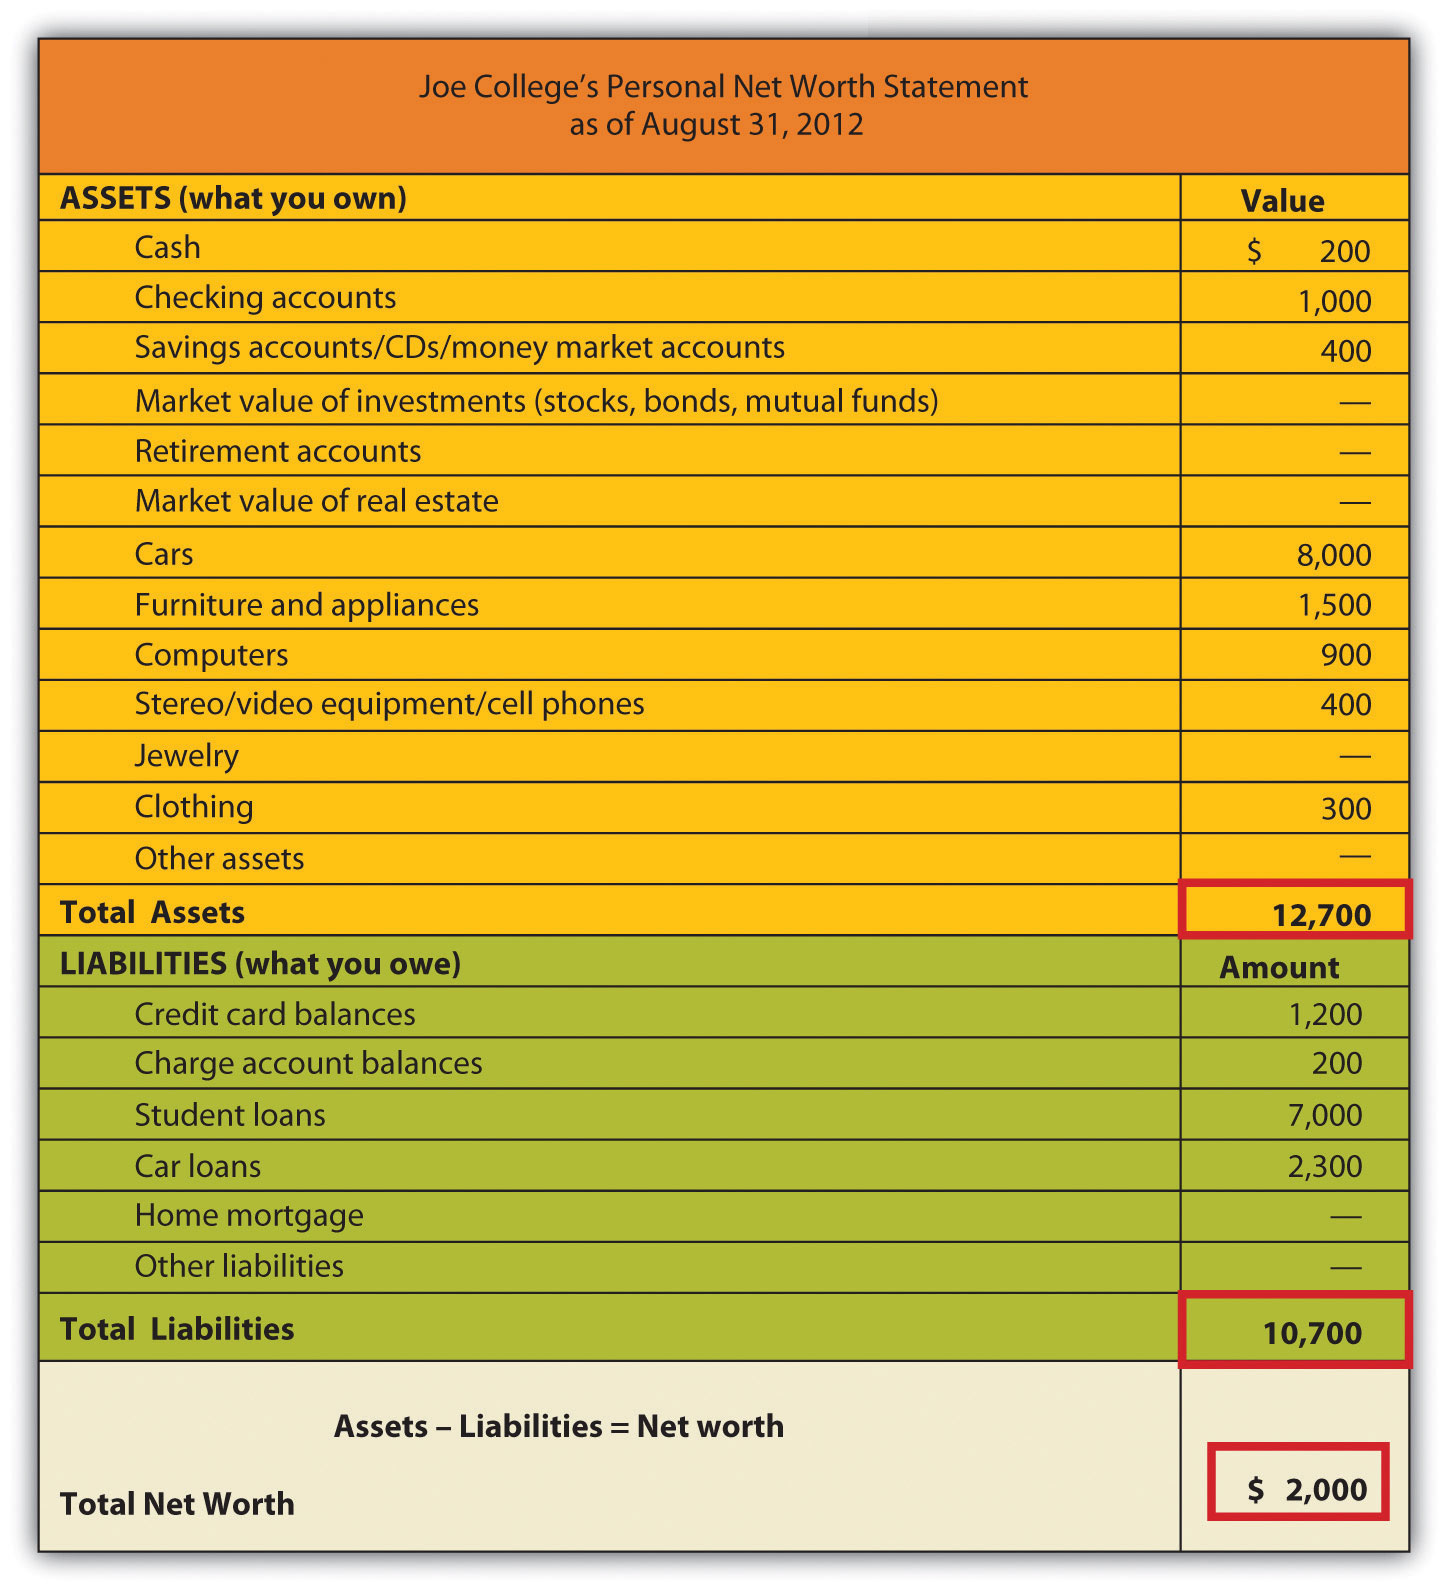
Breaking Down the Numbers
The gap between gross net worth and total liabilities net worth exposes the fragility of financial health. Assets—cash, property, investments—tell one story, while debts, future obligations, and contingent liabilities rewrite it. For individuals, this might mean a $5 million home offset by a $3 million mortgage, leaving a net exposure that’s far riskier than the headline figure suggests. Corporations face similar distortions: a balance sheet flush with revenue can still be hemorrhaging cash if pension liabilities, warranties, or pending lawsuits loom. The key variable isn’t just the size of the debt, but its total liabilities net worth ratio—the proportion of obligations relative to liquid assets.
What makes this dynamic harder to parse is the lag between recording a liability and its financial impact. A lawsuit filed today might not appear on a balance sheet for years, yet it could erode total liabilities net worth overnight if settled. Similarly, off-balance-sheet items—like unfunded retirement plans or guarantees for third parties—can turn a stable financial picture into a ticking time bomb. The result? A net worth that appears robust on paper but is structurally vulnerable to economic shocks, legal challenges, or even shifts in personal circumstances.
#### The Verified Baseline
Publicly traded companies provide the clearest window into total liabilities net worth through SEC filings, where current liabilities (due within a year) and long-term obligations must be disclosed. For example, a retail giant might report $20 billion in assets but $15 billion in liabilities, leaving a total liabilities net worth of $5 billion—yet this figure doesn’t account for pending lawsuits, lease commitments, or deferred tax liabilities. Even then, the numbers are static snapshots. A private equity firm’s net worth might spike after an acquisition, but the total liabilities net worth plummets if the deal is leveraged at 80%, exposing it to refinancing risks. For individuals, verified data is scarcer. Tax filings reveal income and deductions but rarely detail personal debt structures. A high-profile divorce or bankruptcy case, however, forces transparency: when a celebrity’s assets are frozen to satisfy creditors, the total liabilities net worth becomes a matter of public record. These moments highlight a harsh truth—wealth isn’t just about what you own, but what you’re on the hook for. ####What the Estimates Suggest
Where hard data ends, educated guesswork begins. Industry analysts often adjust reported net worth by adding back "hidden" liabilities—like unfunded healthcare costs for aging executives or the present value of future alimony payments. For instance, a tech CEO with a $200 million stake in their company might see their total liabilities net worth drop to $120 million after accounting for estimated legal exposure and deferred compensation. Private equity firms use similar adjustments, factoring in the probability of loan defaults or regulatory fines to refine their total liabilities net worth projections. The problem with estimates is their margin of error. A 2022 study by a financial think tank suggested that for ultra-high-net-worth families, total liabilities net worth could be understated by as much as 30% due to undisclosed trusts or offshore entities. The discrepancy grows when dealing with speculative assets—like cryptocurrency holdings—where debt obligations might not align with volatile market values. Even then, the exercise isn’t purely academic. Lenders, insurers, and potential buyers all rely on these adjusted figures to assess true financial health.

Case Study: A Closer Look
Consider the 2019 financial unraveling of a once-celebrated media mogul whose empire crumbled under total liabilities net worth pressures. On paper, the mogul’s net worth exceeded $1 billion, fueled by real estate holdings and minority stakes in media companies. But beneath the surface, a web of unsecured loans, personal guarantees on corporate debt, and pending lawsuits from former business partners had eroded their total liabilities net worth to roughly $300 million. The breaking point came when a key property sale fell through, triggering a margin call on a leveraged investment—and suddenly, liquidity dried up.
> "You can’t manage what you don’t measure. And if you’re not tracking your total liabilities net worth, you’re flying blind." — Financial restructuring attorney, 2020
The mogul’s downfall wasn’t a sudden wealth loss, but a slow bleed from liabilities that went unchecked. Here’s how the key factors played out:
| Factor | Estimated Impact on Total Liabilities Net Worth |
|---|---|
| Unsecured personal loans | Reduced net worth by ~$150 million (reportedly) |
| Pending legal settlements | Estimated $80–120 million in contingent liabilities |
| Off-balance-sheet guarantees | Added ~$50 million in hidden exposure |
| Leveraged real estate holdings | Trimmed liquid net worth by ~$200 million |
| Tax liabilities (unpaid) | Further reduced net position by ~$30 million |
What This Means Going Forward
The shift toward total liabilities net worth as a metric reflects a broader reckoning with financial transparency. Regulators, investors, and even courts are increasingly scrutinizing not just assets, but the full spectrum of obligations. For individuals, this means adopting a more granular approach to wealth tracking—one that separates liquid assets from illiquid ones, and distinguishes between fixed debts and variable risks. The days of relying solely on a bank statement or a brokerage summary are fading; the new standard demands a 360-degree view of financial exposure.
Institutions are catching on, too. Private equity firms now routinely stress-test total liabilities net worth under multiple scenarios, from interest rate hikes to sudden asset devaluations. Wealth managers are advising clients to preemptively structure liabilities—consolidating high-interest debt, locking in favorable terms, or even transferring obligations to trusts—to insulate net worth from volatility. The message is clear: total liabilities net worth isn’t a static number, but a dynamic equation that demands constant recalibration.

Conclusion
The myth of net worth as a single, immutable figure is giving way to a more nuanced understanding—one where total liabilities net worth takes center stage. Whether you’re analyzing a Fortune 500 balance sheet or your own household finances, the real story lies in the interplay between assets and obligations. Ignore the liabilities, and you risk misjudging risk, opportunity, or even solvency. The mogul’s collapse, the tech executive’s windfall, and the retail giant’s quiet refinancing all share a common thread: a failure to account for the full scope of total liabilities net worth.
Moving forward, the focus must shift from asset accumulation to total liabilities net worth management. That means asking harder questions: What debts are truly fixed? Which obligations could crystallize under stress? How does leverage affect liquidity? The answers will determine not just financial stability, but the ability to weather the next economic storm—or seize the next opportunity—without being blindsided by hidden exposures.
Comprehensive FAQs
#### Q: How often should I recalculate my total liabilities net worth?
At a minimum, conduct a full review annually, or whenever major life events occur—divorce, inheritance, business acquisition, or a significant change in income. For high-net-worth individuals or those with complex debt structures, quarterly check-ins are advisable, especially if interest rates or asset values are volatile.
####Q: Do all liabilities affect total liabilities net worth equally?
No. Secured debts (like mortgages) are less volatile than unsecured ones (credit cards, personal loans), and contingent liabilities (lawsuits, guarantees) can have outsized impacts if they materialize. Always prioritize liabilities by liquidity risk—those due immediately or with high penalty clauses erode net worth faster than long-term, fixed-rate obligations.
####Q: Can total liabilities net worth ever be negative?
Yes. If your liabilities exceed your assets, your total liabilities net worth becomes negative—a situation known as insolvency. This doesn’t necessarily mean bankruptcy, but it signals severe financial distress. Some high-net-worth individuals temporarily operate in this range (e.g., leveraged buyouts), but it’s a high-risk strategy requiring precise timing and exit plans.
####Q: How do off-balance-sheet liabilities impact total liabilities net worth?
Off-balance-sheet items—like operating leases, unfunded pension obligations, or guarantees—aren’t always reflected in standard net worth calculations. However, they can significantly reduce total liabilities net worth if they’re realized. For example, a company’s lease commitments might not appear as debt, but they still represent future cash outflows that could strain liquidity.
####Q: Is total liabilities net worth the same as solvency?
Not exactly. Total liabilities net worth is a snapshot of your financial position at a given time, while solvency refers to your ability to meet obligations as they come due. You could have a positive total liabilities net worth but still be insolvent if your liabilities are concentrated in the short term (e.g., a balloon mortgage payment due next month). Solvency is a function of cash flow, not just net worth.
####Q: How do taxes affect total liabilities net worth?
Taxes are a dual-edged sword. Unpaid taxes are a direct liability that reduces net worth, while tax-efficient structures (like trusts or deferred compensation) can shield assets from immediate obligations. For example, a capital gains tax bill due next year might not appear on a balance sheet today, but it’s a future liability that will erode total liabilities net worth when paid.
####Q: Can I improve my total liabilities net worth without increasing income?
Absolutely. Strategies include consolidating high-interest debt, refinancing mortgages to lower payments, settling contingent liabilities early, or liquidating nonessential assets to pay down obligations. Even small adjustments—like converting variable-rate loans to fixed—can stabilize total liabilities net worth over time.
####Q: Why do some people report net worth without liabilities?
Often, it’s a matter of presentation. Public figures, influencers, or even financial advisors may omit liabilities to simplify their narrative or avoid scrutiny. However, this practice obscures true financial health. A more accurate approach is to disclose total liabilities net worth alongside gross assets, providing a complete picture for stakeholders, lenders, or potential partners.
