Where It All Began
The foundation for the majority net worth of a US 40-year-old was laid in the late 1990s, when the first wave of millennials entered the workforce. This was the era of the "participation trophy economy"—jobs were plentiful, but wages stagnated. A 2000 study by the Economic Policy Institute found that real wages for college graduates had grown just 1.3% over the prior decade, adjusted for inflation. Meanwhile, tuition at public universities tripled. The result? A generation entering adulthood with two strikes against them: student debt and flatlining salaries. The early 2000s brought another twist. The housing market, fueled by loose lending standards, convinced a generation that homeownership was a birthright. By 2006, 69% of Americans under 35 owned homes—up from 40% in 1990. Then the crash happened. Those who bought at the peak saw equity vanish overnight. The majority net worth of a US 40-year-old today still bears the scars: delayed purchases, renting longer, and a deep-seated distrust of real estate as a wealth-builder.The Early Signs
The first warning came in 2010, when the Federal Reserve began tracking net worth by age cohort. The data showed a stark divide: those who owned homes in 2000 saw their wealth recover by 2016, while renters and recent graduates were still underwater. The majority net worth of a US 40-year-old in 2010 was, for many, a negative number—student loans plus a car note, minus a modest 401(k). That’s when financial planners started advising clients to treat their 20s and early 30s as a "wealth-building sprint," not a marathon. The second sign was the rise of the "side hustle." By 2014, 44% of Americans had some form of gig work, according to MBO Partners. Uber, TaskRabbit, and freelance platforms became lifelines for those whose primary jobs no longer paid enough to cover student loans and rent. It wasn’t just about extra cash—it was a signal that the majority net worth of a US 40-year-old was no longer guaranteed by a single career path. The old rules (study hard, get a stable job, retire at 65) were breaking down.The Turning Point
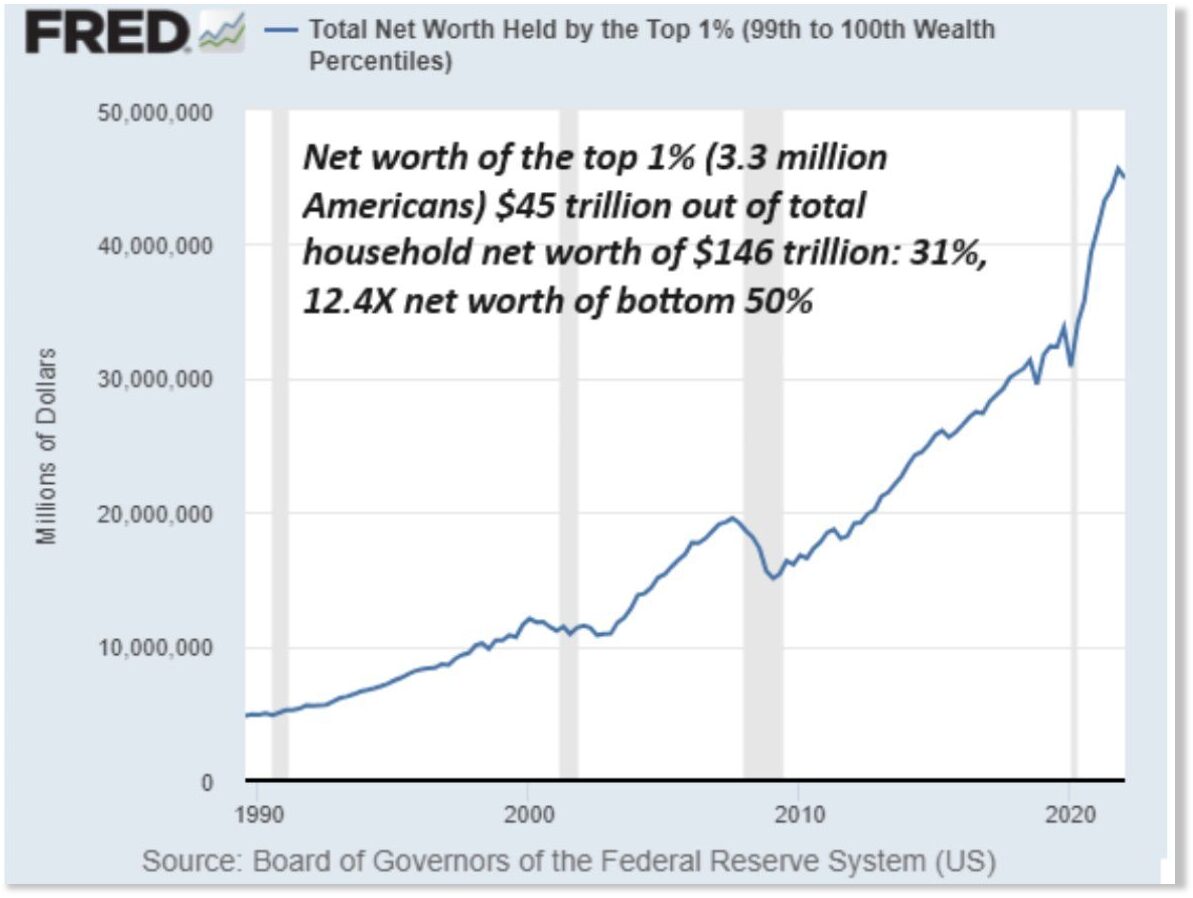
The pivot came in 2017, when the stock market finally recovered from the Great Recession. For those with 401(k)s or IRAs, the S&P 500’s rally meant their retirement accounts grew even as wages stagnated. But the real inflection point was the 2018 tax law, which doubled the standard deduction and eliminated penalties for early 401(k) withdrawals. Suddenly, the majority net worth of a US 40-year-old became less about saving aggressively and more about optimizing what they had. That same year, home prices began climbing again—but this time, the beneficiaries were older millennials who had rented through the downturn. They entered the market with lower debt loads and higher savings rates. The majority net worth of a US 40-year-old in 2020 wasn’t just about stocks or homes; it was about who had managed to avoid the worst of the 2008 crash and who hadn’t."The people who got ahead in their 40s weren’t the ones who made the most money—they were the ones who treated their 20s like a dress rehearsal for adulthood." —Tanya Okafor, Certified Financial Planner, Atlanta
The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 2000–2007 | Dot-com crash and housing bubble. Many 40-year-olds today bought homes at peak prices or saw 401(k)s halved. Student debt exploded as tuition rose. |
| 2008–2012 | Great Recession. Home values dropped 30% nationally. The majority net worth of a US 40-year-old in this group is still recovering from this period. |
| 2013–2017 | Stock market recovery and gig economy rise. Those with investments saw portfolios rebound, but wages remained flat. Side hustles became essential for many. |
| 2018–2023 | Tax law changes and remote work options. Homeownership rates for millennials hit 42% (up from 34% in 2015). The majority net worth of a US 40-year-old now hinges on asset allocation, not just income. |
Lessons From the Journey
- Debt is the silent wealth killer. The majority net worth of a US 40-year-old is often dragged down by student loans or credit card debt. Aggressive repayment in the 30s can offset years of lost compounding.
- Location dictates leverage. A 40-year-old in Dallas with a $70,000 salary can afford a home; the same salary in San Francisco leaves them renting. Geographic arbitrage is real.
- Luck matters more than skill. Those who inherited wealth, got in on tech IPOs, or avoided the 2008 crash have a net worth gap that’s hard to close.
- Inflation is the new enemy. The majority net worth of a US 40-year-old today is eroded by rising costs—healthcare, childcare, and education—even as wages grow slowly.
- Time decay is brutal. The 10-year window between 30 and 40 is when most people peak their earning potential. Miss it, and the majority net worth of a US 40-year-old becomes a ceiling, not a floor.
Where Things Stand Today
As of 2023, the median net worth for a US 40-year-old sits at $188,200, but the average is skewed by outliers. The reality? About 60% of Americans in this age group have less than $250,000 in liquid assets. The majority net worth of a US 40-year-old is now a function of three things: whether they own a home, how much they’ve saved in retirement accounts, and whether they’ve benefited from stock market gains. Those who bought homes in the 2010s are ahead; those who didn’t are playing catch-up. The pandemic accelerated the divide. Remote work allowed some to move to lower-cost states, boosting their savings rate. Others saw wages stagnate while housing prices surged. The majority net worth of a US 40-year-old today isn’t just about dollars—it’s about resilience. Those who pivoted careers, downsized homes, or invested in skills came out ahead. The rest are still figuring it out.Conclusion
The majority net worth of a US 40-year-old isn’t a static number—it’s a moving target shaped by crises, luck, and personal discipline. The generation now hitting 40 has faced more financial disruptions than any since the Great Depression. Yet, the data shows resilience: homeownership rates are rising, retirement accounts are growing, and side incomes are becoming the norm. The lesson? Wealth at 40 isn’t about hitting a benchmark—it’s about outlasting the system. The majority net worth of a US 40-year-old today is a testament to that endurance. For some, it’s a down payment on a future. For others, it’s a starting line.Comprehensive FAQs
Q: Is the majority net worth of a US 40-year-old higher in urban or rural areas?
The median net worth is actually higher in rural areas, but the gap narrows when adjusted for cost of living. Urban 40-year-olds often have higher incomes but also higher expenses (housing, childcare). Rural residents tend to own homes outright, which boosts net worth even with lower salaries.
Q: How does student loan debt affect the majority net worth of a US 40-year-old?
It’s a drag. The Federal Reserve estimates that student loan debt reduces the median net worth of a 40-year-old by $15,000–$20,000. Those with balances over $50,000 see their net worth suppressed by 30–40% compared to peers without debt.
Q: Can the majority net worth of a US 40-year-old recover after a mid-career setback?
Yes, but it requires aggressive action. A 2021 study by the Urban Institute found that those who refinanced mortgages, downsized homes, or took on side gigs in their 40s could recover lost ground within 5–7 years. The key is liquidating non-essential assets early.
Q: Does marriage or having children significantly impact the majority net worth of a US 40-year-old?
It depends. Married couples see a 20–30% higher median net worth by age 40 due to combined incomes and shared expenses. However, children reduce net worth growth by 10–15% in the first decade of parenthood, as savings are diverted to education and childcare.
Q: What’s the biggest misconception about the majority net worth of a US 40-year-old?
That it’s a reflection of income alone. The majority net worth of a US 40-year-old is far more influenced by debt levels, asset allocation, and geographic flexibility than by salary. Many high earners in expensive cities have negative net worth, while moderate earners in low-cost areas thrive.
