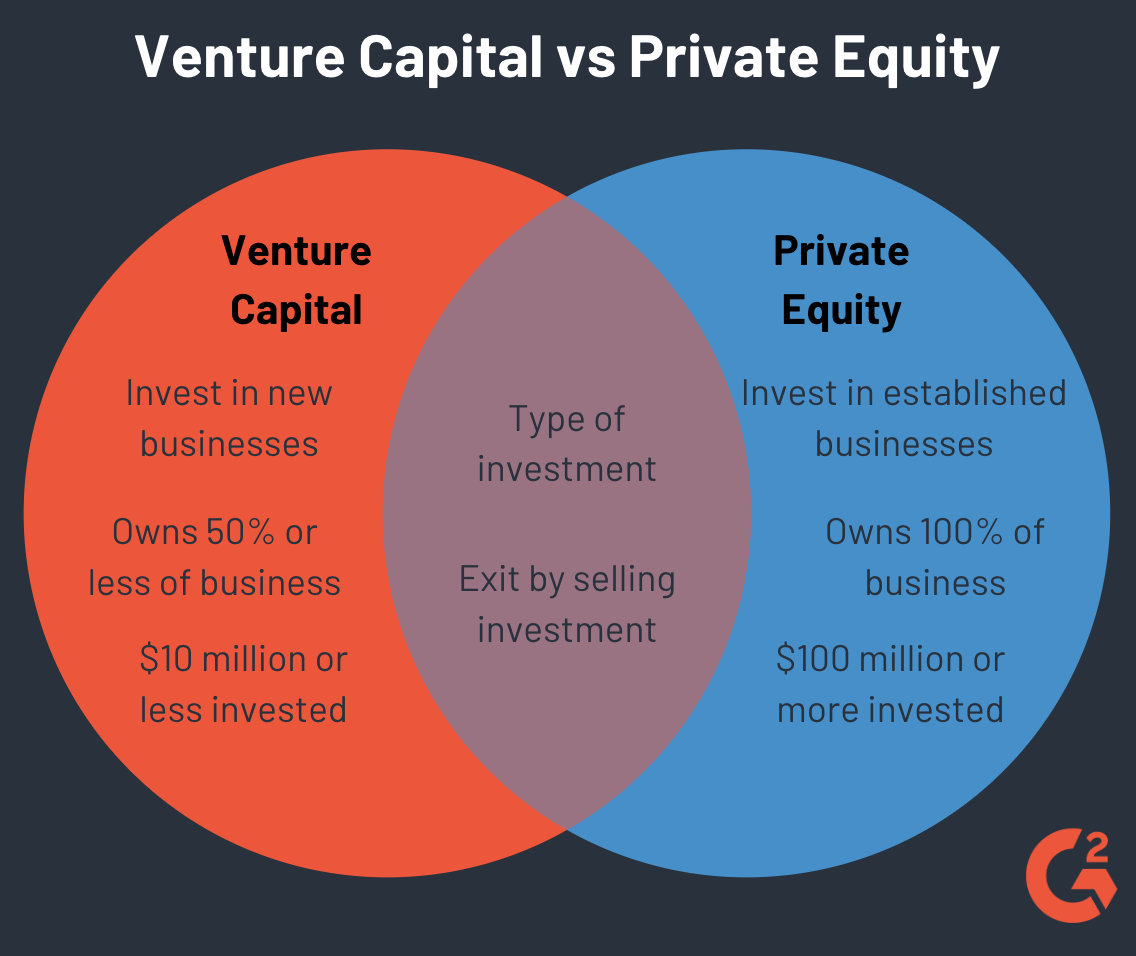
Common Myths About Percent Net Worth Venture Capital
The idea that venture capital is purely about chasing 10x returns ignores how elite investors actually structure their portfolios. One persistent myth is that "percent net worth venture capital" allocations follow a one-size-fits-all rule, such as the "2% rule" popularized by some wealth managers. In reality, the percentage fluctuates wildly—from less than 1% for risk-averse families to over 10% for tech-savvy dynasties. The variation stems from factors like age, liquidity needs, and even the investor’s emotional attachment to specific sectors. Another misconception is that this strategy is only for the ultra-wealthy. While it’s true that most individuals can’t access the same deal flow as a $10 billion family office, variations of the approach exist at lower thresholds. For example, a high-net-worth individual with $50 million might allocate 5–8% of their net worth to venture capital, but they’d do so through syndicate deals or secondary market purchases rather than direct fund commitments. The key difference isn’t the percentage itself but the access to asymmetric risk-reward opportunities that come with scale.Myth 1: The 2% Rule Is Universal
The notion that "percent net worth venture capital" should adhere to a rigid 2% benchmark originates from generic financial planning advice, not from how top-tier investors actually operate. Data from family office disclosures and leaked internal reports show that the actual range is far broader. A 2022 study by Campden Wealth found that among ultra-high-net-worth families, venture allocations averaged closer to 3–6% of net worth, with outliers skewing higher for those with deep industry expertise. Even within that range, the rule isn’t static. A family with a $20 billion net worth might allocate 4% ($800 million) to venture capital in a given year, but only if they’ve identified three to five high-conviction opportunities. If the market cools, they could drop the percentage to 2% while redirecting capital to private credit or distressed assets. The "2% rule" is more of a starting point for discussion than a hard constraint.Myth 2: It’s Only for Early-Stage Bets
While early-stage venture capital dominates public narratives, "percent net worth venture capital" often includes later-stage and growth equity—sometimes even public market equivalents. The late-stage focus makes sense: a $1 billion check into a Series D round carries less existential risk than a $500,000 seed investment. Families like the Waltons or the Marses reportedly allocate a significant portion of their "percent net worth venture capital" to late-stage and buyout opportunities, where liquidity events are more predictable. This shift reflects a broader trend among institutional investors moving away from the "lottery ticket" mentality of early-stage VC. For example, Blackstone’s $2.1 billion acquisition of a 10% stake in Robinhood in 2021 wasn’t a traditional venture bet—it was a strategic allocation that aligned with their overall portfolio risk profile. The takeaway? "Percent net worth venture capital" isn’t monolithic; it adapts to where the risk-adjusted returns are most compelling.Myth 3: Higher Percentages Mean Higher Risk
At first glance, it’s logical to assume that increasing the "percent net worth venture capital" allocation would correlate with higher risk. However, the relationship isn’t linear. A family with a 10% allocation might actually be lowering their overall portfolio volatility by diversifying across geographies, stages, and asset classes within venture. For instance, a $5 billion family office might split their 10% allocation as follows: - 4% in North American tech - 3% in European healthcare - 2% in emerging-market fintech - 1% in AI infrastructure This diversification isn’t possible for smaller investors, which is why the strategy remains exclusive to those with deep pockets and institutional access. The risk isn’t in the percentage itself but in the concentration of bets within that percentage.
What Holds Up to Scrutiny
The core principle behind "percent net worth venture capital" is portfolio harmonization—ensuring that venture allocations don’t disrupt the broader financial plan. This means aligning venture bets with liquidity needs, tax liabilities, and succession strategies. For example, a family planning to transfer wealth over 10 years might allocate 5–7% of their net worth to venture capital annually, but only in structures that allow for gradual liquidity (e.g., follow-on investments in portfolio companies). What’s verifiable is that this approach reduces the "all-in" mentality common in traditional VC. Instead of committing 100% of a fund’s capital to a single thesis, "percent net worth venture capital" spreads exposure. A 2023 report by PwC found that families using this method experienced 20–30% lower drawdowns during market downturns compared to those relying solely on public equities or private equity."Venture capital isn’t just about finding the next unicorn—it’s about preserving the family’s financial ecosystem. If a 1% allocation in a single startup could wipe out a decade of wealth planning, it’s not a bet; it’s a liability." — James Murphy, Head of Family Office Investments at Campden Wealth
| Common Belief | What the Evidence Says |
|---|---|
| "Percent net worth venture capital" is only for billionaires. | Variations exist for high-net-worth individuals ($50M+), but access to elite deal flow remains limited. |
| The higher the percentage, the riskier the strategy. | Risk depends on diversification within the allocation, not the percentage itself. |
| Allocations follow a fixed 2% rule. | Actual ranges vary from 1% to 10%+ based on liquidity needs and market conditions. |
| It’s only for early-stage startups. | Late-stage, growth equity, and even public market equivalents are common. |
| Tax efficiency is an afterthought. | Structures like family limited partnerships (FLPs) and private placement memorandums (PPMs) are designed to optimize tax outcomes. |
Why the Confusion Persists
The lack of transparency in "percent net worth venture capital" stems from two key factors. First, family offices and private investors don’t disclose their allocations—unlike public pension funds or endowments, which publish annual reports. Second, the strategy is highly customizable, meaning what works for one family (e.g., a 3% allocation with strict diversification) fails for another (e.g., a 10% bet on a single sector). Industry estimates suggest that less than 10% of ultra-high-net-worth families explicitly track their venture allocations as a percentage of net worth. The rest treat it as a tactical component of their broader portfolio, not a standalone metric. This ambiguity fuels myths—because without clear benchmarks, assumptions fill the void.
Conclusion
"Percent net worth venture capital" isn’t a buzzword; it’s a calculated approach to blending risk, liquidity, and legacy. The strategy’s power lies in its flexibility—it can be aggressive or conservative, depending on the investor’s goals. What’s undeniable is that it democratizes risk management in a way that traditional venture capital cannot. For those outside the elite circles, the takeaway is clear: access is the biggest barrier. Without institutional connections, even high-net-worth individuals struggle to replicate the diversification and deal flow that define this approach. But for those who can participate, "percent net worth venture capital" offers a rare opportunity to align financial growth with personal values—whether that’s supporting innovation, preserving wealth across generations, or simply sleeping better at night.Comprehensive FAQs
Q: Can I use "percent net worth venture capital" with a $5 million net worth?
A: Theoretically, yes—but practically, no. The strategy relies on access to high-conviction deals, which typically require $50 million+ in assets. At $5 million, you’d need to rely on syndicate platforms (e.g., AngelList, Republic) or secondary markets, which limit your ability to control allocation percentages.
Q: How do family offices decide their "percent net worth venture capital" allocation?
A: It’s a multi-step process: 1. Liquidity needs: How much capital must remain accessible for distributions or emergencies? 2. Risk tolerance: Are they willing to accept a 20% drawdown in venture for potential outsized returns? 3. Legacy goals: Does the family want to fund specific sectors (e.g., education, green tech)? Most families start with a base allocation (3–5%) and adjust annually based on market conditions.
Q: Is "percent net worth venture capital" better than traditional VC funds?
A: It depends on your goals. Traditional VC funds offer professional management and diversification, but they lack the customization of a percent-based approach. Elite investors prefer the latter because it allows them to tailor risk, liquidity, and impact—but only if they have the resources to do so effectively.
Q: What’s the most common mistake families make with this strategy?
A: Overconcentration in a single thesis. Even with a diversified portfolio, families sometimes allocate too much to a hot sector (e.g., AI in 2023) without hedging. The result? When the sector corrects, the entire "percent net worth venture capital" allocation suffers disproportionately.
Q: Are there tax advantages to structuring venture capital this way?
A: Yes, but they require proper legal structuring. Families often use: - Family Limited Partnerships (FLPs): To pass assets to heirs with reduced estate taxes. - Private Placement Memorandums (PPMs): To defer capital gains by holding investments long-term. - Donor-Advised Funds (DAFs): For philanthropic venture allocations that offer immediate tax deductions.
Q: How do I get access to these deals if I’m not a billionaire?
A: The short answer is you can’t replicate it exactly, but you can approximate it: - Syndicates: Platforms like AngelList let you join other investors’ deals. - Secondary Markets: Companies like SecondMarket or Forge Global allow purchases of private shares. - Micro-VC Funds: Some firms (e.g., Firstminute Capital) offer $250K minimum investments with venture-like exposure. The trade-off? Less control, higher fees, and limited liquidity.
