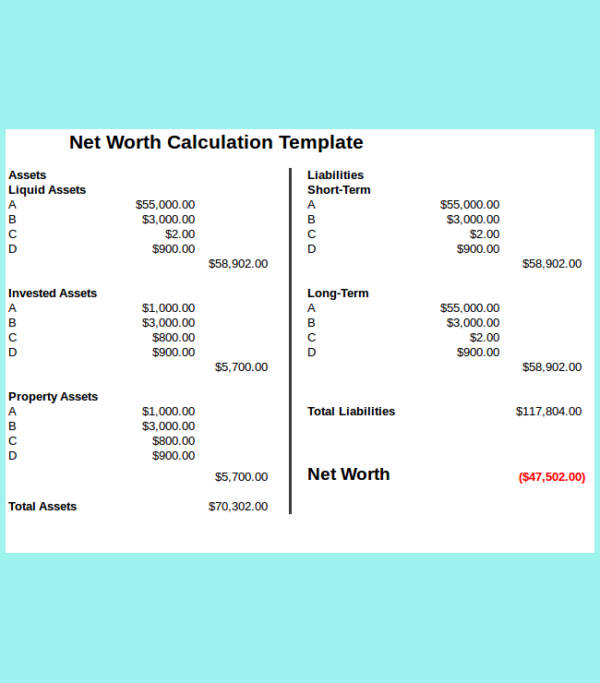
The Complete Overview of Networth Calculation
Networth calculation is the financial equivalent of a stress test—it reveals what you own, what you owe, and the gap between the two. But unlike a credit score, which is a black-box algorithm, networth is supposed to be transparent. In theory, you add up everything of value (cash, investments, property) and subtract everything owed (mortgages, loans, credit cards). The result is a single number that supposedly defines your financial standing. The catch? The components of that calculation are rarely fixed. A vintage car collection might appreciate in value, but only if you can sell it quickly. A pension fund’s future payouts are an estimate, not a guarantee. Even cash isn’t as liquid as it seems—some accounts have withdrawal limits, others face penalties. The real complexity emerges when you consider what shouldn’t be included. A stay-at-home parent’s work isn’t quantified in most networth calculations, yet their contribution to household stability is incalculable. A freelancer’s reputation or a doctor’s patient base might be their most valuable asset, but these don’t appear on a balance sheet. The system favors tangible, easily tradable assets while dismissing intangibles that drive real-world value. This bias isn’t accidental; it’s a reflection of how financial institutions have historically valued security over potential. A bank will lend against a house because it can foreclose, but it won’t lend against a social media following—even if that following generates six figures annually.Historical Background and Evolution
The concept of networth as a financial metric traces back to medieval merchant ledgers, where traders recorded assets and debts to assess creditworthiness. By the 19th century, banks formalized the practice, treating networth as a proxy for risk. The modern framework—assets minus liabilities—was solidified during the Industrial Revolution, when factories and railroads required massive capital injections. Lenders needed a way to quantify collateral, and networth became that tool. What started as a commercial necessity evolved into a personal finance staple by the 20th century, thanks to the rise of consumer credit and the middle-class dream of homeownership. The digital age transformed networth calculation into both a science and an art. The advent of online banking in the 1990s made it easier to track balances, while robo-advisors and fintech apps automated the process. Today, platforms like Wealthfront or Mint can generate a networth snapshot in seconds—but these tools still rely on the same flawed assumptions as their 19th-century predecessors. The difference? Now, a single misclassified asset (like cryptocurrency held in a cold wallet) can skew the entire calculation. Meanwhile, the gig economy has introduced new variables: the value of a Uber driver’s car isn’t just its depreciated market price, but its role in generating income. Networth calculation hasn’t kept pace with these shifts, leaving gaps that benefit those who control the data—and penalize those who don’t.Core Mechanisms: How It Works
At its core, networth calculation follows a deceptively simple formula: Total Assets – Total Liabilities = Networth But the devil is in the definitions. Assets can include cash, investments, real estate, vehicles, and even collectibles—though appraisals for the latter are often subjective. Liabilities encompass mortgages, student loans, credit card debt, and sometimes even future obligations like alimony or child support. The challenge isn’t the arithmetic; it’s the classification. A business owner might argue that their company’s goodwill is an asset, while a creditor might treat it as a liability if the business is struggling. The same logic applies to personal guarantees on loans or the unpaid taxes of a freelancer who hasn’t set aside enough for quarterly estimates. The process becomes even murkier when accounting for time horizons. A retiree’s networth might look robust on paper, but if their portfolio is heavily weighted in bonds yielding 2%, their purchasing power could erode faster than inflation. Conversely, a young professional with a high-paying job and no debt might have a modest networth now—but their earning potential could outpace inflation over decades. The static snapshot of networth calculation ignores these temporal dynamics, treating wealth as a fixed quantity rather than a fluid asset. This is why financial advisors often recommend tracking networth trends over time, rather than fixating on a single number.Key Benefits and Crucial Impact
Networth calculation serves as a financial report card, but its value extends beyond personal tracking. For lenders, it’s a quick way to assess whether a borrower can handle additional debt. Governments use networth thresholds to determine eligibility for public assistance, student loan forgiveness, or even visa applications. Politicians weaponize the metric to justify policy—arguing that high networth individuals should pay more in taxes, or that low networth families need stimulus checks. The problem? The numbers don’t account for structural inequalities. A nurse with $50,000 in student loans might have a lower networth than a software engineer with the same debt, yet their earning trajectories could converge—or diverge—based on factors like geographic location, discrimination, or industry demand. The psychological impact of networth calculation is equally significant. For some, hitting a networth milestone (e.g., $1 million) triggers a sense of achievement, while for others, a negative networth can feel like failure—even if it’s temporary. This is why financial planners often emphasize networth growth rates over absolute figures. A family might have a networth of $200,000 but be on track to double it in five years; another might have $500,000 but see it stagnate due to market conditions. The narrative around networth calculation shapes behavior, from aggressive investing to debt avoidance, even when the underlying data is incomplete."Networth isn’t a destination; it’s a story you’re telling yourself—and others—about your financial future. The numbers are just the first chapter." — Morgan Housel, behavioral finance author
Major Advantages
- Clarity in financial standing. A networth statement forces you to confront what you own and owe, revealing blind spots like hidden fees or underperforming assets.
- Benchmarking progress. Tracking networth over time shows whether your savings, investments, or debt reduction strategies are working—or need adjustment.
- Lender and investor confidence. A strong networth improves loan approval odds and can lower interest rates, as it signals lower risk.
- Tax and legal planning. Networth thresholds determine eligibility for deductions, trusts, or estate planning strategies that minimize tax burdens.
- Risk assessment. A high networth relative to income might indicate over-leveraging, while a low networth with high cash flow could signal untapped opportunities.

Comparative Analysis
| Traditional Networth Calculation | Modern/Alternative Approaches |
|---|---|
| Focuses on liquid and tangible assets (cash, real estate, stocks). | Includes intangibles like human capital (skills, reputation), social capital (networks), and digital assets (NFTs, crypto). |
| Static snapshot—ignores future income potential. | Dynamic tracking—considers earning trajectories, career flexibility, and inflation-adjusted growth. |
| Debt is treated as uniformly negative. | Distinguishes between "good debt" (mortgages, student loans with high ROI) and "bad debt" (credit cards, consumer loans). |
| Primarily used for lending and eligibility determinations. | Employed for behavioral insights—understanding spending habits, risk tolerance, and long-term goals. |
Future Trends and Innovations
The next evolution of networth calculation will likely blend traditional metrics with behavioral economics and AI-driven predictions. Fintech firms are already experimenting with predictive networth—estimating future financial trajectories based on spending patterns, career data, and even social media activity. For example, a platform might analyze your LinkedIn profile, online courses, and side hustle income to project your networth in five years, not just report it today. This shift could democratize financial planning, giving gig workers and freelancers tools previously reserved for institutional investors. Another frontier is decentralized networth tracking, where individuals verify assets via blockchain rather than relying on third-party institutions. Imagine a system where your crypto holdings, freelance invoices, and even loyalty points are automatically tallied in real time, creating a self-sovereign networth ledger. The challenge? Standardizing how to value non-fungible assets like domain names or digital art. As central banks explore central bank digital currencies (CBDCs), networth calculation could become more granular—tracking not just balances but transaction histories and spending velocities. The risk? Greater surveillance by governments and corporations, turning a personal metric into a tool for social scoring.
Conclusion
Networth calculation remains one of the most powerful yet misunderstood tools in personal finance. Its strength lies in its simplicity: a single number that supposedly summarizes your financial life. Its weakness? The assumptions it forces you to make—about what’s valuable, what’s risky, and what’s worth tracking. The best networth calculations aren’t just about the math; they’re about the questions they prompt. Why is your home equity growing slower than expected? Could your side hustle be worth more than your 401(k) contributions? The answers lie in how you define—and refine—the process. The future of networth calculation won’t eliminate its ambiguities, but it may make them more transparent. As AI and decentralized finance reshape how we measure value, the conversation around networth will shift from what you own to what you can create. For now, the discipline of calculating networth serves as both a mirror and a compass—reflecting where you are while pointing toward where you might go. The key isn’t to chase a specific number, but to use the process as a lens for smarter financial decisions.Comprehensive FAQs
Q: Should I include my retirement accounts in my networth calculation?
A: Yes, but with caveats. Defined-contribution accounts (like 401(k)s or IRAs) should be included at their current value, as they’re part of your assets. However, if you’ve taken loans against them, that amount becomes a liability. Pension funds are trickier—include the present value of projected payouts, but note that future benefits aren’t guaranteed. Some advisors recommend excluding retirement accounts if you’re still contributing, as the funds aren’t fully accessible without penalties.
Q: How often should I update my networth calculation?
A: At a minimum, quarterly—especially if your income, debt, or investments fluctuate frequently. High-net-worth individuals or those with volatile assets (like crypto or private equity) may need monthly updates. The goal isn’t to obsess over daily market swings, but to catch major shifts early. Automating the process with tools like YNAB or Personal Capital can reduce the effort while keeping your numbers current.
Q: Does my networth include the value of my skills or professional network?
A: Traditional networth calculations ignore these, but some modern approaches treat them as human capital. For example, a doctor’s ability to earn $300,000/year could be valued at the present discounted value of future income. Similarly, a salesperson’s client list might be worth thousands in commissions. While these aren’t liquid assets, they’re critical to long-term wealth. If you’re self-employed or in a high-earning field, accounting for them—even informally—can provide a more accurate picture of your financial potential.
Q: Why does my networth sometimes decrease even when I’m saving money?
A: This happens when your liabilities (like student loans or credit card debt) are larger than your new savings, or when asset values drop. For example, if you save $10,000 but your stock portfolio loses $15,000 due to a market downturn, your networth falls. It can also occur if you take on new debt (e.g., a home renovation loan) that outweighs your cash inflows. The fix? Focus on networth growth rate—if your savings and investments outpace debt and market losses over time, you’re still building wealth, even if the number dips occasionally.
Q: Can a negative networth be a good thing?
A: In some cases, yes—if the debt is strategic. Student loans for a high-earning field (e.g., medicine, engineering) or a mortgage on appreciating real estate can be long-term investments. A negative networth might also reflect a phase of life (early career, family expansion) where debt is a tool for future growth. The red flag? Negative networth driven by consumer debt (credit cards, car loans) or stagnant income. Always ask: Is this debt accelerating my goals, or is it a drag? If it’s the latter, prioritize paying it down.
Q: How do I handle assets that are hard to value, like a family business or art collection?
A: Start with conservative estimates. For a family business, use a multiple of earnings (e.g., 3–5x annual profit) or get a professional appraisal. Art and collectibles should be valued at replacement cost (what it would cost to buy a similar item today) or recent sale prices—never peak market values. If the asset is illiquid (hard to sell quickly), consider assigning it a lower weight in your networth calculation. The key is consistency: if you’re tracking progress, use the same methodology each time.
Q: Does my spouse’s or partner’s networth affect mine?
A: It depends on how you define "yours." If you’re legally married or in a community-property state, your combined assets and debts are typically considered together for financial planning. For unmarried couples, networths are separate unless you’ve co-signed loans or jointly own assets. Some advisors recommend tracking household networth (combined figures) for shared goals, while keeping individual calculations for personal accountability. Clarify ownership and liability rules early to avoid surprises.
