
7 Things Worth Knowing About Net Worth Middle Class
The net worth middle class operates by its own rules—rules that aren’t taught in personal finance seminars or highlighted in political debates. These are the facts that explain why the term middle-class wealth has become a euphemism for financial precarity for millions. The numbers don’t lie, but they’re often misread.1. The Median Net Worth Middle Class Is a Moving Target
Federal Reserve data shows the median net worth for U.S. households hovers around $138,000—but that figure masks vast regional and demographic divides. In states like Massachusetts or Maryland, where home values and living costs skew high, the net worth middle class might require $300,000 or more to feel secure. Conversely, in Mississippi or West Virginia, the same net worth could mean generational stability. The problem? The median isn’t the mean, and the mean isn’t reality for most. Nearly 40% of U.S. households have a net worth below $50,000, meaning the "middle" in net worth middle class is less a statistical center and more a fragile plateau. What’s often overlooked is how this median shifts with age. A 25-year-old with a net worth of $20,000 might be on track to join the net worth middle class by 40—but only if they avoid major debt, benefit from employer matches on retirement accounts, and don’t face a housing market crash. The trajectory isn’t linear; it’s a series of gambles.2. Homeownership Is the Great Equalizer (and Divider)
Owning a home is the single largest driver of net worth for the middle class. According to the Federal Reserve, homeowners hold nearly 70% of the nation’s wealth, while renters’ net worth is typically one-tenth that of homeowners. The net worth middle class isn’t just about income—it’s about asset accumulation through equity. A family that bought a $300,000 home 20 years ago might now have $200,000 in equity, even if their mortgage is paid off. That same family renting for two decades would have no such asset. The catch? The barrier to entry has risen sharply. In 2000, the median home price was $150,000; today, it’s over $400,000. For first-time buyers, this means either moving to lower-cost areas (and accepting lower wages) or waiting decades to build enough savings. The net worth middle class is increasingly a club with a $100,000 initiation fee—one that many can’t afford.3. Student Debt Erases Generational Wealth
Student loans don’t just delay homeownership—they rewrite the rules of the net worth middle class. A 2023 Brookings Institution study found that households with student debt have net worths 40% lower than those without, even when controlling for income. The debt doesn’t just reduce disposable income; it forces trade-offs that ripple across decades. Someone paying off $50,000 in loans at 6% interest might skip retirement contributions or emergency savings, ensuring their net worth growth stalls. The impact is generational. Parents who took on debt to send their children to college often see their own net worth middle class status evaporate, while their kids inherit both the debt and the higher cost of living. This isn’t just a personal finance issue—it’s a wealth transfer crisis, where the middle class funds the next generation’s middle class at the expense of their own.4. Retirement Savings Are the Wildcard
The net worth middle class is a house of cards when it comes to retirement. A 2023 Pew Research report found that only 50% of middle-class households have retirement savings, and the median balance for those who do is $65,000. That’s barely enough to supplement Social Security for a few years. The problem isn’t just saving—it’s timing. Someone who starts contributing to a 401(k) at 25 with employer matches can retire comfortably. Someone who starts at 40? They’re playing catch-up in a system designed for early starters. Here’s the paradox: The net worth middle class is supposed to be stable, but retirement insecurity makes it volatile. A single market downturn in the years before retirement can wipe out decades of savings. And with life expectancies rising, the buffer between "retirement age" and "retirement reality" is shrinking.5. The Geography of Net Worth Middle Class
Where you live dictates whether you’re middle class—or just pretending to be. In San Francisco, a net worth of $1 million might still feel precarious; in Tulsa, it’s a ticket to generational wealth. The cost of living index isn’t just a number—it’s the difference between a net worth middle class that’s secure and one that’s illusionary. A couple earning $120,000 in New York might have a net worth of $150,000, while the same income in Ohio could yield $400,000. This isn’t just about housing. Healthcare costs, state taxes, and even the local job market can swing net worth trajectories. A teacher in Texas might retire with a comfortable net worth; one in California might rely on family for support. The net worth middle class isn’t a national average—it’s a zip code lottery.6. The Silent Killer: Lifestyle Inflation
> "The middle class doesn’t just spend their income—they spend their future net worth on things that depreciate faster than they appreciate." — Thomas Piketty, economist A $70,000 salary feels like a middle-class paycheck until you factor in the latte factor’s evil twin: the subscription trap, the car payment that outlasts the car’s value, and the vacation debt that lingers long after the trip. The net worth middle class is often defined by what it doesn’t own—no stock portfolio, no rental properties, no diversified assets—because those things require delayed gratification. Instead, the middle class buys liability disguised as lifestyle: a leased SUV, a gym membership never used, or a "smart" home full of gadgets that break in three years. The danger? These choices don’t just reduce net worth—they redefine what middle class means. A family that trades homeownership for a bigger TV isn’t just making a spending decision; they’re opt[ing] out of the net worth middle class entirely.7. The Net Worth Middle Class Is a Political Football
Politicians love to talk about the middle class, but they rarely define it by net worth. Income thresholds (often $50,000–$150,000) ignore the fact that a couple earning $120,000 with $200,000 in student debt and no savings is financially middle class in name only. Meanwhile, a family earning $90,000 with a paid-off home and $300,000 in retirement accounts is wealthy by net worth standards but might not qualify for middle-class tax breaks. This disconnect matters. Policies that assume the net worth middle class is homogeneous—whether it’s student debt forgiveness, housing subsidies, or retirement incentives—miss the mark. The result? Programs that help the wealthy (homeowners with large mortgages) while leaving the truly precarious (renters with no assets) behind.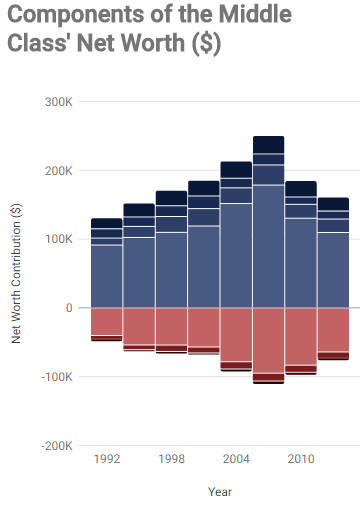
How These Facts Connect
The net worth middle class isn’t a static line—it’s a feedback loop where debt, geography, and timing collide. Homeownership amplifies wealth for those who can afford it, while student debt and lifestyle choices siphon wealth from those who can’t. Retirement savings act as both a safety net and a pressure valve: the more you save, the more secure your net worth middle class status becomes—but the system is rigged against late starters. The most revealing insight? The net worth middle class is less about income and more about time. A 30-year-old with a six-figure salary might feel secure, but their net worth could be negative if they’re drowning in debt. A 60-year-old with the same salary might have a net worth of $800,000 if they bought a home 30 years ago and avoided lifestyle inflation. The gap isn’t just about money—it’s about decades of compounded choices.| Factor | Impact on Net Worth Middle Class | Example |
|---|---|---|
| Homeownership | +70% higher net worth vs. renters | A 2003 home purchase → $250K equity by 2024 |
| Student Debt | -40% net worth vs. no-debt peers | $50K loan at 6% → $150/month payment for 10+ years |
| Retirement Savings | +3x net worth at retirement | $500/month 401(k) → $500K+ by 65 |

Conclusion
The net worth middle class is a myth for many—and a reality for those who understand the rules. It’s not about hitting a specific income threshold; it’s about building a financial foundation that outlasts market cycles, career shifts, and unexpected expenses. The good news? The mechanics are clear: own a home, avoid crippling debt, save aggressively, and let time do the heavy lifting. The bad news? The system is stacked against those who start late, earn less, or live in high-cost areas. The conversation about the net worth middle class needs to shift. It’s not enough to say, "Work harder, save more." The reality is that geography, policy, and luck play as big a role as personal discipline. The middle class isn’t failing—it’s being outmaneuvered by forces beyond its control. The question isn’t whether you’re middle class; it’s whether your net worth reflects that status—and what you’re willing to do to close the gap.Comprehensive FAQs
Q: What’s the average net worth for a middle-class family?
The Federal Reserve’s most recent data puts the median net worth for U.S. households at around $138,000, but this varies wildly by age, region, and homeownership status. A 35-year-old couple with no home may have a net worth in the $20,000–$50,000 range, while a 55-year-old homeowner could exceed $400,000. The "average" is misleading—median is more accurate, but even that hides deep divides.
Q: Can you be middle-class by income but not by net worth?
Absolutely. A family earning $100,000–$150,000 annually might qualify as middle-class by income but have a net worth below $50,000 if they’re burdened by student debt, car loans, or high living costs. Conversely, a couple earning $80,000 with a paid-off home and $200,000 in retirement savings is wealthier by net worth than many higher earners. The two metrics don’t always align.
Q: Does homeownership always boost net worth?
Not if you buy at the wrong time or take on too much debt. A homeowner who bought during a bubble (2006–2007) or stretched beyond their means may see their net worth decline if they can’t sell or refinance. The key is buying below market value, holding long-term, and ensuring the mortgage doesn’t consume more than 28% of gross income. Renting in a high-appreciation area can sometimes yield higher net worth growth than owning in a stagnant market.
Q: How does student debt affect net worth middle class status?
Student loans don’t just reduce disposable income—they delay asset accumulation. A 2023 study found that borrowers with $50,000 or more in student debt have net worths $150,000 lower than non-borrowers with similar incomes. The debt forces trade-offs: skipping retirement contributions, delaying home purchases, or taking lower-paying jobs to manage payments. The net worth middle class becomes invisible for those trapped in this cycle.
Q: Is the net worth middle class shrinking?
Yes, but not uniformly. For younger generations, the net worth middle class is harder to reach due to higher education costs, stagnant wages, and housing inflation. However, older homeowners with equity are faring better. The shrinking isn’t linear—it’s a pyramid where the base (young adults) is narrowing while the top (homeowning boomers) remains stable. Without policy changes (student debt relief, housing reform), the trend will likely continue.
Q: Can you recover if your net worth middle class status slips?
Recovery is possible, but it requires aggressive action. Steps include:
- Eliminating high-interest debt (credit cards, payday loans) first.
- Building a $10K emergency fund to avoid further debt.
- Maximizing tax-advantaged accounts (401(k), IRA) to accelerate savings.
- Side income or skill-building to increase earning potential.
- Negotiating lower costs (refinancing mortgages, downsizing housing).
