Breaking Down the Numbers
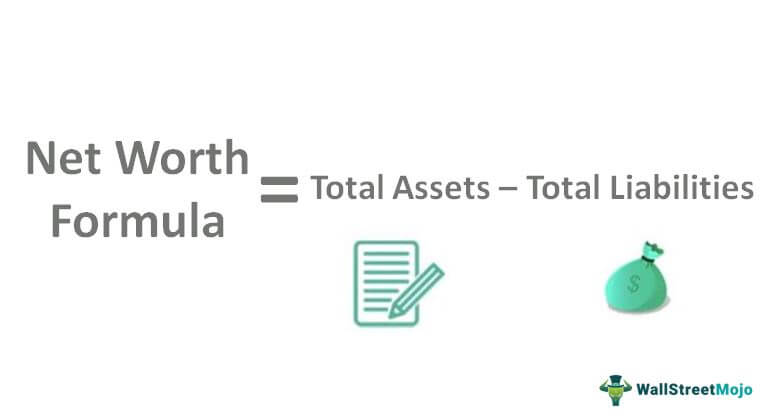
At its core, the net worth formula calculation is a snapshot of financial health, but the snapshot is never complete. Assets—cash, investments, property—are the building blocks, but their values fluctuate based on external forces. A retirement account’s worth today may not reflect tomorrow’s market returns. Meanwhile, liabilities aren’t just debts; they include mortgages, loans, and even unpaid taxes. The challenge isn’t just tallying these figures but understanding their volatility. A sudden medical bill or a stock market crash can rewrite the equation overnight, making net worth less a measure of stability and more a reflection of exposure. The real art lies in categorization. Not all assets are liquid, and not all liabilities are equal. A private company’s valuation requires expert appraisal, while a credit card balance is straightforward. The net worth formula calculation must account for these disparities—whether it’s distinguishing between a fully vested 401(k) and a restricted stock unit, or separating a primary residence’s equity from a vacation home’s depreciating value. Even the timing of the calculation matters. A year-end assessment might show a higher net worth than a mid-year check, simply because bonuses or tax refunds haven’t yet been received.The Verified Baseline
Publicly disclosed net worth figures—such as those reported by billionaires or listed on corporate filings—provide the most concrete starting point. For example, a CEO’s compensation package might include a base salary, bonuses, and stock awards, all of which contribute to net worth. However, even these figures are often incomplete. Restricted stock units (RSUs) vest over time, meaning their full value isn’t realized immediately. Similarly, deferred compensation or unexercised options may not appear as liquid assets. The net worth formula calculation in such cases relies on estimates of future realizable value, which introduces uncertainty. For individuals without public disclosures, the baseline is built from verifiable documents: bank statements, property deeds, loan agreements, and investment account summaries. These provide a foundation, but gaps remain. Offshore accounts, trusts, and privately held businesses often lack transparent valuations. Even for high-net-worth individuals, the net worth formula calculation is rarely a single number but a range—one that accounts for both realized and unrealized gains, as well as potential future liabilities like estate taxes or legal judgments.What the Estimates Suggest
Beyond the verifiable, estimates dominate the net worth formula calculation. For instance, a family-owned business’s value might be estimated using comparable sales or earnings multiples, but these are educated guesses. Art collections, rare wines, or vintage cars may appreciate over time, but without a sale, their worth is speculative. Industry analysts often adjust net worth figures based on trends—such as rising real estate prices or tech stock rallies—but these adjustments are reactive, not predictive. Tax filings offer another layer of estimation. The IRS requires asset disclosures, but valuations are self-reported, leaving room for interpretation. A farmer’s land might be valued at current market rates, while a startup founder’s equity could be based on the latest funding round—neither of which reflects real-time liquidity. Even for the ultra-wealthy, the net worth formula calculation is less about certainty and more about plausible ranges. A billionaire’s net worth might be reported as "$X billion," but the actual figure could be higher or lower depending on unrecorded assets, pending lawsuits, or undisclosed debts.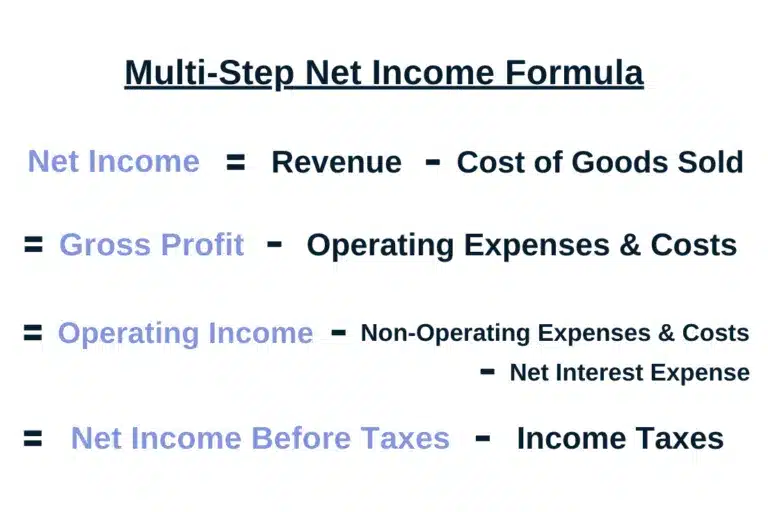
Case Study: A Closer Look
Consider the net worth of a mid-career professional in their early 40s, with a mix of liquid and illiquid assets. Their net worth formula calculation might start with a primary residence valued at $800,000, a retirement account worth $500,000, and a side business generating $200,000 annually—but the business’s valuation is unclear. If the business is privately held, its worth could range from $1 million to $3 million, depending on growth projections. Meanwhile, student loans totaling $100,000 and a car loan of $30,000 reduce the total. The result? A net worth somewhere between $1.4 million and $2.6 million, with significant uncertainty around the business’s value. This individual’s financial picture changes dramatically if the business stalls or if housing prices dip. A 10% drop in real estate values could erase $80,000 in equity overnight. Conversely, a successful exit strategy for the business could double its valuation. The net worth formula calculation here isn’t a fixed point but a spectrum—one that shifts with economic conditions, personal decisions, and unforeseen events."Net worth is a snapshot, not a forecast. The real skill isn’t in calculating it once but in understanding how it moves—and how to protect it when the market turns." — Financial planner specializing in high-net-worth individuals
| Factor | Estimated Impact on Net Worth |
|---|---|
| Primary Residence Value | ±$80,000 (subject to market fluctuations) |
| Business Valuation (Private) | $1M–$3M (depends on growth and industry multiples) |
| Pending Student Loan Payoff | +$100,000 (if accelerated; otherwise, ongoing liability) |
What This Means Going Forward
The net worth formula calculation is evolving with technology and shifting financial behaviors. Digital assets—cryptocurrency, NFTs, or decentralized finance holdings—complicate the equation, as their values are highly volatile and often lack clear regulatory frameworks. For younger generations, student debt and gig economy income create new variables, while older cohorts grapple with healthcare costs and long-term care planning. The traditional assets-liabilities model is no longer sufficient; modern net worth must account for intangibles like human capital (earning potential) and social capital (network value). Financial advisors increasingly use dynamic modeling to project net worth over time, incorporating scenarios like inflation, job loss, or inheritance. The net worth formula calculation is becoming less about a single number and more about resilience—how well an individual can withstand financial shocks. For institutions, this means stress-testing portfolios; for individuals, it means diversifying beyond traditional assets and planning for liquidity needs in uncertain markets.
Conclusion
The net worth formula calculation is both simpler and more complex than it appears. On one hand, it’s a basic arithmetic exercise: subtract what you owe from what you own. On the other, it’s a reflection of life’s unpredictability—where a single event can alter the equation entirely. The ultra-wealthy may obsess over offshore accounts and private equity stakes, while the middle class focuses on mortgages and retirement savings, but the core challenge remains the same: how to measure what can’t always be measured. For most people, the goal isn’t perfection but awareness. Understanding the gaps in the net worth formula calculation—whether it’s undervalued assets, hidden liabilities, or future obligations—is the first step toward financial security. The number itself is less important than the story it tells: about risk tolerance, generational wealth, and the ever-present question of what happens next.Comprehensive FAQs
Q: Does net worth include future income, like expected bonuses or raises?
A: No. Net worth is based on current assets and liabilities, not future earnings. However, financial planners sometimes incorporate human capital—your earning potential—into broader wealth assessments, though this isn’t part of the standard net worth formula calculation.
Q: How often should I recalculate my net worth?
A: At least annually, but more frequently if your financial situation changes—such as after a major purchase, sale, or inheritance. Quarterly checks can help track progress, especially during volatile markets. The net worth formula calculation is only useful if it reflects your current reality.
Q: Are there assets that should never be included in net worth?
A: Generally, no—but some items are impractical to value or irrelevant. For example, personal belongings like furniture or clothing are rarely included unless they hold significant sentimental or collector’s value. The net worth formula calculation focuses on assets with measurable liquidity or appreciation potential.
Q: Can net worth be negative, and what does that mean?
A: Yes. A negative net worth occurs when liabilities exceed assets, which is common for young adults with student debt or homeowners with underwater mortgages. It doesn’t mean financial ruin—many people rebuild wealth over time—but it signals a need for debt management or income growth strategies.
Q: How do taxes affect net worth calculations?
A: Taxes reduce net worth in two ways: they’re a liability (unpaid taxes lower your balance), and they erode asset values (e.g., capital gains taxes cut into investment returns). The net worth formula calculation should account for both current tax obligations and future liabilities, such as estate taxes for high-net-worth individuals.
Q: Should I include my spouse’s or partner’s assets in my net worth?
A: It depends on whether the assets are jointly owned. If they’re separate, they shouldn’t be included in your personal net worth formula calculation. However, for couples planning jointly, combining assets provides a clearer picture of total household wealth.
Q: What’s the difference between net worth and liquid net worth?
A: Net worth includes all assets and liabilities, while liquid net worth excludes illiquid assets (like a primary residence or a business) and only counts cash, investments, and easily convertible holdings. The net worth formula calculation is broader; liquid net worth is a subset used for emergency planning or short-term financial needs.
Q: Can net worth be manipulated for tax or legal purposes?
A: Yes, but it’s often unethical or illegal. Strategies like transferring assets to trusts or offshore accounts can reduce taxable net worth, but they don’t change the underlying financial reality. The net worth formula calculation must remain transparent to avoid penalties or disputes, especially in high-asset divorces or estate planning.
