7 Things Worth Knowing About Net Worth by Annual Income
The numbers behind wealth accumulation are deceptive. Income alone doesn’t dictate net worth—it’s a starting point. Here’s what actually moves the needle.1. The Wealth Gap Isn’t Just About Salary
Income disparities explain some of the divide, but inherited wealth and asset appreciation account for far more. According to Federal Reserve data, the bottom 50% of households hold just 2.6% of all wealth, while the top 10% control nearly 70%. A $200,000 annual income might feel middle-class in many cities, but if your parents left you a home worth $500,000, your net worth could already be in the seven figures. Meanwhile, someone earning the same salary but starting from zero might struggle to cross the $1 million threshold in a lifetime. The net worth by annual income ratio flips when you factor in generational wealth. The problem deepens when you consider liquidity. A high earner with no savings or investments may have a net worth tied to a single asset—like a home—while someone with a modest income but diversified holdings could outpace them. This is why two people in the same tax bracket can have wildly different financial trajectories.2. Geography Rewrites the Rules
Cost of living isn’t just about groceries and rent—it’s about opportunity costs. A $100,000 income in San Francisco might yield a net worth growth rate of 2% annually if housing prices rise, while the same income in Des Moines could see 8% growth due to lower expenses and stronger local markets. The net worth by annual income calculus shifts based on whether you’re in a high-tax state like California or a no-income-tax state like Texas. Even within cities, neighborhoods dictate wealth accumulation: a $150,000 earner in a gentrifying Brooklyn brownstone district could see their home’s value double in a decade, while a similar earner in a stagnant suburb might see theirs depreciate. Tax policies amplify these effects. States with high property taxes (like New Jersey) can erode net worth faster than those with none (like Florida). A $250,000 income in one state might net you $300,000 in assets after a decade, while the same income in another could leave you flat.3. Time in the Market Beats Timing the Market
The S&P 500’s average annual return is around 10% over long periods, but most people don’t hit that because they enter and exit at the wrong times—or worse, never invest. A $120,000 earner who maxes out a 401(k) and IRA from age 25 could see their retirement accounts grow to $2.5 million by 65, assuming consistent contributions. Meanwhile, someone earning $200,000 who dips into investments for short-term gains might end up with half that. The net worth by annual income equation favors those who treat saving as non-negotiable, not those who chase higher salaries at the expense of long-term growth. Compounding is the silent multiplier. A $50,000 salary with $10,000 annual investments at 7% returns could turn into $1.2 million over 30 years. Skip the first five years, and you’re looking at $700,000. The difference isn’t just time—it’s discipline.4. Debt Isn’t the Enemy—If Managed Right
Student loans, mortgages, and credit cards all drag down net worth, but some debt accelerates wealth. A $150,000 earner who takes out a 30-year mortgage at 4% interest might see their home’s value outpace the loan’s cost, especially in appreciating markets. Meanwhile, someone who avoids debt entirely but stashes cash in low-yield savings accounts could watch their net worth by annual income ratio shrink over time. The key is leveraging debt for appreciating assets—like real estate or education—rather than depreciating ones. High-interest debt (like credit cards) is the exception. A $100,000 income with $20,000 in credit card debt at 20% APR could see their net worth shrink by $4,000 a year in interest alone. The math is brutal: for every dollar earned, 4% goes to servicing debt instead of building assets.5. Lifestyle Inflation Sabotages Long-Term Growth
Promotions often come with bigger houses, cars, and subscriptions—not necessarily bigger net worth. A $200,000 earner who upgrades to a $1.2 million home in a high-maintenance neighborhood might see their net worth dip if they stretch their budget. The same income in a modest home with a side hustle could see faster wealth accumulation. The net worth by annual income ratio suffers when spending grows at the same rate as earnings, leaving nothing for investments or savings. Psychology plays a role. People tend to spend more when they earn more, even if they don’t need to. A $300,000 income might feel like a license to splurge, but without reinvestment, that money disappears into depreciating assets. The highest-net-worth individuals don’t just earn more—they spend less relative to their income.6. Career Trajectories Matter More Than Titles
A doctor’s income peaks later in life, while a tech executive’s might spike early. A surgeon earning $300,000 at 40 could have a net worth of $1.5 million by 50 if they save aggressively, while a software engineer earning $200,000 at 30 might see their net worth stagnate if they burn out or switch jobs frequently. The net worth by annual income curve isn’t linear—it’s shaped by career stability, industry trends, and how early you start optimizing for wealth. Fields with high barriers to entry (like law or medicine) often correlate with higher net worth because they attract disciplined, long-term thinkers. Creative or gig-based careers, by contrast, can yield high incomes but volatile net worth due to irregular cash flow.7. Luck and Timing Are Wildcards
"Wealth is partly skill, partly power, and partly luck. And in that order." — Nassim Nicholas TalebA $150,000 earner who inherits $500,000 could see their net worth triple overnight. Someone in the same income bracket who loses a job during a recession might watch their investments halve. The net worth by annual income ratio isn’t just about effort—it’s about being in the right place at the right time. Real estate booms, stock market crashes, and even health crises can reshape wealth trajectories faster than salary increases. This is why ultra-high-net-worth individuals often attribute success to "luck" more than hard work. The truth is that systemic advantages—like access to private equity or timing a market recovery—play a huge role in who ends up ahead.
How These Facts Connect
The data reveals a system where income is the engine, but geography, timing, and debt act as accelerators or brakes. A $250,000 earner in Austin might outpace a $300,000 earner in New York because of lower costs and stronger local markets. Meanwhile, someone earning $100,000 who starts investing at 22 could surpass a $150,000 earner who waits until 35. The net worth by annual income relationship isn’t static—it’s a moving target influenced by external forces beyond individual control. What’s clear is that wealth isn’t just about how much you earn; it’s about how you deploy that income. Savers and investors build equity over time, while spenders and speculators often find themselves chasing their tails. The highest-net-worth individuals aren’t always the highest earners—they’re the ones who optimize for compounding, minimize drag, and ride the waves of opportunity.| Factor | Impact on Net Worth | Example |
|---|---|---|
| Geography | Can double or halve growth rates | A $150K earner in Texas vs. California |
| Investment Discipline | 10x difference over 30 years | $10K/year invested vs. $0 |
| Debt Strategy | Good debt accelerates wealth; bad debt erodes it | Mortgage vs. credit card debt |
Conclusion
The myth of "earn more, get richer" ignores the mechanics of wealth accumulation. Income is the foundation, but net worth is the result of how you interact with that income—through saving, investing, and managing risk. The net worth by annual income ratio isn’t a fixed number; it’s a dynamic interplay of choices, circumstances, and luck. For most people, the path to building wealth isn’t about hitting a salary milestone but about optimizing the levers they control: spending habits, asset allocation, and long-term planning. The good news? Unlike inherited wealth or market timing, these levers are within reach for anyone willing to make the effort. The bad news? The system is rigged in favor of those who already have a head start. Understanding net worth by annual income isn’t about changing the game—it’s about playing it smarter.Comprehensive FAQs
Q: Can I estimate my net worth based on income alone?
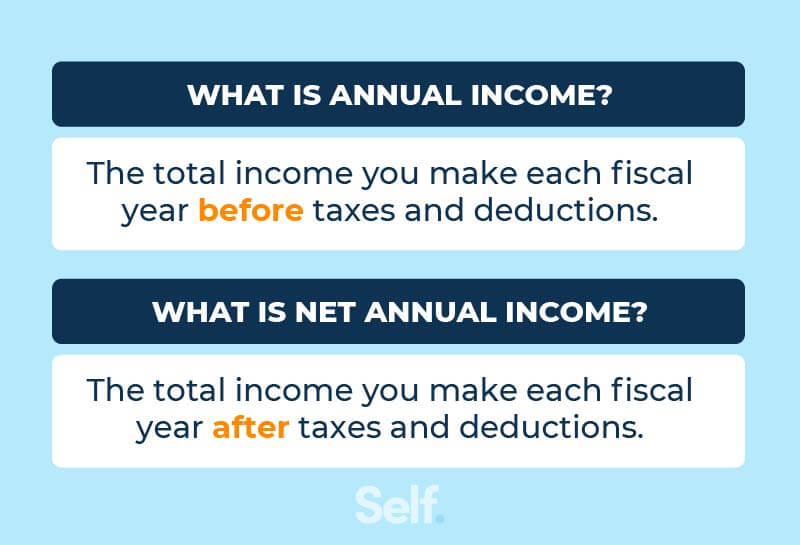
A: No. Income is just one input. Net worth depends on assets (home, investments, savings), liabilities (debt, loans), and time. Two people with the same income can have net worths differing by millions due to these factors.
Q: Does a higher income always mean higher net worth?
A: Not necessarily. High earners often face higher taxes, lifestyle inflation, and opportunity costs (like time spent working). Some of the wealthiest individuals earn modest incomes but optimize savings and investments relentlessly.
Q: How does student loan debt affect net worth by income?
A: It can severely drag down net worth, especially if interest rates are high. A $100,000 income with $50,000 in student debt might see net worth grow slower than someone with the same income but no debt, assuming similar spending and savings rates.
Q: Is it better to save aggressively at a lower income or wait for a higher salary?
A: Starting early—even at a lower income—gives compounding more time to work. A $60,000 earner saving $10,000/year at 25 can outpace a $120,000 earner who starts saving at 35, assuming similar investment returns.
Q: How does divorce impact net worth by income?
A: It can halve assets overnight. A couple with a combined $300,000 income and $2 million net worth might split into two households with $150,000 incomes and $1 million each—unless one spouse takes on significantly more debt or loses assets in the division.
Q: Can you build significant net worth on a modest income?
A: Yes, but it requires extreme discipline. A $50,000 earner who saves 50%, invests wisely, and avoids lifestyle inflation can reach $1 million in net worth within 20–30 years, depending on market returns and geographic costs.
Q: How do side hustles affect the net worth by income equation?
A: They can accelerate wealth if profits are reinvested. A $100,000 primary income with a $20,000/year side hustle that’s fully invested could see net worth grow 20–30% faster than someone relying solely on their day job.
Q: What’s the biggest mistake people make when tracking net worth by income?
A: Ignoring liabilities. Many focus only on assets (home, stocks) and overlook debt (mortgages, credit cards, student loans), which can obscure true financial health. A $500,000 home with $400,000 in debt leaves little equity—despite the high income.
