The Complete Overview of "Assets Minus Liabilities"
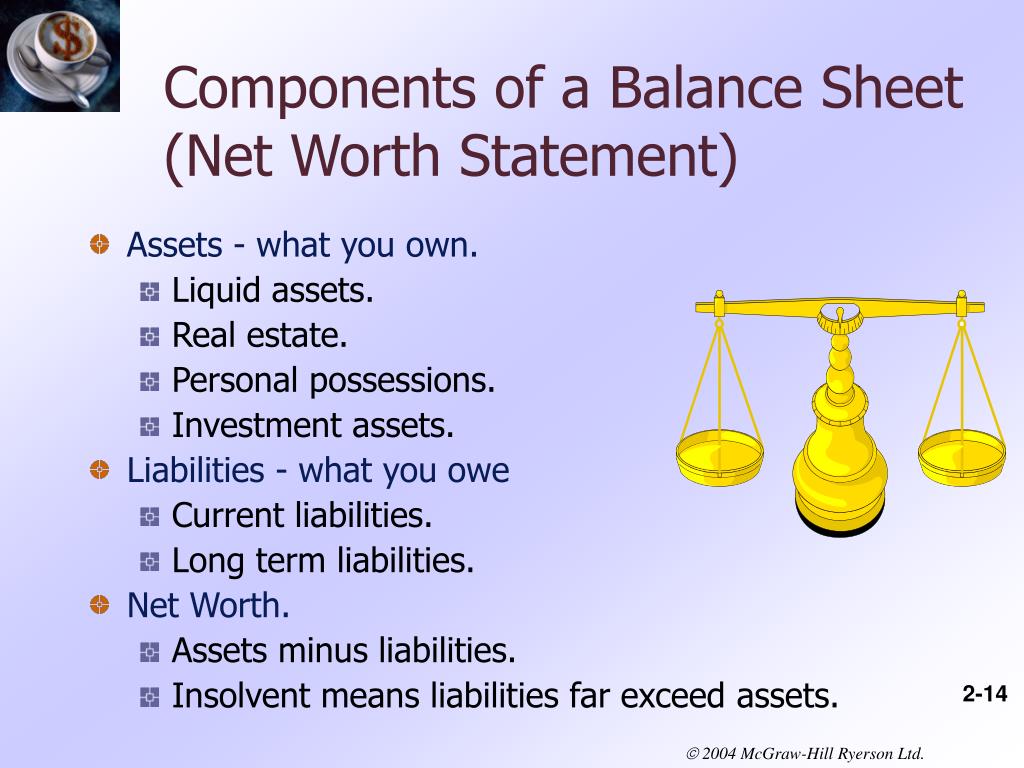
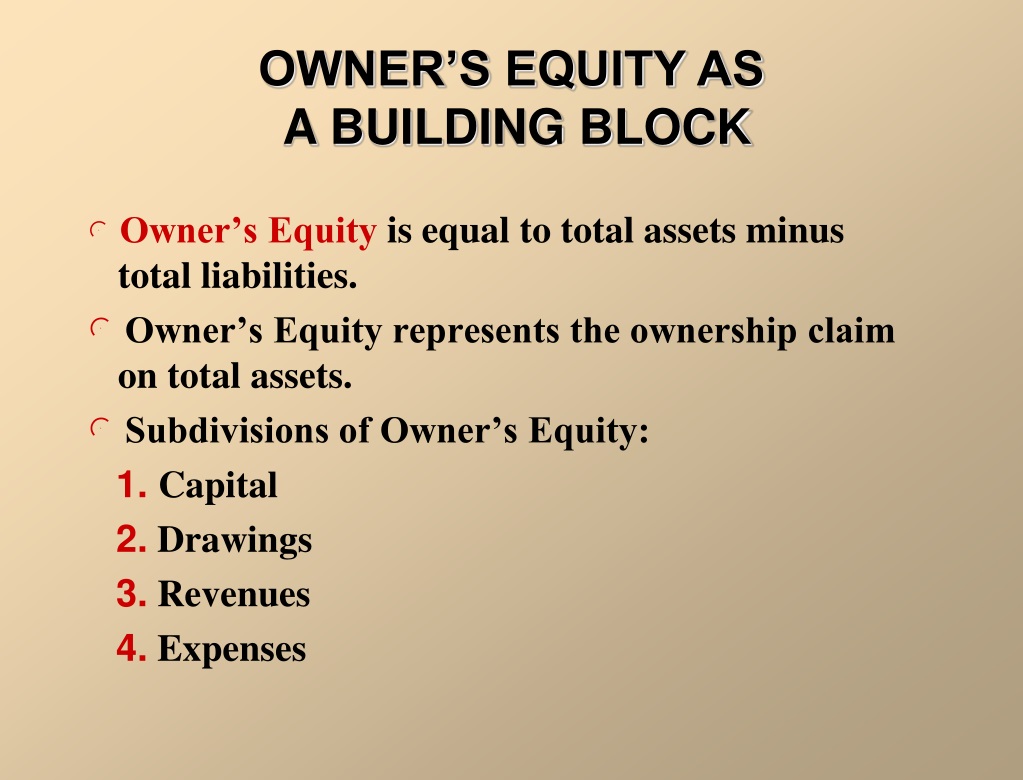
At its simplest, assets minus liabilities is the net worth calculation—what remains after subtracting all debts from everything owned. But the term operates across scales: for individuals, it’s personal finance; for businesses, it’s solvency; for nations, it’s fiscal health. The phrase itself is deceptively narrow, yet it encapsulates the core of financial risk. A bank won’t lend based on income alone; it scrutinizes the borrower’s assets minus liabilities to gauge repayment capacity. Investors don’t buy stocks for their dividends; they assess whether the company’s net assets justify its market price. Even governments use this ratio to determine eligibility for bailouts or infrastructure grants. The genius of the concept lies in its adaptability. Accountants, economists, and laypeople all wield the same tool, though their interpretations diverge. A real estate developer might focus on tangible assets like land and equipment, while a software firm prioritizes intellectual property and customer contracts. The liabilities side isn’t just debts—it includes contingent obligations, like lawsuits or unfulfilled warranties. The result? A figure that’s part math, part judgment call. For example, a family home might be valued at market price, but if it’s underwater on a mortgage, its contribution to assets minus liabilities could be negative. The equation forces clarity: financial health isn’t about assets alone, but the gap between what you control and what you’re obligated to pay.Historical Background and Evolution
The idea of netting assets against liabilities traces back to medieval merchant ledgers, where traders recorded inventory against trade debts. By the 17th century, European banks formalized the practice to assess loan risks, laying the groundwork for modern credit scoring. The term "net worth" entered common usage in the 19th century as industrialization created complex corporate structures. Railroads and factories required massive capital, and investors demanded transparency—hence the birth of audited balance sheets, where assets minus liabilities became the bottom line. The 20th century transformed the concept into a cultural touchstone. During the Great Depression, personal bankruptcies surged, forcing courts to refine how assets minus liabilities determined insolvency. Post-WWII, the rise of consumer credit—mortgages, car loans, credit cards—made the equation a household concern. Today, algorithms and big data have automated the calculation, but the principle remains unchanged: lenders, insurers, and even dating apps now factor net worth into decisions. The shift from manual ledgers to AI-driven risk models hasn’t altered the core question: What’s left after the bills are paid?Core Mechanisms: How It Works
The mechanics hinge on two pillars: what’s counted as an asset, and what’s classified as a liability. Assets range from liquid cash to illiquid real estate, while liabilities include short-term debts (credit cards) and long-term obligations (mortgages). The challenge isn’t the arithmetic—it’s the subjectivity. A vintage car collector might value their vehicles at $500,000, while a bank would appraise them at resale price. Similarly, a startup’s "assets" could include unproven patents or a loyal customer base, neither of which appear on a traditional balance sheet. The calculation becomes a game of assumptions. For individuals, retirement accounts are typically marked to market, but a small business owner might inflate equipment values to boost their assets minus liabilities. Corporations use "goodwill" to reflect brand value, though this intangible asset can vanish in a single quarter if customer trust erodes. The result? A number that’s as much about perception as it is about reality. Even governments manipulate the ratio—think of sovereign wealth funds buying foreign assets to artificially inflate their assets minus liabilities during economic crises.Key Benefits and Crucial Impact
The equation’s primary benefit is its ability to distill complexity into a single metric. A family planning for college tuition can track their assets minus liabilities to ensure savings outpace future costs. A board of directors uses the same ratio to decide whether to issue dividends or reinvest profits. The impact extends beyond finance: lenders rely on it to approve mortgages, insurers to set premiums, and even landlords to screen tenants. Without this framework, risk assessment would be guesswork. Yet the equation’s power is also its limitation. It ignores timing—cash flow matters more than a static net worth. A business with high assets but seasonal revenue might still face liquidity crises. The ratio also obscures quality: a portfolio of blue-chip stocks differs fundamentally from a pile of collectibles, even if their assets minus liabilities values match. The key insight? The number is a starting point, not an endpoint."Net worth is the residue of all your past decisions. The real question isn’t what it is today, but whether it’s trending upward—or whether you’re just delaying the inevitable by hiding liabilities off-balance-sheet." — Former CFO of a Fortune 100 firm, speaking anonymously
Major Advantages
- Risk assessment: Lenders and investors use assets minus liabilities to gauge repayment capacity or investment safety.
- Wealth tracking: Individuals monitor their financial progress by comparing net worth over time.
- Tax planning: Governments and accountants structure transactions to optimize the ratio for tax efficiency.
- Corporate valuation: Buyers and sellers determine fair market prices based on net asset value.
- Insolvency determination: Courts and creditors rely on the ratio to declare bankruptcy or restructure debts.
- Behavioral insight: The ratio reveals spending habits—high liabilities relative to assets often signal financial stress.
Comparative Analysis
| Individual Net Worth | Corporate Net Assets |
|---|---|
| Focuses on personal holdings (cash, property, investments) minus debts (mortgages, loans). | Includes tangible (equipment) and intangible (brand) assets minus liabilities like bonds and payables. |
| Used for loan approvals, estate planning, and personal financial health. | Drives M&A decisions, dividend policies, and credit ratings. |
| Subjective valuations (e.g., sentimental property values). | Regulated by GAAP/IFRS standards, though goodwill and intangibles are debated. |
| Can be volatile due to market fluctuations (e.g., stock portfolios). | More stable for mature companies, but startups may have negative net assets. |
| Improved by saving, asset appreciation, or debt reduction. | Enhanced through acquisitions, cost-cutting, or revenue growth. |
Future Trends and Innovations
The next frontier lies in real-time assets minus liabilities tracking. Blockchain and smart contracts could automate updates, ensuring net worth reflects dynamic conditions—like a freelancer’s income fluctuating with project completions. For businesses, AI-driven scenario modeling will simulate how net assets shift under different economic conditions, from interest rate hikes to supply chain disruptions. The rise of "liability insurance" products—where policies cover specific debts—will further blur the line between assets and obligations. Cryptocurrency complicates the equation. Digital assets like Bitcoin are volatile, and their classification as "assets" or "liabilities" depends on whether they’re held for investment or used as collateral. Regulators are grappling with how to treat them in insolvency proceedings, while individuals face tax implications tied to their assets minus liabilities valuations. The trend suggests the equation will become more granular, less about static snapshots and more about predictive analytics.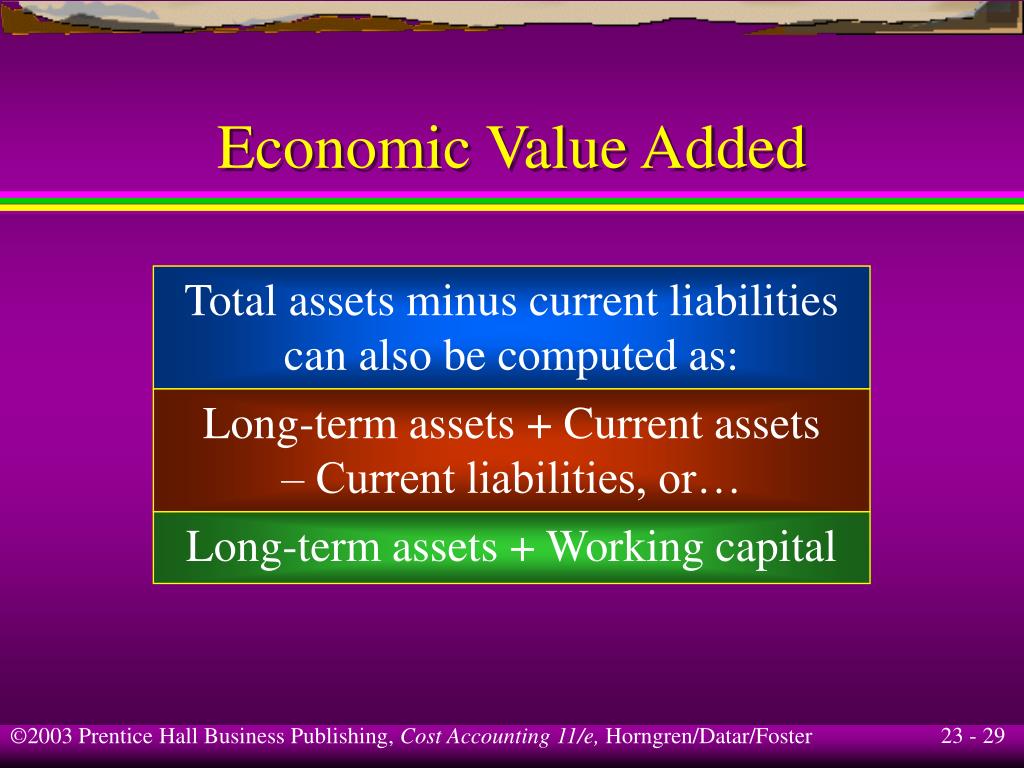
Conclusion
The phrase assets minus liabilities is more than an accounting formula—it’s a lens through which to view financial reality. Whether applied to a single household or a multinational corporation, it forces clarity in a world of uncertainty. The challenge isn’t calculating the number; it’s recognizing that the true value lies in what it omits: time, liquidity, and the human element of risk tolerance. A high net worth doesn’t guarantee security, just as a low one doesn’t preclude resilience. The equation’s enduring relevance stems from its simplicity: subtract what you owe from what you own, and you’ve just defined your starting point. The future of assets minus liabilities will be shaped by technology and shifting definitions of wealth. As intangible assets grow in importance—think data, patents, and digital identities—the traditional balance sheet will evolve. But the core question remains unchanged: What’s left after accounting for all obligations? The answer, more than ever, is the foundation of every financial decision.Comprehensive FAQs
Q: Can assets minus liabilities ever be negative?
A: Yes. When liabilities exceed assets, the result is negative net worth—a common scenario for startups, highly leveraged corporations, or individuals with significant debt. This doesn’t automatically mean insolvency, but it signals financial strain that requires restructuring (e.g., debt consolidation, asset sales) or external support (e.g., loans, investor capital).
Q: How often should I calculate my assets minus liabilities?
A: The frequency depends on your financial situation. High-net-worth individuals or business owners may track it quarterly to monitor trends, while others might review it annually. Automated tools (like personal finance apps) can simplify this process by pulling data from bank accounts, investments, and loans in real time.
Q: Do hidden liabilities (like unpaid taxes or lawsuits) affect the calculation?
A: Absolutely. Hidden or contingent liabilities—such as pending legal claims, unpaid taxes, or guarantees for others’ debts—should be included in the assets minus liabilities equation. Omitting them can lead to an overstated net worth, which is dangerous for lenders, investors, or courts evaluating insolvency. Transparency is critical.
Q: How do intangible assets (e.g., patents, brand value) factor into the equation?
A: Intangible assets are increasingly vital, especially for tech and creative industries. They’re included in assets minus liabilities if they have measurable value—patents might be appraised by a specialist, while brand value could be estimated using multiples of revenue. However, their valuation is subjective and often debated in disputes (e.g., divorce settlements, M&A negotiations).
Q: Can assets minus liabilities improve over time without active management?
A: Rarely. While passive growth (e.g., asset appreciation, inflation) can boost net worth, sustained improvement typically requires deliberate actions: reducing debt, increasing income, or investing strategically. Market conditions play a role, but relying solely on passive growth is risky—especially in low-interest-rate environments where traditional assets yield little.
Q: How do governments or regulators influence assets minus liabilities?
A: Policies like tax incentives, debt relief programs, or asset protection laws directly impact the ratio. For example, student loan forgiveness can instantly improve an individual’s assets minus liabilities, while corporate tax reforms may inflate or deflate net assets. Regulators also intervene in insolvency cases to ensure fair distributions, often recalculating net worth under strict rules.
Q: What’s the difference between assets minus liabilities and cash flow?
A: Assets minus liabilities is a snapshot of net worth at a point in time, while cash flow measures the movement of money in and out over a period. A company could have high net assets but negative cash flow if its liabilities are coming due (e.g., debt maturities). Conversely, a business with low net worth might generate strong cash flow through efficient operations. Both metrics are essential but serve different purposes.
