Common Myths About Net Worth Tracking
The first myth is that net worth is a measure of success. It’s not. A young professional with student loans and a modest salary might have a negative net worth, while a retiree with a paid-off home and modest savings could have a positive one—yet neither reflects "success" in any absolute sense. Net worth is a tool, not a trophy. The second myth is that tracking it requires advanced math or expensive software. In reality, the most effective net worth templates often start with a pen and paper—or a free spreadsheet—before scaling up. The third myth, perhaps the most damaging, is that net worth is static. It’s not. It’s a living document that should be updated monthly, if not weekly, to reflect changes in asset values, debt repayments, or new income streams. These misconceptions persist because financial education often treats net worth as an abstract concept rather than a practical skill. Most people learn to budget but rarely learn to audit their financial health. A net worth template isn’t just about tallying numbers; it’s about understanding the stories behind them. Why did your stock portfolio drop last quarter? Did you take on new debt for a "good" reason? Are your savings growing faster than your expenses? The template itself won’t answer these questions, but it will force you to ask them.Myth 1: "Net worth is just for the rich."
The idea that net worth tracking is a luxury for high-net-worth individuals is a self-fulfilling prophecy. In truth, the opposite is often true. A young professional with modest assets but significant liabilities—student loans, credit card debt, or a car payment—stands to benefit most from tracking their net worth. Why? Because small changes in spending or saving habits can have outsized effects when starting from a low base. For example, paying down $5,000 in credit card debt might not seem like much to someone with a seven-figure portfolio, but for someone with a net worth in the negative, it’s a 20% improvement in their financial position. The problem is that most people associate net worth with homeownership or stock portfolios, which are out of reach for many. But net worth isn’t about the size of your balance sheet—it’s about the direction of your finances. A freelancer with $10,000 in savings and $5,000 in debt has a net worth of $5,000. That’s not much, but if they’re adding $2,000 to their savings each year while paying down debt, their net worth is growing. The template doesn’t care about absolutes; it cares about trends. And that’s what makes it useful at any income level.Myth 2: "You need fancy software to track it."
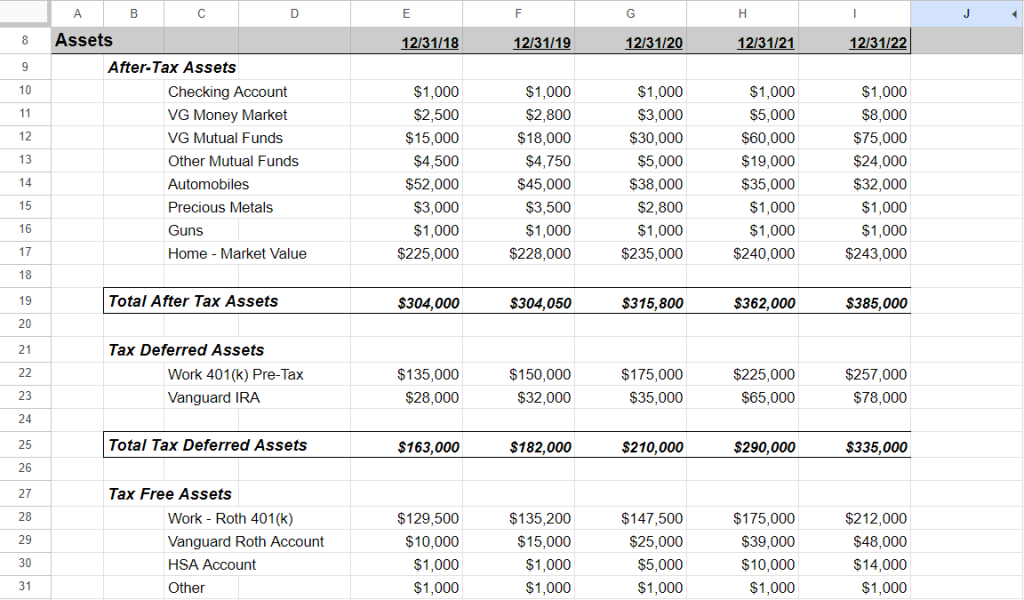
The allure of sleek financial apps—with their automated categorization and pretty dashboards—can make it seem like a net worth template requires a subscription to Mint or YNAB. But the most accurate net worth spreadsheets are often the simplest: a Google Sheet with two columns, one for assets and one for liabilities. The reason? Automation can’t account for every nuance. For example, if you own a rental property, its value might fluctuate based on market conditions, and your mortgage balance changes monthly. A manual entry ensures you’re not missing critical details, like the equity in a side business or the value of a non-liquid asset like a vintage car. That said, tools like net worth calculators built into platforms like Personal Capital or Wealthfront can save time—for those who trust their data inputs. But even these rely on a foundational understanding of what should (and shouldn’t) be included. The core principle remains: the template is only as good as the data you feed it. And no app can replace the act of thinking critically about your financial decisions.Myth 3: "Updating your net worth is a chore."
The idea that tracking net worth requires hours of work each month is another barrier to adoption. In reality, the most effective net worth templates are designed to be updated in under 30 minutes. The key is to focus on changes rather than recalculating everything from scratch. For example, if your stock portfolio drops by 5%, you don’t need to re-enter every holding—just adjust the total value. Similarly, if you pay down $200 of your credit card balance, update that line item. The goal isn’t perfection; it’s consistency. The real chore isn’t the tracking itself, but the avoidance of it. Many people procrastinate because they fear what the numbers will show. But a net worth template isn’t a judgment—it’s a mirror. And like any mirror, the only way to improve your reflection is to look at it regularly.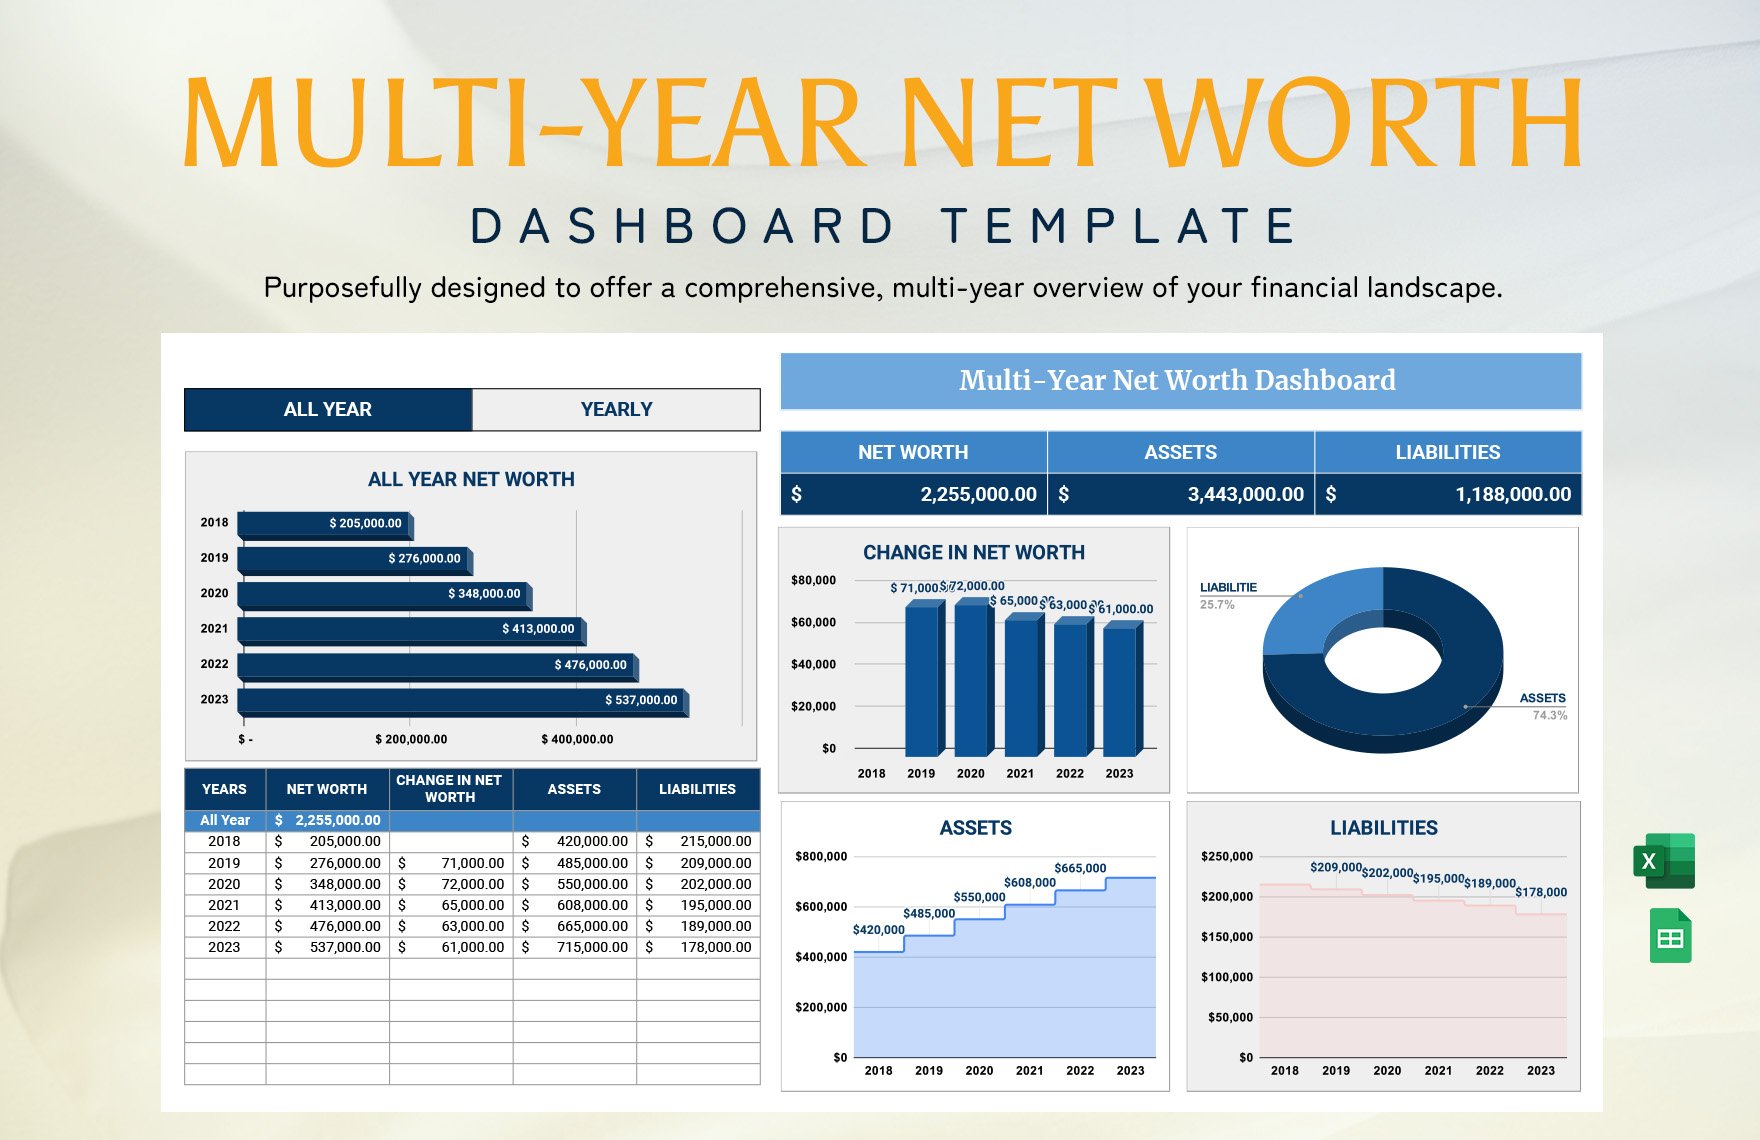
What Holds Up to Scrutiny
At its core, a net worth template is a snapshot of your financial health, but its power lies in the trends it reveals over time. For example, if your net worth grows by 10% in a year, but your income only rises by 5%, you’re likely benefiting from asset appreciation or debt reduction—not just earning more. Conversely, if your net worth stagnates while your income climbs, you might be spending aggressively or failing to invest. These insights are what make net worth tracking more than just a number-crunching exercise. The most reliable net worth systems share a few key traits: 1. Clarity on asset definitions—Is a business asset or a liability? Should you count your retirement accounts at their current value or projected future value? 2. Realistic liability tracking—Not all debt is created equal. A mortgage on a rising-value home is different from a personal loan with high interest. 3. Flexibility for life changes—A template that works for a single person might not suit a couple with shared assets or a family with trusts."Net worth isn’t about the destination; it’s about the journey. The template is just the map. What matters is whether you’re moving forward—or standing still." — Morgan Housel, The Psychology of MoneyHere’s how common beliefs stack up against evidence:
| Common Belief | What the Evidence Says |
|---|---|
| Net worth = homeownership status | Home equity is one asset, but total net worth includes investments, side income, and liabilities. A renter with a diversified portfolio can have a higher net worth than a homeowner with a mortgage. |
| You need to update your net worth monthly | Quarterly updates often suffice for most people, unless you have volatile assets (e.g., crypto, stocks) or significant debt changes. |
| Higher net worth = financial freedom | Net worth alone doesn’t determine cash flow. A high net worth individual with high expenses may still struggle with liquidity. |
| Net worth templates are only for retirement planning | They’re equally useful for debt payoff strategies, emergency fund tracking, or evaluating major purchases (e.g., a car, education). |
Why the Confusion Persists
The gap between theory and practice in net worth tracking stems from two factors: overcomplication and emotional avoidance. Financial media often glorifies extreme cases—like the "millionaire next door" or the tech founder with a $100M portfolio—while ignoring the messy reality of most people’s finances. Meanwhile, the tools themselves can be overwhelming. A spreadsheet with 50 rows of assets and liabilities might seem intimidating, but the truth is, most people only need a handful of key categories to start. The second barrier is psychological. Admitting that your net worth is lower than you thought—or that it’s not growing as fast as you’d like—can trigger stress or guilt. But a net worth template isn’t a report card; it’s a diagnostic tool. The goal isn’t to achieve a specific number, but to understand the levers you can pull to improve it. That requires separating ego from economics—a skill most financial guides don’t emphasize enough.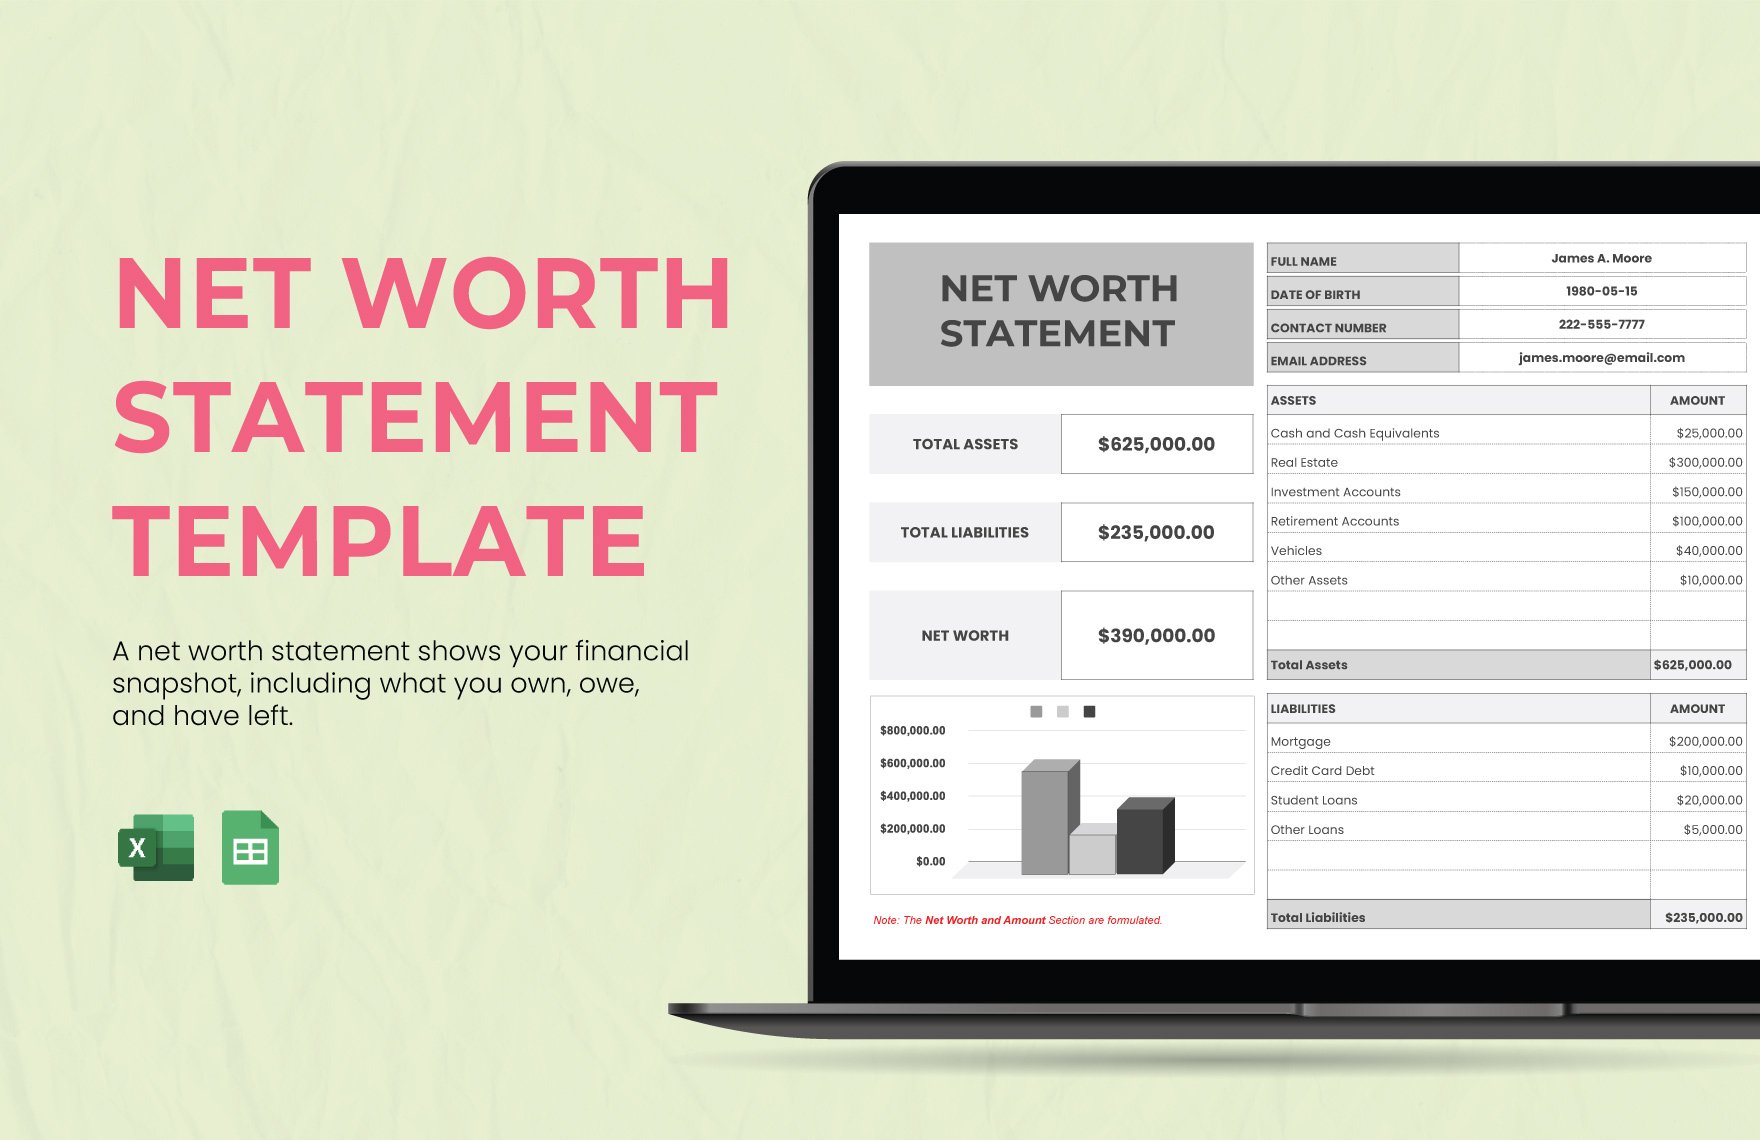
Conclusion
A net worth template isn’t a magic bullet, but it’s the closest thing to one in personal finance. It doesn’t replace discipline or strategy, but it does force clarity on what’s working and what’s not. The best net worth systems—whether a back-of-the-envelope calculation or a high-end financial dashboard—serve as a reality check. They reveal that wealth isn’t just about earning; it’s about preserving, protecting, and growing what you have. The irony is that the simplest templates often work best. You don’t need a PhD in finance to track your net worth—you just need to start. The template itself doesn’t judge. It only shows you where you are. And from there, the rest is up to you.Comprehensive FAQs
Q: Do I need to include every single asset in my net worth template?
A: No. Focus on liquid and high-value assets—cash, investments, real estate, retirement accounts, and valuable possessions (e.g., jewelry, collectibles). Smaller items (like a $200 camera) can be grouped under "miscellaneous" unless they appreciate significantly. The goal is accuracy, not perfection.
Q: Should I track my net worth if I’m in debt?
A: Absolutely. Debt is a liability, and tracking it alongside your assets helps you see the full picture. For example, if your net worth is negative but improving (e.g., due to debt payoff), that’s still progress. The template helps you measure it.
Q: Can I use a net worth template to plan for big purchases, like a house or car?
A: Yes. By projecting how a purchase would affect your assets and liabilities, you can assess whether it aligns with your long-term net worth goals. For example, buying a house might increase your assets but also add a mortgage liability—both should be reflected.
Q: How often should I update my net worth if I don’t have volatile investments?
A: Quarterly updates are sufficient for most people with stable assets (e.g., savings, a paid-off home). If you have investments that fluctuate (stocks, crypto), consider monthly updates for those specific categories.
Q: Is it better to use a spreadsheet or a financial app for tracking?
A: It depends on your comfort level. Spreadsheets (Google Sheets, Excel) give you full control over definitions and categories. Apps (Mint, YNAB) automate data entry but may miscategorize assets or liabilities if you don’t customize them. Start with what you’re comfortable with and adjust as needed.
Q: What’s the biggest mistake people make when setting up a net worth template?
A: Overcomplicating it. Many people include too many categories or obsess over minor adjustments. Start with the basics: total assets minus total liabilities. Refine as you go.
Q: Can a net worth template help me with tax planning?
A: Indirectly, yes. By tracking asset types (e.g., taxable vs. tax-advantaged accounts), you can identify opportunities for tax-efficient strategies, such as harvesting losses or optimizing retirement contributions.
Q: What if my net worth is negative? Is tracking it still useful?
A: Yes. A negative net worth is still a starting point. Tracking it helps you measure progress—whether through debt reduction, income growth, or asset appreciation. Many high-net-worth individuals started with negative net worths.
Q: How do I handle assets with fluctuating values, like stocks or crypto?
A: Update their values monthly (or more frequently if they’re highly volatile). For simplicity, you can use a "cost basis" approach (tracking purchase price) or a "market value" approach (current worth). Consistency matters more than the method.
Q: Should I share my net worth template with a financial advisor?
A: Only if you’re comfortable with transparency. A good advisor will use it to tailor advice, but ensure they understand your goals—not just the numbers. Some advisors prefer their own tools, so clarify expectations upfront.
