Breaking Down the Numbers
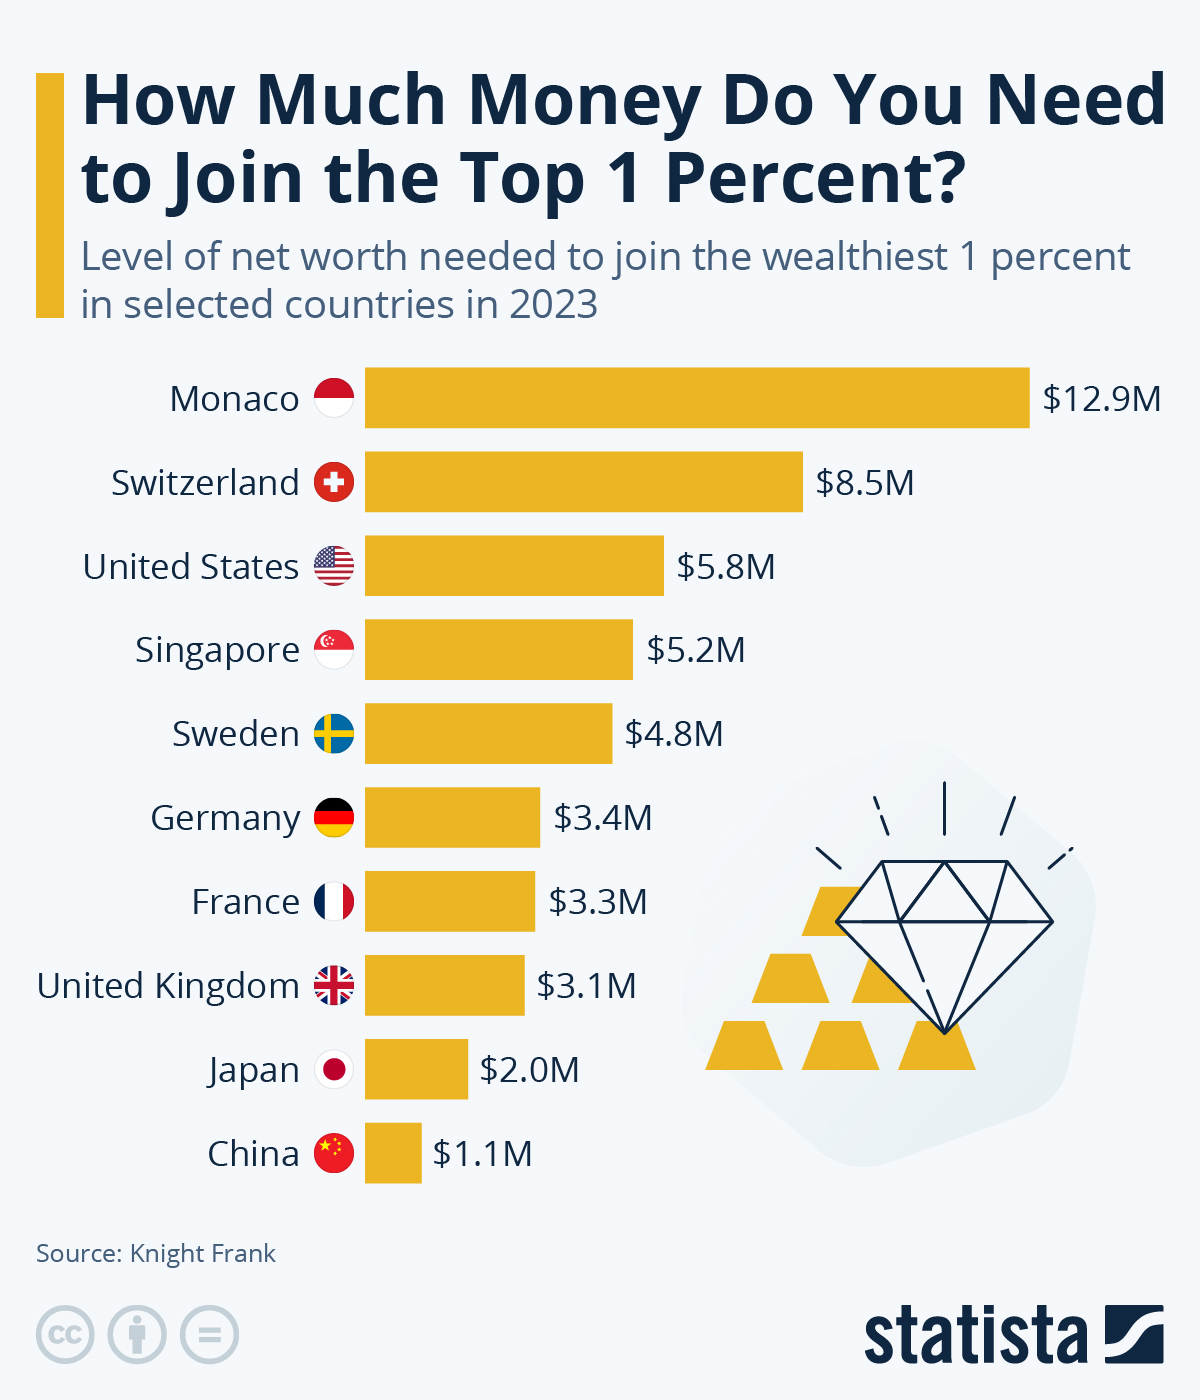
The net worth top one percent is a moving target, but the thresholds are clear: in the U.S., the cutoff hovers around $10–15 million for a household, depending on the year’s inflation adjustments. Globally, the bar shifts—£8 million in the UK, €12 million in the Eurozone—but the principle remains: these figures represent not just income but accumulated capital across decades. The distinction matters because income can be earned and spent, while net worth is a stock of assets that can be deployed strategically. What’s less discussed is how this wealth is structured. The ultra-rich don’t hold their fortunes in diversified mutual funds. Instead, their portfolios are concentrated in private equity, venture capital, and real estate, assets that benefit from tax deferrals, depreciation write-offs, and limited partner protections. A tech CEO’s reported net worth might spike after an IPO, but the real wealth lies in unlisted stakes that appreciate quietly. Meanwhile, the average worker’s 401(k) faces market risk without such safeguards.The Verified Baseline
Public filings and tax transparency initiatives—like the EU’s mandatory wealth disclosures—provide a floor for what we know. For instance, the Forbes Real-Time Billionaires List tracks net worth figures for the ultra-wealthy, though these are self-reported and subject to interpretation. In 2023, the list’s top 10 individuals collectively held assets exceeding $1 trillion, with figures like Elon Musk and Jeff Bezos seeing fluctuations tied to stock performance and personal spending. What’s verifiable is that concentration matters more than absolute numbers: the top 0.1 percent (the wealthiest 1 in 1,000) control a disproportionate share of global assets. Beyond individuals, institutional players dominate. BlackRock and Vanguard, the world’s largest asset managers, hold stakes in nearly every major corporation, effectively acting as shadow trustees for the net worth top one percent. Their influence isn’t just financial—it’s regulatory. When these firms lobby for policies that favor passive investing or lower capital gains taxes, they’re protecting the very structures that sustain their clients’ wealth.What the Estimates Suggest
Industry estimates paint a broader picture, though with necessary caveats. Credit Suisse’s Global Wealth Report suggests that the net worth top one percent owns 43% of global wealth, up from 33% in 2000. The jump isn’t just due to market returns—it’s a result of asset price inflation, where real estate and equities have outpaced wage growth. For example, a London property portfolio that cost £5 million in 2000 might now be worth £20 million, but the underlying rental income hasn’t kept pace with living costs elsewhere. The estimates also highlight generational transfer. A 2022 study by the Institute for Policy Studies found that $41.1 trillion in wealth will change hands over the next three decades, with the majority flowing to heirs of the current top 1 percent. This isn’t just about inheritance taxes—it’s about trust structures that allow wealth to bypass estate duties entirely. A family might transfer assets to a trust decades before a death, ensuring the net worth remains intact across generations.
Case Study: A Closer Look
Consider the case of Michael Bloomberg, whose net worth has oscillated between $50–60 billion over the past decade. His fortune isn’t just tied to Bloomberg LP’s media empire—it’s embedded in private equity stakes, real estate holdings, and political investments. When he sold his weather data unit to IBM for $2.8 billion in 2013, the proceeds weren’t taxed as capital gains but reinvested into entities with favorable tax treatments. His philanthropy, meanwhile, is structured through the Bloomberg Philanthropies trust, which allows for deductions while maintaining control over assets. What’s telling isn’t the size of his wealth but how it’s deployed for leverage. Bloomberg’s political donations—over $100 million in the 2020 election cycle—aren’t just about influence; they’re a cost of maintaining the tax and regulatory environment that protects his assets. The interplay between his media company, his data assets, and his policy work creates a feedback loop where information, capital, and power reinforce each other."Wealth isn’t just about money. It’s about the ability to rewrite the rules so that the game always favors you." — Nomi Prins, former Goldman Sachs executive
| Factor | Estimated Impact on Net Worth Growth |
|---|---|
| Private Equity Stakes | Assets grow at 15–20% annually but with illiquidity risks; tax deferrals add 2–5% effective yield. |
| Real Estate Holdings | London/NYC portfolios appreciate at 3–7% annually; depreciation write-offs reduce taxable income by 10–30%. |
| Political Lobbying | Direct impact unclear, but policies favoring capital gains tax cuts or carried interest exemptions can add 1–3% to after-tax returns. |
| Dynastic Trusts | Wealth preserved across generations with minimal estate tax exposure; growth compounds without liquidity events. |
| Media/Tech Synergies | Control over data or narrative (e.g., Bloomberg Terminal) can create monopolistic pricing power, adding 5–15% to margins. |
What This Means Going Forward
The net worth top one percent isn’t static—it’s adaptive. As governments attempt to tax wealth more aggressively (e.g., France’s 2018 wealth tax repeal or the U.S. proposed billionaire minimum tax), the ultra-rich deploy countermeasures. Offshore trusts, charitable remainder trusts, and even crypto investments (despite volatility) serve as hedges against regulation. The result is a mobility ceiling: the barriers to entry for the top one percent are rising even as their wealth grows more concentrated. The real question isn’t whether this group will shrink—it’s whether the rest of society can opt out of their economic ecosystem. When a single family controls a city’s housing stock, or a hedge fund dictates which startups get venture capital, the illusion of meritocracy fades. The net worth top one percent doesn’t just accumulate wealth; they reshape the conditions under which everyone else operates.
Conclusion
The net worth top one percent is more than a statistic—it’s a system. Understanding it requires looking past income brackets and into the architecture of advantage: how trusts bypass taxes, how private markets insulate assets, and how political power ensures the rules never change. The figures are staggering, but the mechanics are even more so. For the average earner, the path to joining this cohort is nearly impossible without inheriting it. For policymakers, the challenge isn’t just redistribution—it’s disrupting the structures that make wealth self-perpetuating. The conversation about inequality often focuses on guilt or envy, but the real story is about control. The net worth top one percent doesn’t just have money—they’ve designed the economy to ensure it stays with them.Comprehensive FAQs
Q: How is the net worth top one percent defined?
The threshold varies by country but generally sits at $10–15 million for a U.S. household. Globally, it’s adjusted for purchasing power—£8 million in the UK, €12 million in the Eurozone. The key distinction is that these figures represent accumulated assets, not annual income.
Q: Do most ultra-wealthy individuals earn their wealth, or do they inherit it?
Studies suggest 70–80% of ultra-high-net-worth individuals inherit at least part of their fortune. Even self-made billionaires often leverage family networks for initial capital. The Forbes 400 list shows that 40% of current members have at least one relative already on the list.
Q: How do trusts and offshore accounts protect wealth?
Dynastic trusts can shield assets from estate taxes for generations. Offshore accounts exploit tax treaties that allow wealth to be held in jurisdictions with lower or zero capital gains taxes. A single trust might hold real estate, stocks, and private equity—all growing tax-free until distributed.
Q: Why don’t higher taxes on the wealthy reduce inequality?
Wealth taxes face two obstacles: evasion (assets can be restructured into trusts or private companies) and liquidity (real estate and private equity can’t be easily seized). Even when taxes rise, the ultra-wealthy adjust their asset mix to minimize exposure—shifting from stocks to illiquid holdings, for example.
Q: What’s the biggest misconception about the net worth top one percent?
The myth that hard work is the primary driver. While effort matters, systemic advantages—inheritance, access to private markets, and political influence—play a far larger role. A study by the Economic Policy Institute found that 90% of wealth growth from 2009–2018 went to the top 10%, with the net worth top one percent capturing the majority.
Q: Can anyone realistically join the net worth top one percent?
Without inheritance or extreme luck (e.g., a tech IPO), the path is nearly impossible. The average time to accumulate $10 million from a median salary is over 50 years, assuming no market downturns or unexpected expenses. Most who join this cohort do so through asset concentration (real estate, private equity) or dynastic wealth transfer.
Q: How does the net worth top one percent influence policy?
Through lobbying, campaign donations, and revolving-door politics. A single billionaire’s PAC can outspend a small country’s election budget. For example, the Koch network has spent over $1 billion on U.S. elections since 2000, shaping policies on taxes, regulation, and trade—all of which directly benefit their portfolios.
Q: What would it take to reduce the net worth top one percent’s share?
Structural changes: wealth taxes on illiquid assets, closing loopholes in private equity, and breaking up monopolistic holdings. The most effective models—like Nordic countries’ high inheritance taxes—combine progressive taxation with universal social programs to redistribute both capital and opportunity.
