5 Things Worth Knowing About High Net Worth Portfolio Management in Atlanta, GA
The city’s wealth management ecosystem is shaped by five critical forces. Understanding them reveals why Atlanta’s approach to high-net-worth portfolio optimization diverges from global benchmarks—and how clients can leverage local advantages.1. The Tax Arbitrage Advantage of Georgia’s No-State-Income-Tax Policy
Georgia’s absence of state income tax creates a structural advantage for high-net-worth portfolio management in Atlanta, GA, but it’s a double-edged sword. On one hand, HNW individuals can structure portfolios to defer capital gains taxes longer than in high-tax states, often by holding appreciated assets (like real estate or private equity stakes) until federal long-term rates apply. Advisors frequently recommend tax-loss harvesting in taxable accounts while shifting growth-oriented assets into tax-advantaged vehicles—such as Georgia’s Qualified Opportunity Zone (QOZ) funds, which saw $1.2 billion in investments statewide by 2022. The catch? Atlanta’s real estate market, while resilient, lacks the liquidity of coastal cities, forcing investors to weigh illiquidity premiums against tax deferrals. The policy also attracts domestic and international capital seeking tax efficiency. A 2023 report by the Georgia Department of Revenue noted a 40% increase in out-of-state LLC formations in metro Atlanta, many tied to high-net-worth portfolio structuring for foreign clients. However, this influx has tightened competition among wealth managers, pushing firms to differentiate through niche expertise—such as cross-border estate planning for Latin American or Middle Eastern families relocating to Atlanta.2. The Rise of “Insider” Private Equity in Atlanta’s Industrial Sector
Atlanta’s economy isn’t driven by Silicon Valley IPOs or Wall Street arbitrage; it’s powered by industrial private equity. Firms like Ares Management and Carlyle Group have deep roots in the region, targeting logistics, aviation, and defense contracts. For high-net-worth portfolio managers in Atlanta, GA, this means access to non-public equity deals that align with the city’s economic engine. A 2023 PitchBook analysis found that Atlanta-based private equity funds raised $8.7 billion in 2022, with a disproportionate focus on middle-market deals—often too large for angel investors but too niche for institutional funds. The challenge? These assets are illiquid by design. Wealth managers mitigate risk by diversifying across secondary private equity funds (which buy existing stakes) and direct investments in operating companies, such as a $500 million stake in a Georgia-based aerospace supplier. The payoff? Historically, Atlanta’s industrial PE funds have delivered 12–18% annualized returns, outpacing public market benchmarks during inflationary periods. But the trade-off is lock-up periods of 5–7 years, requiring HNW clients to balance liquidity needs with long-term growth.3. Real Estate as Both Anchor and Albatross
No discussion of Atlanta’s high-net-worth investment strategies is complete without addressing real estate—a sector that has simultaneously created and complicated portfolios for the city’s elite. Atlanta’s housing market, once a bargain, now faces supply constraints and rising interest rates, forcing advisors to rethink traditional buy-and-hold models. Luxury home prices in Buckhead and Midtown have surged 15–20% annually since 2020, but appreciation isn’t uniform: commercial real estate (CRE) remains a wild card. Office vacancies in downtown Atlanta hit 25% in early 2024, pressuring landlords and forcing HNW investors to adopt value-add strategies—such as adaptive reuse of Class B office buildings into mixed-use developments. Wealth managers are pivoting toward opportunistic real estate funds that exploit Atlanta’s unique opportunities: - Fractional ownership in high-end rental portfolios (e.g., a $20 million fund pooling 10 luxury condos). - Short-term rental arbitrage in tourist-heavy zones like the Georgia Aquarium district. - Land banking in suburban growth corridors (e.g., Gwinnett County, where population density is rising faster than infrastructure). The risk? Atlanta’s market is less liquid than Miami or NYC, and distressed sales can drag down portfolios. Top advisors now include CRE vetting teams to assess tenant quality and zoning risks—a far cry from the days when raw appreciation drove decisions.“Atlanta’s real estate isn’t just about price appreciation anymore. It’s about resilience. A client holding a 20-unit apartment complex in East Atlanta Village in 2015 might have seen 12% annual gains—until the pandemic hit. Now, we’re structuring deals where cash flow matters more than cap rates.” — James Carter, Managing Director, Carter Wealth Advisors (Atlanta)
4. The Philanthropy Premium: How Atlanta’s HNW Clients Blend Wealth and Legacy
Philanthropy isn’t an afterthought in Atlanta’s high-net-worth portfolio management—it’s a core allocation strategy. The city’s donor-advised funds (DAFs) and private foundations are among the most active in the U.S., with the Atlanta Community Foundation managing $1.5 billion in assets as of 2023. For HNW individuals, charitable giving isn’t just tax-efficient; it’s a portfolio diversifier. Advisors increasingly recommend program-related investments (PRIs), where clients deploy capital to mission-driven ventures (e.g., affordable housing developers) with the expectation of partial repayment—effectively earning 5–8% risk-adjusted returns while supporting local causes. The trend extends to impact investing, where Atlanta’s HNW population is over-indexed in: - Social impact bonds (e.g., Atlanta Public Schools’ literacy programs). - Green bonds tied to the BeltLine’s expansion. - Historically Black college and university (HBCU) endowments, which have seen 300%+ growth in donor commitments since 2020. The result? A symbiotic relationship between wealth growth and community development. Wealth managers now include philanthropy specialists on their teams, structuring gifts to maximize both tax benefits and portfolio liquidity—such as donating appreciated stock to a DAF instead of selling.5. The Advisor Consolidation Challenge
Atlanta’s high-net-worth wealth management sector is undergoing a quiet consolidation, with larger firms absorbing boutique practices to handle the $500 billion+ in assets under management in metro Atlanta. The shift reflects two realities: 1. Scale matters for alternatives. HNW clients increasingly demand access to private credit, hedge funds, and distressed assets—opportunities that require institutional-level deal flow. 2. Succession planning is critical. Many Atlanta-based advisors are nearing retirement, and their clients (often second-generation wealth holders) prefer working with firms that can scale with their needs. The consolidation has created a two-tiered advisor market: - Boutique firms (e.g., Harrison & Shriver, The Private Bank) cater to clients with $10M–$50M in assets, offering hyper-personalized service and deep local industry knowledge. - National platforms (e.g., UBS, Morgan Stanley, and regional banks like Truist) target $50M+ portfolios, leveraging global investment teams but often at the cost of Atlanta-specific expertise. The trade-off? Clients with $20M–$100M in assets are caught in the middle, facing higher fees as boutiques struggle to compete with institutional resources. Top advisors are responding by bundling services—offering family office-like concierge support (e.g., private jet fractional ownership, concierge medical services) to justify premium fee structures.
How These Facts Connect
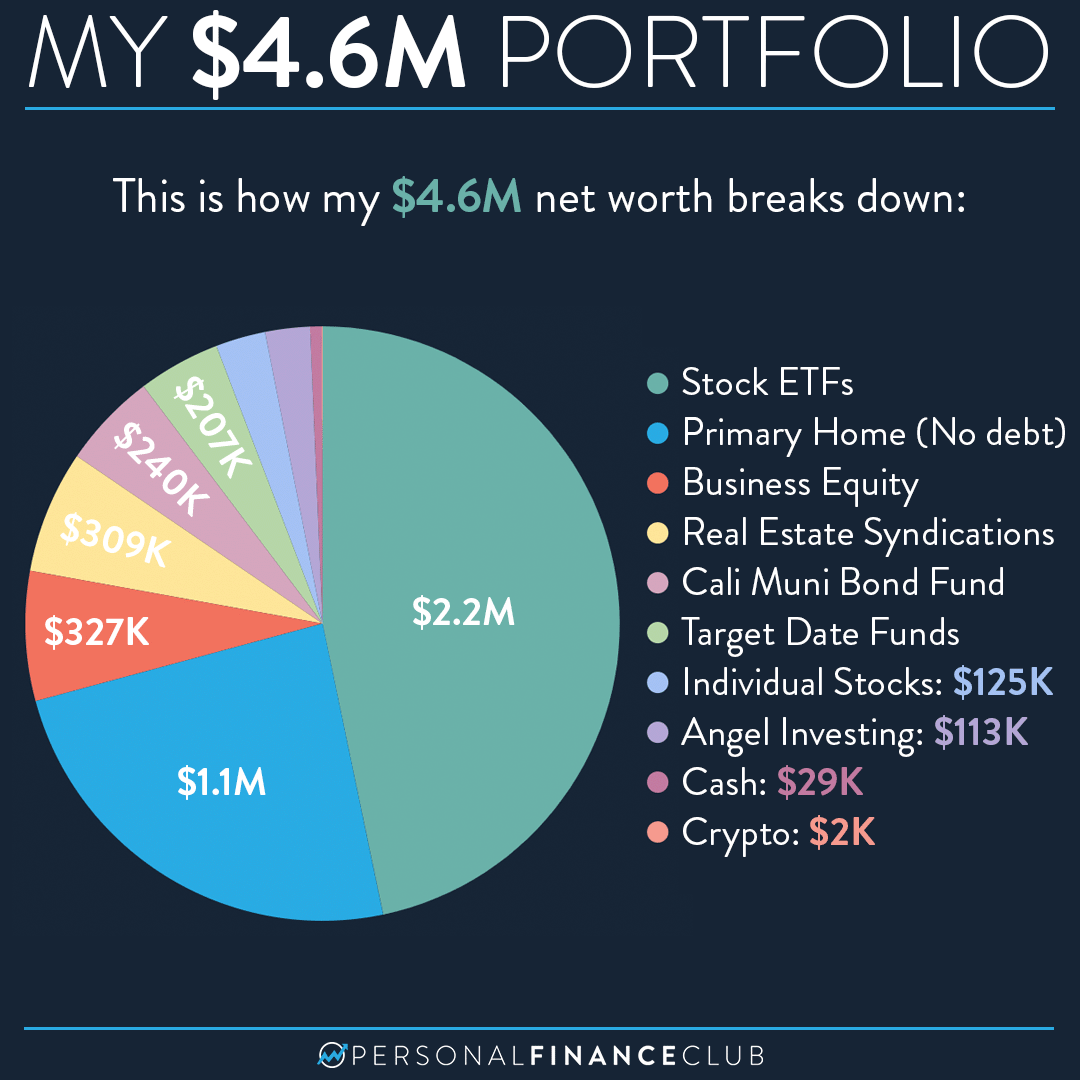
Atlanta’s high-net-worth portfolio management ecosystem is defined by three interconnected tensions: 1. Liquidity vs. Opportunity. The city’s lack of coastal liquidity forces investors to accept illiquidity in exchange for higher-risk, higher-reward assets (private equity, real estate). But as the market matures, secondary markets for these assets are expanding, reducing the trade-off. 2. Tax Efficiency vs. Economic Exposure. Georgia’s no-income-tax policy is a wealth magnet, but it also concentrates risk in sectors like aviation and logistics—exposures that can backfire if global supply chains shift. 3. Legacy vs. Growth. Atlanta’s HNW clients prioritize philanthropy and family wealth transfer, which often means lower portfolio turnover and a focus on absolute returns over benchmark beating. The result is a portfolio construction philosophy that looks like this: - Core holdings: Public equities (30–40%), with an overweight in Atlanta-based industrials (Delta, Home Depot, Coca-Cola). - Alternative sleeve: Private equity (20–30%), real estate (15–20%), and illiquid strategies (10%). - Philanthropic allocation: 5–10% of liquid assets, structured for tax and impact synergies. - Cash/reserve: 5–10%, but often earmarked for opportunistic deployments (e.g., distressed CRE). Atlanta’s HNW portfolios are no longer just about growing wealth—they’re about preserving it in a city where economic cycles move differently than the rest of the U.S.| Key Factor | Atlanta’s Unique Twist | Risk | Opportunity |
|---|---|---|---|
| Tax Policy | No state income tax → deferred capital gains | Illiquidity in holding appreciated assets | QOZ funds, cross-border structuring |
| Private Equity | Industrial/sector-specific funds dominate | 5–7 year lock-ups | 12–18% annualized returns |
| Real Estate | Supply constraints + CRE volatility | Distressed sales drag portfolios | Fractional ownership, short-term rentals |
| Philanthropy | DAFs and PRIs as portfolio diversifiers | Opportunity cost of illiquid gifts | Tax-efficient growth + impact |
Conclusion
High net worth portfolio management in Atlanta, GA isn’t about replicating strategies from Boston or Los Angeles—it’s about leveraging the city’s economic DNA. The most successful advisors don’t just allocate capital; they structure it around Atlanta’s rhythms: the ebb and flow of Delta’s stock, the resilience of its industrial base, and the cultural weight of legacy planning. As the city’s wealth base grows, the biggest challenge won’t be finding assets to invest in, but navigating the illiquidity premium that comes with Atlanta’s unique opportunities. The firms that thrive will be those that blend institutional scale with local intimacy—offering private equity access while still understanding the nuances of a $2 million Buckhead penthouse’s rental yield. For HNW clients, the message is clear: Atlanta’s wealth management playbook is no longer a side note to coastal strategies—it’s the main event.Comprehensive FAQs
Q: How do Atlanta’s wealth managers handle the city’s lack of liquidity in private assets?
Top firms mitigate illiquidity by diversifying across secondary markets (e.g., selling stakes in private equity funds before maturity) and offering bespoke liquidity solutions, such as standby letters of credit for clients who need cash but don’t want to sell assets at a discount. Some boutiques also partner with private credit funds to provide non-bank financing for portfolio needs.
Q: Are there tax advantages to holding real estate in Atlanta vs. other states?
Yes, but they’re nuanced. Georgia’s no-income-tax policy means no state capital gains tax, but federal taxes still apply. The real advantage comes from 1031 exchanges (which Atlanta’s CRE market facilitates well) and opportunity zone funds, which defer federal gains if reinvested in designated zones. However, property taxes in Atlanta are rising (averaging 1.1% of home value), which can offset some benefits.
Q: What’s the typical fee structure for high-net-worth advisors in Atlanta?
Fees vary by asset class: - AUM-based (1% for $1M–$10M, tapering to 0.5–0.8% for $100M+). - Flat fees for alternatives (e.g., $50K–$200K annually for private equity access). - Boutiques charge 1.5–2.5% on assets under $50M but offer bundled services (e.g., concierge, tax planning) to justify premiums. - National firms (UBS, Morgan Stanley) typically charge 0.8–1.2% but may waive fees if clients meet minimum thresholds (e.g., $25M+).
Q: How do Atlanta’s HNW clients protect against Delta Air Lines’ stock volatility?
Most advisors diversify Delta exposure by: - Holding no more than 5–10% of the portfolio in Delta stock. - Pairing it with hedging strategies (e.g., put options) or converting shares to restricted stock units (RSUs) for tax-efficient vesting. - Investing in Delta-related private equity (e.g., stakes in airport infrastructure firms) to benefit from dividend growth without stock price risk. Some clients also use Delta’s employee stock purchase plan (ESPP) for incremental buys during market dips.
Q: Can non-residents use Atlanta’s tax benefits for high-net-worth portfolio management?
Yes, but with strict structuring. Non-residents (especially from high-tax states or countries) can establish Georgia LLCs or trusts to defer capital gains and estate taxes. However, the IRS scrutinizes “tax inversion” schemes, so advisors typically recommend: - Donor-advised funds (DAFs) for charitable giving. - Private placement life insurance (PPLI) for offshore wealth, which grows tax-deferred. - Qualified Opportunity Zone funds (though non-residents must hold assets for 10+ years to defer gains).
Q: What’s the biggest mistake Atlanta HNW clients make with their portfolios?
Overconcentration in local assets—especially real estate and Delta stock. Many clients, lured by Atlanta’s growth, allocate 30–40% of portfolios to metro Atlanta CRE or Delta, creating unintended sector risk. Top advisors now push for geographic diversification (e.g., holding 10–15% in Texas CRE, 5–10% in Florida multifamily) to hedge against local downturns.
Q: How do Atlanta’s wealth managers handle estate planning for blended families?
Atlanta’s diverse HNW population (including many international families and second marriages) requires customized estate structures, such as: - Discretionary trusts to protect assets from remarriage or creditors. - Dynasty trusts (Georgia allows generation-skipping tax exemptions up to $12.92M per individual in 2024). - Qualified Personal Residence Trusts (QPRTs) for primary homes, which can remove property from the taxable estate while allowing the grantor to live in it. Advisors often integrate philanthropy (e.g., spendthrift trusts funding DAFs) to simplify distributions to heirs.
Q: What’s the future outlook for high-net-worth portfolio management in Atlanta?
The next decade will likely see: 1. More alternative investments (e.g., crypto custody services, private credit funds) as advisors compete for $100M+ portfolios. 2. AI-driven portfolio optimization, but with a local twist—using data on Atlanta’s job growth sectors (e.g., biotech in Midtown) to refine allocations. 3. Greater focus on cybersecurity for digital assets, as Atlanta becomes a hub for fintech and blockchain firms. 4. Succession planning crises as baby boomer advisors retire, forcing HNW clients to consolidate relationships with larger firms or family offices.
