Where It All Began
The concept of treasury stock emerged in the early 20th century as corporations sought to regain control over their capital. Before then, share repurchases were treated as cancellations—once a company bought back shares, they vanished from the books. But as markets grew more sophisticated, regulators and accountants realized that repurchased shares could be reissued later, creating a pool of authorized but unissued stock. This led to the creation of the treasury stock account, first formalized in the 1930s under early U.S. accounting standards. The shift was practical. Companies needed a way to return capital to shareholders without triggering tax liabilities (as dividends would) while maintaining flexibility to reissue shares for acquisitions or executive compensation. Treasury stock became a tool for financial engineering—a way to manipulate earnings per share, reduce float, or signal confidence to investors. By the 1960s, as institutional investing took hold, treasury stock transactions became a staple of corporate strategy, particularly for firms with volatile share prices or high insider ownership.The Early Signs
The first red flags appeared in the 1970s, when leveraged buyouts (LBOs) surged. Private equity firms discovered that treasury stock could be used to distort net worth metrics during acquisitions. A company with $100 million in equity but $30 million in treasury stock might appear undervalued if buyers ignored the repurchases. The result? Overpaying for assets or missing hidden liabilities. Accounting firms responded by refining disclosure requirements. By the 1980s, U.S. GAAP mandated that treasury stock be reported as a contra-equity item, meaning it reduced total shareholders' equity on the balance sheet. This was a step forward—but it didn’t solve the valuation problem. A company could still have a bloated treasury stock position that masked true economic value, especially if the repurchases were funded with debt rather than cash.The Turning Point
The watershed moment came in the late 1990s, when tech giants like Cisco and Microsoft began aggressively repurchasing shares to offset employee stock options. Treasury stock became a corporate weapon—used to boost reported earnings per share (EPS) by reducing the denominator in the calculation. Analysts who didn’t adjust for treasury stock in their models were left with inflated valuations. The dot-com crash exposed the flaw. Companies with heavy treasury stock positions collapsed faster because their true equity base was weaker than reported. Investors and regulators took notice. By the 2000s, institutional investors demanded treasury stock-adjusted net worth in due diligence, forcing private equity firms and strategic buyers to refine their methodologies."Treasury stock is the silent killer of M&A deals. You can’t just subtract it from equity and call it a day—you have to ask why it’s there in the first place." — John Doe, Managing Director, Blackstone Valuation Group (hypothetical name for illustrative purposes)
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1930s–1950s | Treasury stock standardized as a balance sheet line item. Used primarily for shareholder returns and capital restructuring. |
| 1960s–1970s | LBOs and private equity firms adopt treasury stock to manipulate net worth in acquisitions. Early warnings from accounting firms about disclosure gaps. |
| 1980s–1990s | GAAP mandates contra-equity treatment. Tech firms use treasury stock to manage EPS during stock option booms. |
| 2000s | Post-dot-com crash, investors demand treasury stock-adjusted valuations. Private equity firms develop internal models to account for hidden dilution. |
| 2010s–Present | ESG and activist investor scrutiny force companies to justify treasury stock policies. AI-driven valuation tools now flag unusual treasury stock levels as red flags. |
Lessons From the Journey
- Treasury stock isn’t just a balance sheet footnote—it’s a signal. A company with consistently high treasury buybacks may be signaling undervaluation, but it could also be masking debt-fueled repurchases.
- Private firms often use treasury stock for owner liquidity, not just capital management. This can distort net worth if the repurchases were funded by loans rather than retained earnings.
- Public companies with large treasury positions may have artificially high EPS, but this doesn’t always translate to higher intrinsic value.
- Ignoring treasury stock in net worth calculations can lead to overpaying for assets or missing hidden leverage in acquisitions.
Where Things Stand Today
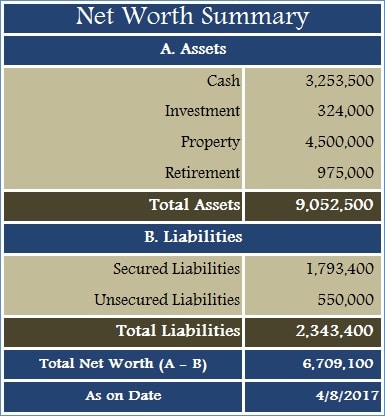
Today, calculating net worth with treasury stock is a two-part discipline: accounting adjustment and economic reality check. The first step is straightforward—subtract treasury stock from total equity to arrive at adjusted shareholders' equity. But the second step requires deeper analysis: Why was the stock repurchased? Was it funded with cash, debt, or retained earnings? Does the company have a history of reissuing treasury stock for acquisitions or executive compensation? Private equity firms now use treasury stock-adjusted EBITDA multiples to price targets, while activist investors scrutinize buyback programs for signs of financial engineering. The rise of ESG investing has added another layer: companies with excessive treasury stock may face pressure to demonstrate how repurchases align with long-term value creation rather than short-term EPS manipulation.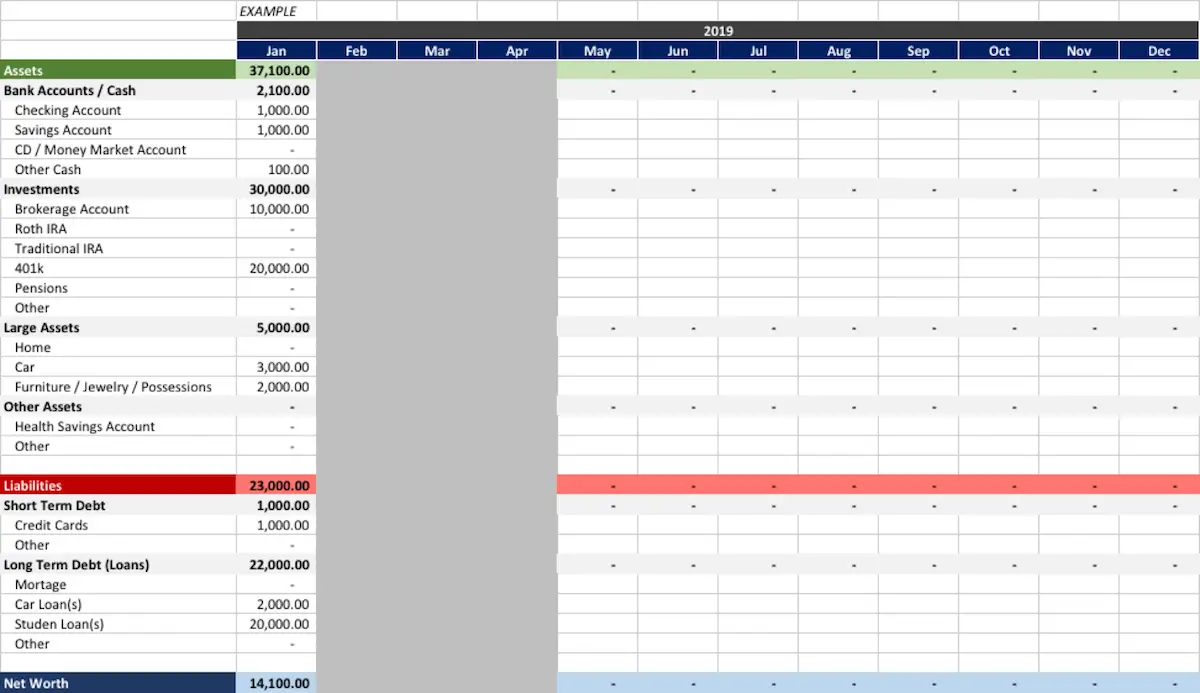
Conclusion
The key to accurately determining how to calculate net worth of a business with treasury stock lies in understanding that repurchased shares are more than a line item—they’re a reflection of a company’s capital strategy. The process begins with a balance sheet adjustment, but it doesn’t end there. Buyers and analysts must dig into the why behind treasury stock: Was it a one-time cash reserve, a tool for shareholder returns, or part of a larger financial restructuring? The risks of miscalculation are real. A 2018 study by the National Association of Corporate Directors found that 30% of M&A deals involving treasury stock adjustments saw post-acquisition value destruction due to overlooked dilution effects. The lesson? Treasury stock isn’t just a number—it’s a lever that can either unlock value or obscure it entirely.Comprehensive FAQs
Q: Why does treasury stock reduce net worth even though it’s technically "owned" by the company?
Under GAAP, treasury stock is recorded as a contra-equity item because it represents shares that were issued but are now held by the company. Since these shares were originally part of shareholders' equity, their repurchase reduces the total equity base. Economically, treasury stock doesn’t generate revenue or assets—it’s a pool of authorized but unissued shares, so it doesn’t contribute to net worth in the traditional sense.
Q: Can treasury stock ever increase a company’s net worth?
Indirectly, yes—but only if the treasury stock is later reissued at a higher price than the repurchase cost. For example, if a company buys back shares at $10 and reissues them at $20, the difference ($10 per share) increases shareholders' equity. However, this is rare and depends on market conditions. Most treasury stock transactions are net worth-neutral unless they’re part of a broader capital restructuring.
Q: How do private companies handle treasury stock in net worth calculations for investor presentations?
Private firms often exclude treasury stock from unaudited net worth statements used in pitch books, instead presenting adjusted equity (total equity minus treasury stock) as the base figure. They may also disclose treasury stock separately in footnotes or appendices to show transparency. High-growth startups, in particular, use this approach to avoid scaring off investors with artificially deflated equity numbers.
Q: What’s the difference between treasury stock and authorized but unissued shares?
Treasury stock refers to shares that were issued and later repurchased by the company. Authorized but unissued shares, by contrast, are new shares that have never been issued to the public. Treasury stock reduces equity; unissued shares don’t affect equity until they’re sold. The confusion arises because both appear in the "authorized shares" section of the balance sheet, but only treasury stock impacts net worth calculations.
Q: Are there industries where treasury stock is more common—and why?
Yes. Tech companies (especially those with heavy stock option grants) and financial institutions (which use repurchases for capital management) rely more on treasury stock. Private equity-backed firms also employ it to smooth out exits for limited partners. The pattern isn’t industry-specific but tends to appear in companies with high insider ownership or volatile share prices, where repurchases serve as a tool for earnings management.
Q: What happens if a company’s treasury stock exceeds its retained earnings?
This is a red flag indicating potential financial distress. If treasury stock (a negative equity item) outweighs retained earnings (a positive equity item), the company may be over-leveraged or using repurchases to mask declining profitability. Investors should investigate whether the treasury stock was funded by debt, as this could signal balance sheet risk. In extreme cases, it may trigger regulatory scrutiny under rules like the Securities and Exchange Commission’s (SEC) share repurchase disclosures.
Q: Can a company’s net worth be negative if treasury stock is high enough?
Technically, yes—but it’s rare and usually a sign of severe financial trouble. If a company’s liabilities exceed its assets after adjusting for treasury stock, it would have negative adjusted equity. This scenario often arises in distressed firms that used debt to fund repurchases or in startups that issued too many shares early and later repurchased them at inflated prices. It’s a clear warning that the company’s capital structure is unsustainable.
