
The Complete Overview of US Population by Net Worth
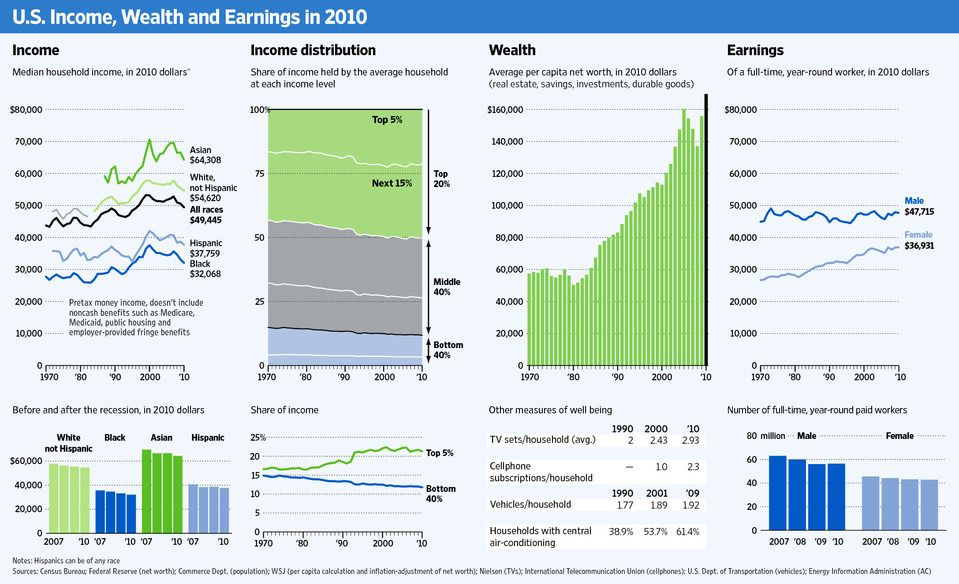
The US population by net worth paints a picture of a country where wealth accumulation has become increasingly concentrated at the top. According to Federal Reserve data, the top 10% of households hold roughly 70% of all liquid assets, while the bottom 50% collectively own less than 2.5%. This isn’t just about income—it’s about intergenerational wealth transfer, real estate ownership, and the compounding power of investments that most Americans never access. The pandemic accelerated these trends: stock market surges lifted the net worth of the wealthiest households by $5.8 trillion in 2021 alone, while nearly 40% of Americans reported they couldn’t cover a $400 emergency expense. What’s less discussed is how net worth disparities correlate with life expectancy, education outcomes, and even political engagement. A 2023 Brookings Institution study found that counties where the median net worth is below $50,000 see higher rates of chronic illness, lower college enrollment, and greater reliance on payday lenders. Meanwhile, in affluent suburbs, home equity alone can fund a child’s private school tuition or early retirement. The US population by net worth isn’t just a financial snapshot—it’s a predictor of social mobility, or the lack thereof.Historical Background and Evolution
The modern wealth distribution in the US traces back to the post-WWII era, when policies like the GI Bill and progressive taxation temporarily narrowed the gap. By the 1980s, however, deregulation, tax cuts for the wealthy, and the rise of financialization reversed that trend. The US population by net worth in 1989 was far more balanced: the top 1% held about 12% of wealth, compared to nearly 30% today. The 2008 financial crisis temporarily disrupted this trajectory—net worth for the bottom 90% dropped by $11 trillion—but the recovery favored asset owners, particularly those with stock portfolios and real estate. The digital economy has deepened these divides. Tech billionaires like Jeff Bezos and Mark Zuckerberg didn’t just accumulate wealth—they reinvented wealth creation. Their companies’ valuations soared while traditional wage growth stagnated. The US population by net worth now includes a new tier: the "liquid wealth elite," whose fortunes are tied to public markets rather than physical assets. Meanwhile, the median net worth—a more reliable measure of typical Americans—has grown at a snail’s pace, stuck at around $180,000 for decades, adjusted for inflation.Core Mechanisms: How It Works
The US population by net worth isn’t shaped by luck alone—it’s the result of structural advantages. Homeownership, for instance, remains the single largest driver of wealth accumulation. A family that inherits a home or buys at the right time can see equity grow exponentially, while renters build no such asset. Tax policies further tilt the scale: capital gains are taxed at lower rates than wages, and estate taxes exempt the first $13.6 million per individual. These mechanisms ensure that wealth begets more wealth, while labor alone rarely breaks the cycle. Education plays a critical but often misunderstood role. A college degree isn’t just a credential—it’s a wealth multiplier. The US population by net worth data shows that households headed by someone with a bachelor’s degree have nearly 5x the median net worth of those without one. But here’s the catch: student debt has become a wealth drain for younger generations. The average Class of 2023 graduate faces $38,000 in loans, money that could otherwise go toward home purchases or investments. The system rewards the educated—but only if they can afford the education in the first place.Key Benefits and Crucial Impact
The US population by net worth isn’t just a cold ledger—it’s a reflection of opportunity. For the top decile, high net worth unlocks political influence, elite education for children, and access to healthcare that most Americans can’t afford. But the benefits aren’t just concentrated at the top. A stable middle class, with its modest but secure net worth, drives consumer spending that fuels the economy. When the median net worth rises, so does small-business formation and homeownership rates. The problem? That median has been stagnant for years, while the ultra-wealthy see their fortunes grow by $2,000 per second. The wealth gap’s most insidious effect may be its self-perpetuating nature. Children born into families with net worth above $1 million are 100 times more likely to remain wealthy than those born into the bottom 20%. This isn’t just about money—it’s about social capital. Wealthy parents can afford private schools, mentorship networks, and unpaid internships that give their children an edge. Meanwhile, low-income families often lack the liquid assets to absorb shocks like medical bills or job loss, trapping them in cycles of debt."Wealth isn’t just money—it’s power. And in America, power is increasingly concentrated in the hands of those who already have it." — Raghuram Rajan, Former Chief Economist, IMF
Major Advantages
- Economic stability: Households with net worth above $100,000 are three times less likely to experience food insecurity during downturns.
- Intergenerational mobility: Families with $50,000+ in net worth can fund college educations without crippling debt.
- Political leverage: The top 1% contribute 80% of political donations, shaping policies that preserve their wealth.
- Health outcomes: Counties with higher median net worth see lower infant mortality rates and longer life expectancies.
- Housing security: Homeownership rates exceed 80% for families with net worth over $500,000, compared to 40% for the bottom quintile.
- Investment access: High-net-worth individuals can diversify into private equity, venture capital, and real estate—assets closed to most Americans.
Comparative Analysis
| Metric | Top 10% of US Population by Net Worth | Bottom 50% of US Population by Net Worth |
|---|---|---|
| Median Net Worth (2023) | $2.2 million | $16,500 |
| Primary Wealth Driver | Stocks, real estate, business ownership | Wages, government assistance, minimal assets |
| Homeownership Rate | 90% | 45% |
Future Trends and Innovations
The US population by net worth is poised for further polarization unless structural changes occur. Artificial intelligence and automation will likely increase wage stagnation while boosting returns for capital owners. If current trends continue, the top 1% could hold 40% of all wealth by 2030, according to economists at the Levy Institute. On the other hand, policies like wealth taxes, expanded child tax credits, and student debt relief could narrow the gap—but political will remains the biggest hurdle. Emerging asset classes—like cryptocurrency and NFTs—may create new wealth tiers, but they also risk deepening inequality. The average Bitcoin holder’s net worth is $100,000+, while most Americans can’t afford even a fraction of a Bitcoin. The future of US wealth distribution may hinge on whether society embraces policies that democratize asset ownership or doubles down on the current system, where wealth begets wealth.Conclusion
The US population by net worth is more than a statistical footnote—it’s the story of America’s economic soul. The data reveals a country where opportunity is heavily weighted toward those who already have advantages, while the rest struggle to keep up. Closing this gap won’t happen overnight, but ignoring it ensures the divide will only widen. The question isn’t whether the wealth distribution in America will change—it’s whether the next generation will have the tools to rewrite the rules. For now, the numbers tell a clear tale: wealth is power, and power is concentrated. The challenge is whether society will choose to redistribute it—or let the cycle continue.Comprehensive FAQs
Q: What’s the difference between median and mean net worth in the US?
The median net worth (around $180,000) represents the midpoint—half of Americans have more, half have less. The mean net worth (over $1.1 million) is skewed by billionaires, making it far higher. This gap highlights how wealth concentration distorts perceptions of typical Americans’ financial health.
Q: How does race factor into the US population by net worth?
White households have a median net worth 10 times higher than Black households and 8 times higher than Hispanic households. This disparity stems from historical redlining, wage gaps, and wealth-building barriers like homeownership access. Even when controlling for income, racial wealth gaps persist.
Q: Can student debt really prevent wealth accumulation?
Absolutely. The average borrower takes 15–20 years to repay student loans, delaying home purchases, investments, and emergency savings. A 2022 Federal Reserve study found that student debt reduces net worth by 10–15% for those with bachelor’s degrees compared to non-borrowers.
Q: Are there any policies that could improve US wealth distribution?
Yes, but they’re politically contentious. Baby bonds (government-funded accounts for children), wealth taxes, and expanded public education have been proposed. Even small tweaks—like indexing capital gains taxes to inflation—could reduce inequality without drastic overhauls.
Q: How does the US compare to other developed nations in wealth inequality?
The US has the highest wealth inequality among OECD countries, with the top 10% holding 57% of total wealth—far above Germany’s 43% or Japan’s 53%. Nordic nations mitigate this through strong social safety nets, progressive taxation, and universal healthcare, which reduce the need for private wealth accumulation.
