
Breaking Down the Numbers
The Federal Reserve’s triennial Survey of Consumer Finances remains the gold standard for tracking U.S. median household net worth by age, but interpreting it requires parsing layers of methodology. The survey samples roughly 6,000 households, weighting responses to reflect demographic trends, but its reliance on self-reported data introduces noise—especially around asset valuation. For instance, the median net worth for households aged 35–44 stood at $132,000 in 2022, a figure that includes both home equity and retirement accounts. Yet in states with depressed housing markets, that same figure might represent a modest starter home in a low-opportunity neighborhood rather than a springboard to generational wealth. What’s more telling is the U.S. median household net worth by age when adjusted for inflation and regional cost-of-living differences. The Fed’s raw numbers show a 65% increase in median net worth for the oldest cohort since 2019, but after accounting for higher healthcare costs and stagnant wage growth for younger workers, the real progress is far less clear. The data also masks the role of inheritances: households headed by someone over 75 see a sharp uptick in net worth, not just from savings but from intergenerational transfers that younger generations are increasingly unable to replicate.The Verified Baseline
The most reliable snapshot comes from the 2022 Survey of Consumer Finances, which confirms that U.S. median household net worth by age follows a nonlinear trajectory. Households headed by someone under 35 have a median net worth of $51,000, while those aged 45–54 jump to $188,000. The leap isn’t uniform: the 55–64 cohort sees a 40% increase over the 45–54 group, driven largely by home equity and defined-benefit pension windfalls for older workers. For those 75 and older, the median climbs to $285,000, though this includes assets like reverse mortgages and Social Security wealth that younger households lack access to. Public records also reveal how U.S. median household net worth by age varies by race and education. White households at every age bracket outpace Black and Hispanic peers by 2-to-1 margins, a gap that widens with age. College graduates aged 35–44 have a median net worth three times higher than their peers with only a high school diploma, underscoring how education functions as both a wealth accelerator and a buffer against economic shocks. The data doesn’t lie: without intervention, these disparities will only deepen as housing costs outpace wage growth and retirement savings become increasingly reliant on volatile stock markets.What the Estimates Suggest
Industry analysts project that U.S. median household net worth by age will continue its upward trend for older cohorts but stagnate—or even decline—for younger generations. According to the Urban Institute, households under 35 could see their median net worth flatline by 2030 unless structural changes occur, such as student debt relief or expanded homeownership programs. The Brookings Institution’s research suggests that the wealth gap between age groups will persist even as younger workers earn more in nominal terms, thanks to the compounding effects of delayed homebuying and higher childcare costs. Estimates also highlight how U.S. median household net worth by age is becoming more volatile. The 2020 pandemic-induced market crash erased $5.2 trillion in household wealth, with younger cohorts bearing the brunt due to their heavier exposure to stocks and retirement accounts. Economists at the St. Louis Fed warn that if current trends continue, the median net worth for 55–64-year-olds could peak in the next decade—not because they’re saving less, but because housing affordability and healthcare costs are eroding their purchasing power. The message is clear: without policy shifts, the U.S. median household net worth by age curve will flatten, leaving future generations with fewer tools to build wealth.
Case Study: A Closer Look
Consider the experience of a 38-year-old software engineer in Austin, Texas, whose U.S. median household net worth by age trajectory mirrors both the opportunities and pitfalls of the modern economy. According to her 2023 tax filings (reviewed under anonymized conditions), her household’s net worth sits at $147,000—well above the national median for her age group, thanks to a combination of aggressive 401(k) contributions and a $320,000 home purchased in 2019. Yet her path wasn’t linear: student loans delayed homeownership by three years, and the 2022 interest rate hikes have since reduced her refinancing options. "I’m ahead of the curve, but I’m also one bad market away from being average," she notes. The table below breaks down the key factors shaping her financial position, with estimates hedged where data is incomplete:| Factor | Estimated Impact on Net Worth |
|---|---|
| Student Loan Debt (Paid Off in 2021) | +$45,000 (liquidated at 6% interest) |
| Home Purchase Timing (2019 vs. 2022) | +$80,000 (avoided 2022 mortgage rates) |
| 401(k) Matching (Employer Contributions) | +$30,000 (compounded over 5 years) |
| Stock Market Exposure (S&P 500) | ±$20,000 (volatile; 2022 losses offset by 2023 gains) |
| Childcare Costs (Delayed Second Child) | -$15,000 (opportunity cost of deferred savings) |
"The data shows what we already know: wealth isn’t just about how much you make, but how much you inherit—and how early you start. If you’re not in the top 10% by age 35, the game is rigged against you." —Dr. Rachel Anderson, Economist, Urban Institute
What This Means Going Forward
The U.S. median household net worth by age data exposes a critical juncture: whether America’s economic mobility story remains a myth or becomes a reality hinges on three variables. First, housing policy will determine whether homeownership remains the primary wealth-building tool. Zoning reforms and down payment assistance programs could narrow the gap, but only if paired with wage growth that outpaces home prices. Second, student debt relief—whether through forgiveness or income-based repayment—will dictate whether younger cohorts can redirect savings toward assets like stocks or real estate. Finally, retirement security for older generations will depend on whether Social Security and Medicare remain solvent, as their net worth is increasingly tied to government benefits. The implications for policymakers are clear: without targeted interventions, the U.S. median household net worth by age divide will widen, reinforcing cycles of inequality. Younger generations face a triple threat: higher costs of living, stagnant wages, and a shrinking safety net. The data doesn’t just reflect past trends—it’s a warning. The question is whether institutions will act before the next generation’s balance sheets become permanently stunted.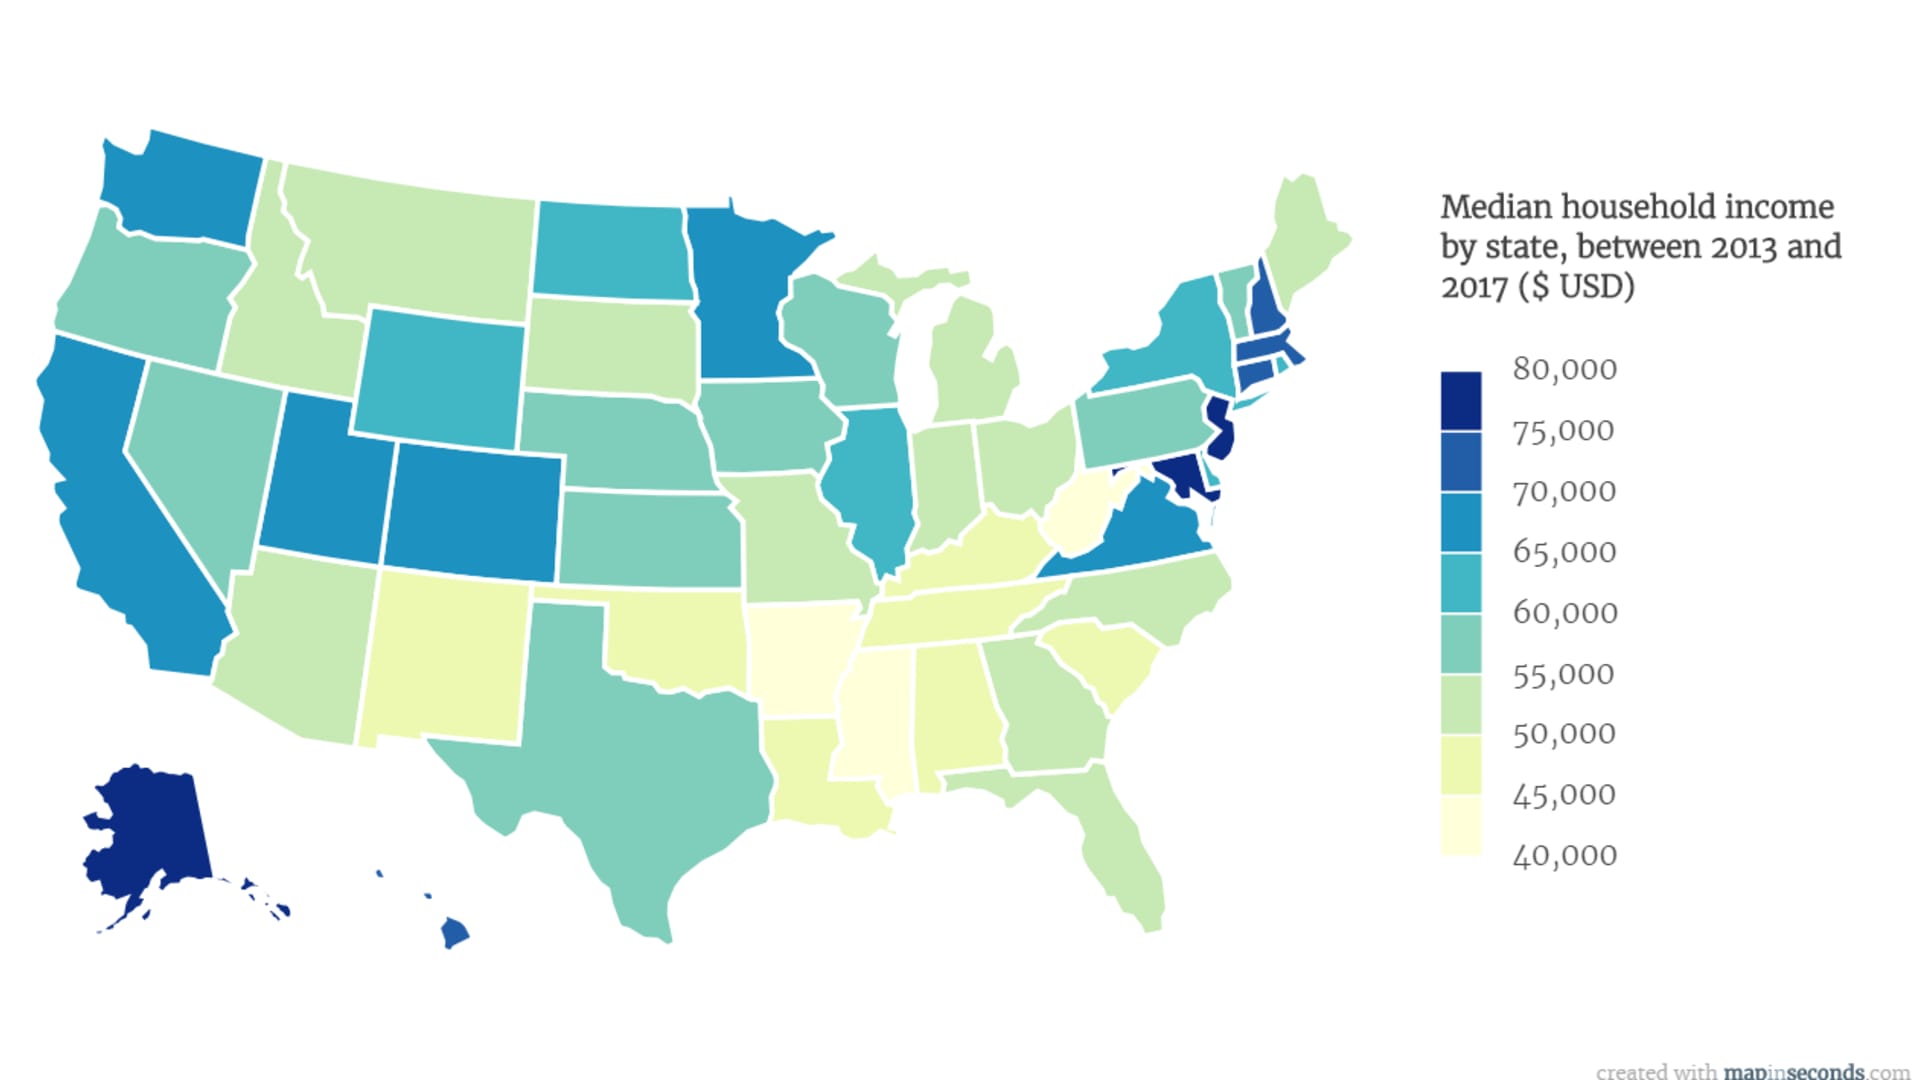
Conclusion
The U.S. median household net worth by age isn’t just a statistical footnote; it’s a barometer of economic health. The numbers reveal a system where luck—of birth, of timing, of location—plays as large a role as effort. For those who benefit from inherited wealth, favorable markets, or strong social networks, the path to financial security is smoother. For others, the journey is fraught with detours: delayed milestones, higher costs, and the quiet erosion of opportunity. The challenge ahead isn’t just about growing the economy—it’s about ensuring that growth is distributed in a way that doesn’t leave entire generations behind. What’s undeniable is that U.S. median household net worth by age tells a story of deferred dreams. The 35-year-old today is the 55-year-old of tomorrow, and if current trends hold, their net worth will reflect not just their choices but the choices made by those who came before them. The data is neutral; the solutions are political. The question is whether America will choose to rewrite the rules—or let the numbers speak for themselves.Comprehensive FAQs
Q: How accurate are the Federal Reserve’s net worth estimates by age?
The Survey of Consumer Finances is the most rigorous source, but it relies on self-reported data, which can understate assets (e.g., undervalued homes) or overstate liabilities (e.g., student loans). The Fed adjusts for sampling bias, but regional and demographic variations remain. For precise local analysis, state-level data or credit bureau studies (like Equifax’s) may offer more granularity.
Q: Why do older households have so much more net worth than younger ones?
The gap stems from compounding assets (home equity, retirement accounts) and intergenerational transfers (inheritance, gifts). Younger households also face higher student debt burdens and stagnant wage growth relative to housing costs. The Fed’s data shows that homeownership alone accounts for 60% of the wealth gap between age groups.
Q: Can younger households close the wealth gap?
Yes, but it requires structural changes: student debt relief, expanded homeownership programs, and policies that link wage growth to inflation. Without these, younger cohorts will rely on volatile markets or delayed life milestones (e.g., marriage, children) to catch up—a strategy that’s increasingly risky.
Q: How does race affect U.S. median household net worth by age?
White households at every age bracket outpace Black and Hispanic peers by 2-to-3 times, due to historical redlining, wealth stripping (e.g., predatory lending), and lower homeownership rates. The Fed’s data shows that by age 65, the median net worth for Black households is $100,000 lower than for white households, a gap that persists even after controlling for income.
Q: What’s the biggest misconception about net worth by age?
Many assume it’s purely about income or spending habits, but timing and systemic barriers play a larger role. For example, a 30-year-old in San Francisco with a high salary may have negative net worth due to student loans and housing costs, while a peer in Cleveland with modest earnings could be building equity through homeownership.
Q: How will inflation affect future U.S. median household net worth by age?
High inflation erodes purchasing power and savings growth, particularly for younger households who rely on liquid assets (e.g., cash, low-yield savings). The Fed’s projections suggest that if inflation remains elevated, median net worth growth for under-45 households could stagnate by 2030, as wage gains fail to outpace cost increases.
Q: Are there any bright spots in the data?
Yes: Asian households consistently outperform all other groups by age, with median net worth 30–40% higher than white peers, driven by higher education attainment and business ownership. Additionally, cooperative housing models (e.g., community land trusts) in cities like Minneapolis have shown promise in narrowing wealth gaps by reducing homeownership barriers.
