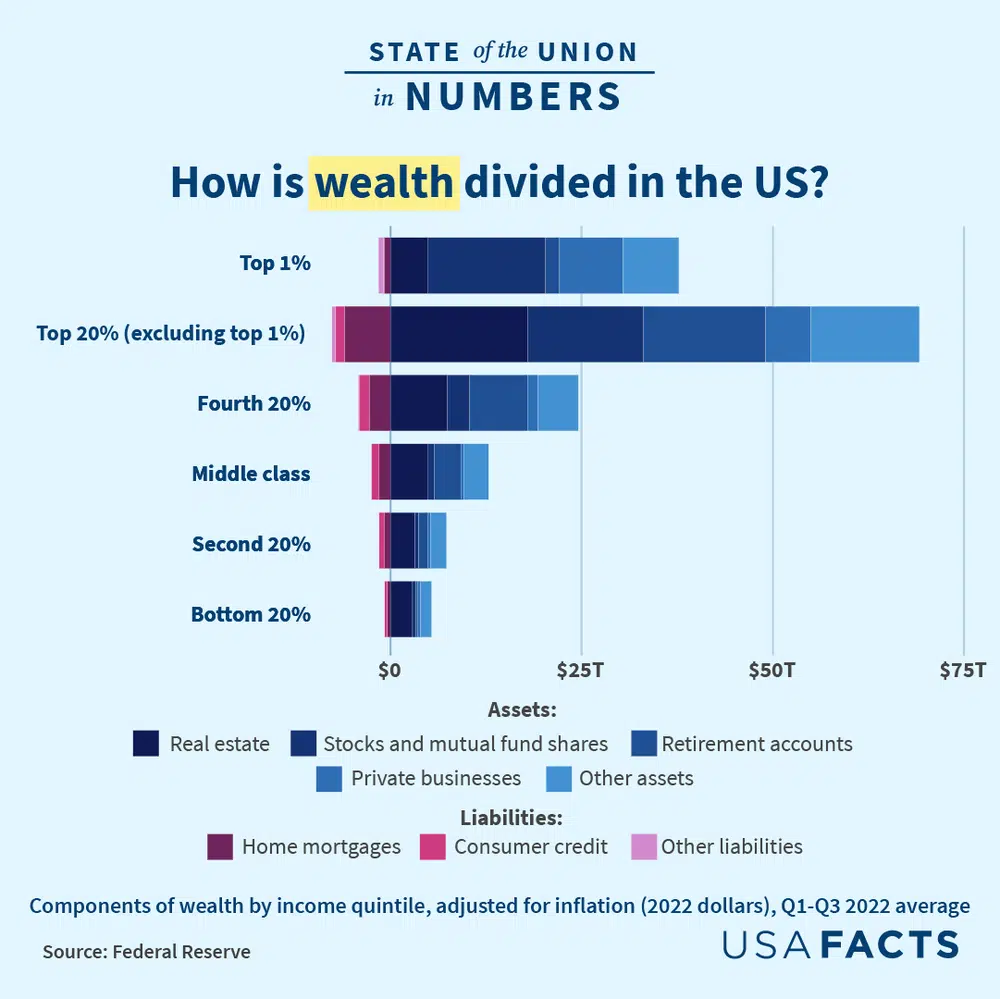
The Complete Overview of US Wealth Percentiles
The US wealth percentiles system is built on two pillars: net worth (assets minus liabilities) and liquidity (how easily that wealth can be converted to cash). The Federal Reserve’s Survey of Consumer Finances, conducted every three years, slices households into deciles (10ths) and quintiles (20ths), but the real drama unfolds in the top 1%. Here, wealth isn’t just about salary—it’s about generational capital, real estate holdings in prime markets, and ownership stakes in businesses that most Americans can’t even access. The 90th percentile might own a modest portfolio of index funds; the 99th? Private jets, vineyard investments, and trusts that shield assets from estate taxes. What makes US wealth percentiles so revealing is how they correlate with economic mobility. A child born into the bottom 20% has roughly a 7% chance of reaching the top 20% by age 30. For those in the top 1%, the odds of staying there—or ascending further—are nearly 100%. The system isn’t just tilted; it’s engineered to favor those who already have the keys. And those keys? They’re often passed down, not earned.Historical Background and Evolution
The modern framework for tracking US wealth percentiles emerged in the 1980s, as economists like Edward Wolff began quantifying the shift from wage-based prosperity to asset-based inequality. Before then, wealth was somewhat fluid—post-WWII policies like the GI Bill and strong labor unions helped distribute opportunity more evenly. But by the 1990s, deregulation, the rise of financialization, and the hollowing out of manufacturing jobs tilted the scales. The wealth gap between percentiles began to resemble the Gilded Age, when robber barons like Rockefeller and Carnegie controlled vast empires while the working class struggled to afford basic necessities. The 2008 financial crisis didn’t just expose inequality—it supercharged it. While the bottom 90% lost $11 trillion in net worth during the crash, the top 1% saw their wealth grow by $1.6 trillion in the following year alone. The recovery that followed wasn’t a rebound for most Americans; it was a wealth transfer from Main Street to Wall Street. Today, the US wealth percentiles tell a story of two economies: one where debt is a tool for mobility, and another where debt is a strategic asset—used to acquire more assets, often at a fraction of their market value.Core Mechanisms: How It Works
At its core, the US wealth percentiles system operates on three levers: tax policy, asset ownership, and inheritance. The top 1% pay lower effective tax rates than middle-class households, thanks to deductions, carried-interest loopholes, and the ability to defer capital gains. Meanwhile, the bottom 50%—who own less than 3% of all wealth—pay the most in payroll taxes, which fund programs they often can’t access. Asset ownership compounds the divide: the top 10% own 90% of all stocks and mutual funds, while the bottom 50% own just 0.5%. Inheritance seals the deal—70% of wealth transfers happen through bequests, not merit. The wealth percentile you’re born into isn’t just about money; it’s about opportunity. A family in the 99th percentile can afford to send their child to a private school with a $50,000 annual tuition, where connections to Silicon Valley VCs or Wall Street recruiters are almost guaranteed. A family in the 20th percentile might struggle to afford community college, let alone the unpaid internships that now serve as rungs on the corporate ladder. The US wealth percentiles don’t just reflect inequality—they create it, generation after generation.Key Benefits and Crucial Impact
For those at the top, the advantages of high US wealth percentiles are self-reinforcing. Access to capital means better education, which leads to higher-paying jobs, which then allow for more investments—creating a feedback loop that’s nearly impossible to break. The bottom 40%? They’re stuck in a cycle of liquidity constraints, where every financial setback—medical debt, a car repair, a layoff—can spiral into insolvency. The wealth gap between percentiles isn’t just about money; it’s about agency. The rich don’t just have more; they have more options. Politically, the US wealth percentiles system ensures that policy favors those who benefit from it. Lobbying power correlates directly with wealth—80% of federal lobbyists represent corporations or the ultra-wealthy. When tax reforms are debated, it’s the top 1% who shape the outcome, not the 99%. The wealth percentile you’re in determines whether you’re a stakeholder in the economy or just a taxpayer."Wealth inequality is the mother of all political distortions. It doesn’t just skew policy—it skews democracy itself." — Thomas Piketty, Capital in the Twenty-First Century
Major Advantages
- Asset appreciation: The top 10% own 93% of all real estate outside primary residences, meaning their wealth grows passively through rental income and property value inflation.
- Tax optimization: High-wealth individuals use trusts, offshore accounts, and charitable deductions to reduce their tax burden by 20-40% compared to middle-class filers.
- Leverage access: Banks extend preferential loan terms to the wealthy—lower interest rates, higher credit limits—allowing them to acquire more assets with borrowed money.
- Human capital multiplier: Elite education and networks provide unpaid internships, mentorship, and industry connections that middle-class families can’t replicate.
- Political influence: The top 0.1% donate $1 billion annually to campaigns, ensuring policies that protect their interests—from carried-interest tax breaks to deregulation.
- Generational wealth transfer: 70% of intergenerational wealth transfers go to the top 10%, locking in privilege across generations.

Comparative Analysis
| Metric | Bottom 50% (US Wealth Percentiles) | Top 10% | Top 1% |
|---|---|---|---|
| Median Net Worth | $6,720 (2022 Fed data) | $688,300 | $17.2 million |
| Homeownership Rate | 50% | 80% | 95%+ (often multiple properties) |
| Stock Ownership | 5% | 70% | 90%+ (including private equity) |
| Effective Tax Rate | 20-30% | 15-20% | 10-15% (after deductions) |
Future Trends and Innovations
The US wealth percentiles divide is likely to deepen as automation and AI reshape the labor market. Middle-skill jobs—once the backbone of the middle class—are being replaced by low-wage gig work and high-skill tech roles, widening the gap further. Meanwhile, the ultra-wealthy are betting big on private credit, venture capital, and alternative assets like fine art and cryptocurrency, which offer tax advantages and liquidity flexibility beyond traditional markets. Policy changes could either exacerbate or mitigate the trend. A wealth tax—proposed by figures like Elizabeth Warren—could recalibrate the US wealth percentiles, but political resistance from the top 1% makes it unlikely in the near term. Alternatively, universal basic assets (not just income) could provide a floor for the bottom 50%, but without structural reforms to inheritance, education, and tax policy, the system will continue to favor those who already hold the keys.
Conclusion
The US wealth percentiles aren’t just numbers—they’re a report card on American capitalism. They show a system where opportunity is not just unequal but engineered to favor the few. The data doesn’t lie: the top 1% have more wealth than the bottom 90% combined, and that gap is growing. The question isn’t whether this is fair—it’s whether it’s sustainable. History suggests that societies with this level of inequality either collapse or reform. The choice is ours. But change won’t come from within the system. It requires political will, structural reforms, and a reckoning with the myth of meritocracy. Until then, the US wealth percentiles will keep climbing—not because of what people earn, but because of what they inherit.Comprehensive FAQs
Q: How are US wealth percentiles calculated?
The Federal Reserve’s Survey of Consumer Finances ranks households by net worth (assets minus debts) and divides them into deciles (10ths) and quintiles (20ths). The top 1% is defined as those with net worth exceeding $17.2 million (2022 data), though this threshold adjusts with inflation.
Q: What’s the difference between wealth and income percentiles?
Income percentiles measure annual earnings, while wealth percentiles account for assets (home, stocks, business ownership) minus liabilities (mortgages, debt). Wealth is stickier—it compounds over generations—whereas income can fluctuate yearly.
Q: Do US wealth percentiles vary by race or ethnicity?
Yes. The median white household holds $188,200 in wealth, while Black households have just $24,100 and Hispanic households $36,400 (2022 Fed data). This gap is driven by historical redlining, wage disparities, and inheritance patterns.
Q: Can someone move up or down the US wealth percentiles?
Movement is possible but extremely rare. The bottom 50% has a 7% chance of reaching the top 20% by age 30, while the top 1% has a near-guaranteed chance of staying there—or ascending further—due to inheritance, education, and network effects.
Q: How do taxes affect US wealth percentiles?
The top 1% pay lower effective tax rates (10-15%) than middle-class households (20-30%) due to capital gains exemptions, deductions, and carried-interest rules. Meanwhile, the bottom 40% pay the most in payroll taxes, which fund programs they often can’t access.
Q: Are there countries with more equal wealth percentiles?
Yes. Nordic countries (Denmark, Sweden) have lower wealth inequality due to progressive taxation, strong labor unions, and universal healthcare. The U.S. ranks among the most unequal in the developed world, alongside Chile and Mexico.
Q: What’s the biggest misconception about US wealth percentiles?
Many assume wealth inequality is just about income. In reality, it’s about asset ownership, inheritance, and systemic barriers—like zoning laws that inflate housing costs or private school networks that open doors. The system isn’t just unfair; it’s designed to perpetuate itself.
