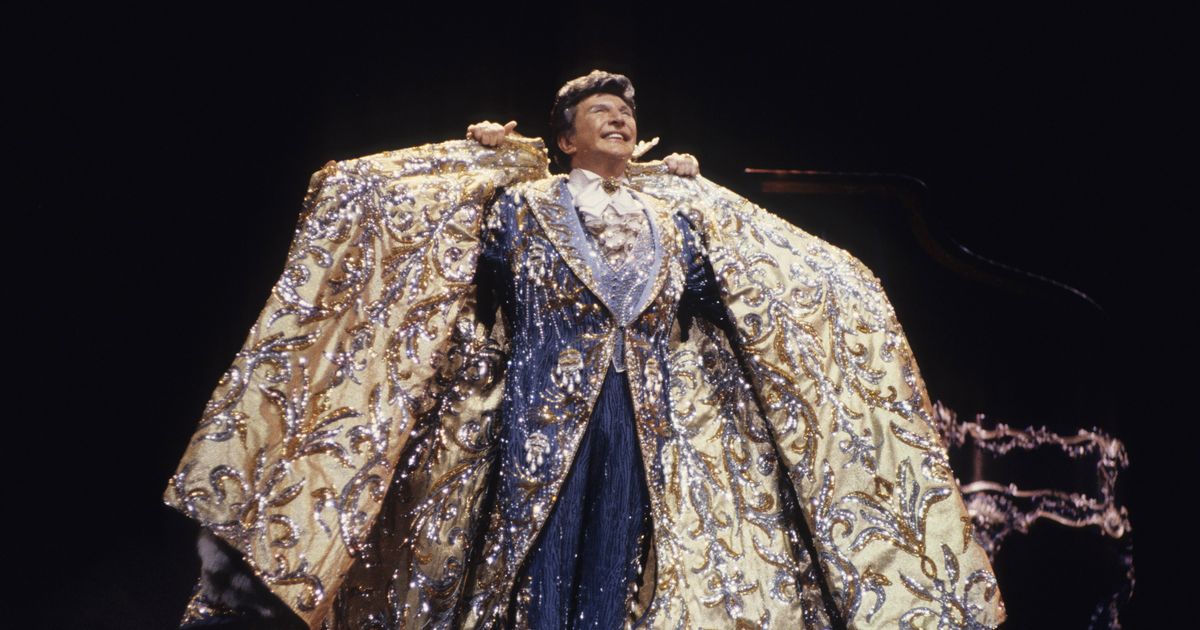
The Complete Overview of Who Inherited Liberace’s Fortune
Liberace’s death on February 4, 1987, triggered a domino effect of legal challenges that dragged on for over a decade. His will, drafted in 1973 and amended in 1983, named his nephew, Scott Thorson, as his sole beneficiary—a decision that stunned Liberace’s extended family, including his brother George Liberace and his sister Frances Liberace. Thorson, a former lover and business partner, was entrusted with managing the estate, but his relationship with Liberace’s kin was already fraught. The core issue: who inherited Liberace’s fortune hinged on whether Thorson’s role was legitimate or a product of coercion.
The estate’s complexity lay in its dual nature. Liberace had structured his affairs to protect his wealth from creditors (including the IRS, which had audited him in the 1970s) by transferring assets into trusts and limited partnerships. His will left everything to Thorson, but his brother George and sister Frances argued that Liberace had been mentally incapacitated when the will was signed and that Thorson had unduly influenced him. The battle centered on two key questions: Was the will valid? And did Liberace’s family have a moral—or legal—claim to his fortune?
Historical Background and Evolution
Liberace’s financial empire was built on decades of savvy branding. By the 1970s, he had transitioned from a touring pianist to a global entertainment mogul, leveraging television appearances, Las Vegas residencies, and merchandise (from Liberace-branded colognes to his signature white Cadillac). His net worth grew alongside his fame, but so did his legal vulnerabilities. In 1974, he settled a tax dispute with the IRS for $1.3 million, a fraction of what he owed but a sign of his financial agility. His estate planning reflected this paranoia: he used trusts to shield assets from probate, ensuring that even if his will was contested, his wealth wouldn’t be easily seized.
The turning point came in 1982, when Liberace and Thorson formed Liberace Enterprises, a company that managed his touring shows, recordings, and licensing. Thorson’s role as both personal partner and business executor created a conflict of interest that would later fuel accusations of financial mismanagement. When Liberace died, Thorson inherited not just his personal fortune but control over his professional empire—a power that made him a target for Liberace’s family. The legal fight over who inherited Liberace’s fortune wasn’t just about money; it was about who would control his legacy.
Core Mechanisms: How It Works
The mechanics of Liberace’s estate were designed to bypass traditional inheritance laws. His 1983 will left everything to Thorson, but the real complexity lay in the trusts and partnerships he’d established. For example:
- Revocable trusts held his real estate, allowing him to avoid probate but also giving Thorson immediate access to assets.
- Limited partnerships (like those used for his Las Vegas shows) obscured ownership, making it harder for creditors or family members to trace his wealth.
- Royalties and licensing deals were structured to continue generating income post-mortem, with Thorson as the primary beneficiary.
The legal battle hinged on Nevada probate law, which required proof of Liberace’s mental capacity and freedom from undue influence. His family argued that Thorson had isolated Liberace in his final years, pressuring him to change his will. Thorson countered that Liberace was fully competent and that the family’s claims were motivated by greed. The case dragged on until 1991, when a Nevada court upheld the will, confirming Thorson’s inheritance—but not without conditions. The judge ruled that Thorson had to distribute a portion of the estate to Liberace’s siblings, though the exact figures remain private.
Key Benefits and Crucial Impact
The resolution of who inherited Liberace’s fortune had ripple effects beyond the courtroom. For Liberace’s family, the outcome was bittersweet: they received a fraction of what they’d fought for, but the legal fees drained what little remained. For Thorson, the victory was hollow. He inherited a fortune that included debt (Liberace’s IRS liabilities and unpaid business loans) and a tarnished reputation. His later attempts to monetize Liberace’s image—through books, documentaries, and even a short-lived Las Vegas show—proved controversial, with critics accusing him of exploiting the legend’s memory.
The estate’s settlement also had cultural consequences. The Liberace Museum in Las Vegas, now a tourist attraction, was preserved but repurposed, stripping away some of its original opulence. The case became a cautionary tale in estate planning, illustrating how even the most meticulous preparations can collapse under familial infighting. Liberace’s story underscores a harsh truth: wealth isn’t just about accumulation—it’s about control, and control often outlives the person who wields it.
“Liberace’s fortune wasn’t just money; it was his identity. When you fight over an estate, you’re not just fighting over dollars—you’re fighting over who gets to define the person who’s gone.” — Estate litigation attorney specializing in celebrity cases (1992)
Major Advantages
The legal battle over who inherited Liberace’s fortune revealed several key advantages—and pitfalls—in celebrity estate planning:
- Trusts as shields: Liberace’s use of revocable trusts allowed his assets to bypass probate, but it also created a paper trail that his family later used to challenge his intentions.
- Business vs. personal assets: By separating his professional empire (Liberace Enterprises) from his personal wealth, he ensured that even if one was contested, the other remained intact.
- Nevada’s probate laws: The state’s relatively lenient rules on will contests gave his family a fighting chance, but it also meant that the case dragged on for years, costing millions in legal fees.
- The power of influence: Thorson’s role as both heir and executor gave him leverage, but it also made him a target—proving that in estate battles, perception is as critical as legality.
Comparative Analysis
| Aspect | Liberace’s Estate (1987) | Typical Celebrity Estate |
|--------------------------|------------------------------------------------------|------------------------------------------------------|
| Primary Heir | Nephew (business partner) | Spouse, children, or long-term partner |
| Contested Will | Yes (family vs. executor) | Often contested if relationships are strained |
| Estate Structure | Trusts + limited partnerships | Trusts, wills, and direct asset transfers |
| Legal Outcome | Partial victory for heir, but forced settlements | Varies—some estates settle quickly, others drag on |
| Cultural Impact | Museum repurposed, legacy commercialized | Often leads to documentaries or biopics |
Future Trends and Innovations
The Liberace estate case remains a benchmark in celebrity inheritance law, but modern trends suggest that such battles are becoming rarer—thanks to advances in estate planning. High-net-worth individuals now use dynasty trusts, private foundations, and digital asset directives to lock in their legacies. For example, the estate of Elvis Presley (another icon with a complex inheritance) has faced similar challenges, but Presley’s heirs have used modern trusts to distribute his fortune over decades, avoiding the kind of public spectacle that defined Liberace’s case.
Technology is also changing how estates are managed. Blockchain-based wills and AI-driven asset tracking could reduce the need for lengthy probate battles, though they raise new questions about security and accessibility. Meanwhile, the rise of celebrity family offices—like those managed by the children of Michael Jackson or Prince—shows how the ultra-wealthy are centralizing control to avoid the kind of fragmentation that plagued Liberace’s heirs.

Conclusion
The story of who inherited Liberace’s fortune is more than a footnote in entertainment history—it’s a case study in the fragility of legacy. Liberace’s wealth was a product of his genius, but its distribution was hijacked by legal technicalities and personal vendettas. His family walked away with crumbs, his business partner inherited a burden, and the public was left with a sanitized version of his life. The lesson? Wealth is only as secure as the people who guard it.
Yet, the Liberace estate’s enduring relevance lies in its honesty. Unlike the sanitized narratives of other celebrity fortunes, his story reveals the messy, human side of inheritance—where love, greed, and legal maneuvering collide. As estate planning evolves, Liberace’s case serves as a reminder: no matter how carefully you structure your affairs, the people who come after you will always find a way to complicate things.
Comprehensive FAQs
Q: Did Liberace’s brother George or sister Frances receive any money from the estate?
A: Yes, but far less than they sought. After years of litigation, a Nevada court ordered Scott Thorson to distribute a portion of the estate to George and Frances Liberace, though the exact amounts were never publicly disclosed. The settlement was part of a broader agreement to avoid further legal battles, but the siblings reportedly received only a fraction of what they’d claimed was rightfully theirs.
Q: What happened to Liberace’s Las Vegas mansion?
A: Liberace’s iconic mansion on the Las Vegas Strip was sold shortly after his death for $4.5 million (a fraction of its estimated value at the time). The buyer, a developer, demolished it in 1990 to make way for a hotel-casino complex. Today, the site is part of the Paris Las Vegas resort, and no physical remnants of the mansion remain. The Liberace Museum, however, was preserved and later repurposed as a tourist attraction.
Q: Was Scott Thorson ever fully in control of Liberace’s fortune?
A: No. While Thorson inherited the majority of the estate and initially controlled Liberace Enterprises, court-imposed conditions limited his authority. He was required to account for the estate’s finances, and disputes over unpaid debts (including IRS liabilities) further restricted his access to assets. Thorson later sold his rights to Liberace’s likeness and recordings, but he never achieved the level of control he’d initially wielded.
Q: How much was Liberace’s estate actually worth at the time of his death?
A: Estimates vary, but figures around $18 million (equivalent to over $50 million today) are commonly cited. This included cash, real estate, royalties, and business interests. However, the estate’s true value was obscured by Liberace’s use of trusts and partnerships, which made it difficult to assess the full scope of his wealth. Legal fees and debts further eroded its value during the probate process.
Q: Did Liberace’s will go through probate?
A: Yes, but only partially. Because Liberace had structured much of his wealth through trusts and limited partnerships, only a portion of his estate went through Nevada probate court. The contested will pertained to his personal assets, not the business entities he’d established. This strategy—common among high-net-worth individuals—allowed his heirs to avoid a full-scale probate battle, though it didn’t prevent legal challenges over the will’s validity.
Q: Are there any remaining legal disputes over Liberace’s estate?
A: As of recent years, no active legal disputes remain. However, occasional claims arise over Liberace’s intellectual property, particularly his recordings and likeness. In 2015, a dispute over the rights to his music led to a temporary injunction, but no major inheritance battles have emerged since the 1990s. The estate’s current management is handled by a trust overseen by Liberace’s heirs, with Thorson having sold his remaining interests decades ago.
Q: What lessons can modern celebrities learn from Liberace’s estate?
A: Liberace’s case highlights several key takeaways: 1. Avoid over-reliance on a single heir—especially if that person is also a business partner or family member with conflicting interests. 2. Use trusts strategically to bypass probate, but ensure they’re structured to withstand legal challenges. 3. Plan for family dynamics—even if you trust someone implicitly, their relationship with your relatives can derail your wishes. 4. Document mental capacity—if you’re concerned about future contests, record your decision-making process to preempt claims of undue influence. 5. Consider post-mortem management—some estates use "dead hand" provisions to give trustees authority even after the grantor’s death, reducing family interference.
Q: Has any of Liberace’s fortune been donated to charity?
A: Yes, but not directly from his estate. After the legal battles concluded, portions of the estate’s residual income were allocated to charitable causes, including the Liberace Foundation, which supported arts education and LGBTQ+ organizations (a cause close to Liberace’s heart). However, the majority of his fortune was distributed to his heirs or used to settle debts, with only a small percentage going to philanthropy.
