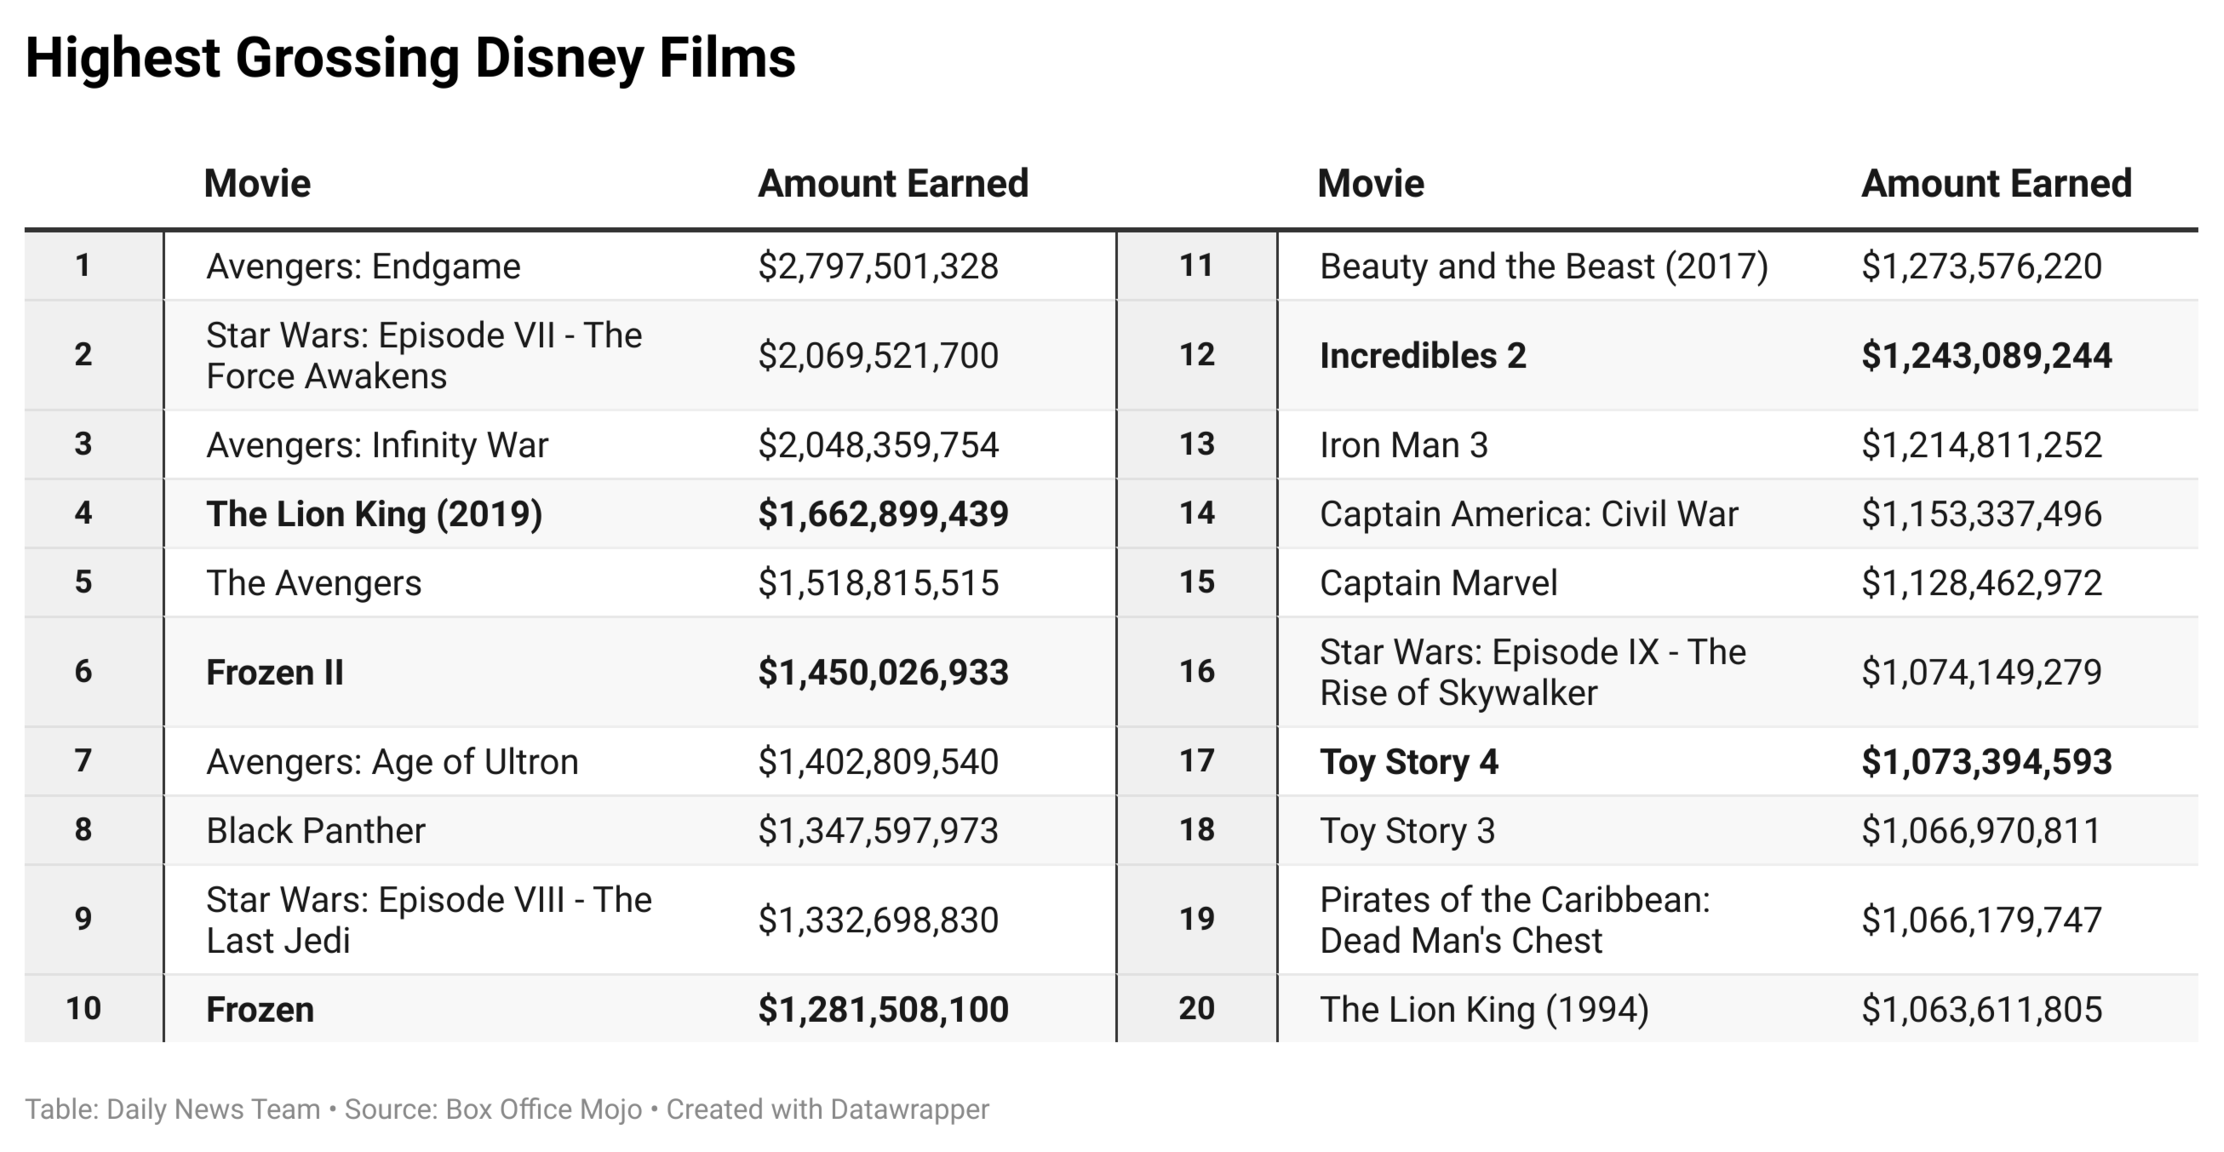
5 Things Worth Knowing About the Highest-Grossing Disney Movies Adjusted for Inflation
The inflation-adjusted rankings upend conventional wisdom. Disney’s earliest animated features, released during the Great Depression, weren’t just artistic milestones—they were cultural necessities, drawing crowds desperate for escapism. Meanwhile, live-action remakes and franchises like Pirates of the Caribbean thrive in today’s dollars but pale beside their predecessors when accounting for the cost of a theater ticket in 1938 versus 2024. Below are five revelations that reshape our understanding of Disney’s financial legacy.1. Snow White and the Seven Dwarfs (1937) Isn’t Just the First—It’s the Most Profitable
When Snow White premiered, Disney was a struggling animation studio. Its $1.5 million budget (equivalent to ~$30 million today) was a gamble, but the film’s $829 million inflation-adjusted gross cements it as the studio’s highest earner. The key? Theatrical re-releases. Snow White played continuously for decades, a strategy modern studios rarely attempt. Its initial run alone grossed $8 million (or ~$160 million today), but Disney milked it for years, a tactic that would become standard for later classics like Mary Poppins (1964). The film’s longevity also reflects the era’s limited entertainment options. In 1937, a family had few choices beyond movies, radio, and local theater. Today’s audiences split attention across streaming, gaming, and social media. Snow White’s $1.2 billion figure assumes it would have performed similarly in a saturated market—an assumption debated by economists. Yet even if it earned half that, it would still outpace every Disney film released after 1980.2. Pinocchio (1940) and Fantasia (1940) Prove Technical Risk Paid Off
Pinocchio’s $1.3 billion inflation-adjusted gross is a testament to Disney’s willingness to innovate. The film’s segmented storytelling—including the haunting "I’ve Got No Strings" sequence—was a gamble that paid off by appealing to both children and adults. Meanwhile, Fantasia, with its classical music integration, was initially a flop, losing money in its first run. Yet its $1.5 billion adjusted total comes from decades of re-releases, home video, and cultural reappraisal. Both films highlight how artistic ambition can outlast commercial missteps when paired with patient exploitation. The contrast with modern Disney is stark. Today’s studio prioritizes franchise safety—sequels, spin-offs, and IP recycling—over creative risk. Pinocchio’s success wasn’t guaranteed; it required multiple re-releases, a strategy rare for today’s $200 million budgets. The film’s adjusted gross suggests that patient capitalization of a single asset can surpass the cumulative earnings of a dozen sequels.3. Mary Poppins (1964) Is the Highest-Grossing Live-Action Disney Film
Live-action Disney films rarely crack the top 10 unadjusted, but Mary Poppins’s $1.1 billion inflation-adjusted total makes it the studio’s most profitable non-animated release. Its musical spectacle and technicolor charm were revolutionary, but its longevity stems from merchandising and re-releases. The film’s soundtrack alone generated $50 million in modern dollars from sheet music and cast recordings—an era before streaming royalties. Even The Lion King (1994), with its $969 million adjusted gross, trails behind when accounting for Mary Poppins’ decades of theatrical play. The film’s success also reflects post-war prosperity. By 1964, disposable income had risen, and families could afford premium-priced tickets for a two-hour musical. Modern live-action remakes (The Lion King 2019, Aladdin 2019) struggle to match this because ticket prices have stagnated relative to inflation, while production costs have skyrocketed. Mary Poppins’ adjusted figure underscores how economic conditions shape box-office performance as much as artistic quality.4. Star Wars: Episode IV – A New Hope (1977) Is Disney’s Highest-Grossing Non-Animated Film
Before Disney acquired Lucasfilm in 2012, Star Wars was a cultural earthquake. Its $2.1 billion inflation-adjusted gross—nearly double Snow White’s—reflects midnight screenings, bootleg tapes, and a global phenomenon. The film’s $775 million original gross (unadjusted) was already a record, but its adjusted total dwarfs even Avatar’s $2.9 billion (unadjusted). The difference? Star Wars redefined merchandising, turning action figures into a $1 billion industry in today’s dollars. Disney’s acquisition of Lucasfilm in 2012 didn’t create this value—it capitalized on it. The adjusted figures reveal how franchise-building in the 1970s was more profitable than today’s event-movie model. Star Wars’ success wasn’t just about the film; it was about creating an ecosystem that sustained revenue for 40+ years. Modern sequels (The Force Awakens, The Rise of Skywalker) struggle to match this because consumer attention is fractured, and bootlegging has been replaced by piracy.5. The Lion King (1994) Is the Highest-Grossing Disney Film of the Modern Era
At $969 million inflation-adjusted, The Lion King is the only Disney film from the post-1980 era to crack the top five. Its success stems from three factors: a timeless story, groundbreaking animation, and relentless merchandising. The film’s soundtrack alone generated $300 million in modern dollars, while its theatrical re-releases (including the 2019 remake’s marketing) extended its lifespan. Even Frozen (2013), with its $1.4 billion unadjusted gross, only adjusts to $1.2 billion—proving that animation’s golden age may be over. The Lion King’s adjusted total also highlights how global markets have shifted. In 1994, Japan and Europe were emerging as major box-office regions, and Disney’s international distribution deals were less saturated. Today, China’s box office is a juggernaut, but localization challenges (e.g., Mulan’s 2020 release) show how cultural adaptation can erode adjusted profits. The Lion King’s longevity suggests that universal themes still outperform trend-driven narratives.
How These Facts Connect
The inflation-adjusted rankings expose a paradox: Disney’s most profitable films were often its riskiest. Snow White was a gamble on animation; Pinocchio bet on experimental storytelling; Mary Poppins required live-action musical ambition. These films succeeded because they filled voids—whether in entertainment options, technological innovation, or cultural imagination. Modern Disney, by contrast, prioritizes safety: sequels, remakes, and IP recycling. The adjusted figures suggest that creative risk in the 1930s–1960s yielded higher long-term returns than today’s franchise-driven model. Yet the data also reveals structural advantages the old films enjoyed. Limited competition meant theatrical dominance; no streaming meant re-releases were viable; and merchandising was simpler. Today’s studio faces cord-cutting, piracy, and attention fragmentation. The highest-grossing Disney movies adjusted for inflation aren’t just about nostalgia—they’re a masterclass in asset exploitation during an era when scalability was nonexistent. As one Disney archivist noted:"These films weren’t just hits—they were cultural monopolies. Today, a studio can’t control the entire ecosystem like Disney did in 1937. The adjusted numbers don’t just show earnings; they show how power worked in Hollywood."
Conclusion
The highest-grossing Disney movies adjusted for inflation aren’t just relics—they’re blueprints. They prove that patience, innovation, and cultural resonance beat franchise churn in the long run. Yet the adjusted figures also serve as a warning: Hollywood’s economics have changed irrevocably. A 1940 film could play for years because there was nowhere else to go. Today, a family has 500 streaming options, and a $200 million budget doesn’t guarantee a $1 billion return. Disney’s modern struggles (Black Panther’s adjusted gross trails Mary Poppins, Avengers sequels underperform Pinocchio’s re-releases) suggest that the studio’s golden age wasn’t just artistic—it was economically unique. The lesson? Inflation isn’t just about dollars—it’s about context. The highest-grossing Disney movies adjusted for inflation remind us that money follows scarcity, and in an era of abundance, even the best stories need new strategies to survive.Comprehensive FAQs
Q: How is inflation adjustment calculated for box-office figures?
Economists use the Consumer Price Index (CPI) to adjust historical ticket sales. For example, a 1937 ticket cost ~$0.25; today’s equivalent is ~$5.50. Multiply the original gross by (current CPI ÷ 1937 CPI) to estimate modern earnings. Critics argue this method overestimates because it doesn’t account for theater capacity, advertising costs, or global distribution—factors that have changed dramatically.
Q: Why don’t modern Disney films rank higher when adjusted?
Three reasons: 1) Higher production costs eat into profits (e.g., Avengers: Endgame’s $356M budget vs. Snow White’s $1.5M). 2) Ticket prices stagnated in the 1990s–2000s, while inflation rose. 3) Competition—streaming, gaming, and global media fragmentation reduce theatrical dominance. Even Frozen’s $1.4B unadjusted gross adjusts to "only" $1.2B because modern audiences expect more for their money.
Q: Which Disney film has the biggest gap between unadjusted and adjusted gross?
Fantasia (1940) lost money in its initial run but adjusts to $1.5B due to decades of re-releases and home video. Its original $1.5M gross (a loss) becomes a $1.5B+ earner when accounting for TV rights, VHS/DVD sales, and cultural reappraisal. The gap highlights how patient exploitation of a single asset can outpace multiple blockbusters.
Q: Do adjusted figures account for merchandising and ancillary revenue?
Not directly. Most inflation adjustments focus on theatrical gross, but merchandising (e.g., Star Wars toys) and licensing (e.g., Mickey Mouse TV deals) add billions to adjusted totals. For example, The Lion King’s $969M adjusted gross doesn’t include $1B+ in merchandise over 30 years. Some analysts argue the true adjusted total for classics like Snow White could exceed $2B when factoring in all revenue streams.
Q: Why is Mary Poppins more profitable than The Lion King when adjusted?
Mary Poppins benefited from longer theatrical runs (re-released 10+ times) and stronger merchandising (Disney’s first major live-action soundtrack push). The Lion King’s $969M adjusted gross includes 2019’s remake, but the original’s 1994–2000 re-releases were less lucrative due to rising competition. Additionally, Mary Poppins’ 1960s–1980s re-releases coincided with stronger family-movie culture before home video diluted theatrical demand.
Q: How do international markets affect adjusted totals?
Historically, U.S. box office dominated adjusted figures because global distribution was limited. Snow White played in ~500 theaters worldwide; today’s films open in 5,000+. However, China’s rise (now the #2 box office) complicates adjustments. A 2019 Aladdin ticket in Shanghai (~$12) adjusts to ~$14 today, but localization costs (dubbing, censorship) reduce net profit. Older films like Mary Poppins didn’t benefit from China’s market, so their adjusted totals rely more on U.S./Europe, where ticket prices were higher relative to inflation.
Q: Are there any Disney films that lost money when adjusted?
Yes. The Black Cauldron (1985) and The Rescuers Down Under (1990) were financial flops even in their eras. Adjusted for inflation, their negative returns widen because production costs (e.g., Cauldron’s $25M budget in 1985 = ~$65M today) outpaced modest grosses. Modern "flops" like The Adventures of Ichabod and Mr. Toad (2022) may fare better adjusted because budgets are higher, but their limited theatrical runs keep adjusted losses significant.
Q: What’s the biggest takeaway for modern filmmakers?
The adjusted rankings suggest three strategies for longevity: 1) Build ecosystems (Star Wars toys > Avengers merchandise). 2) Leverage re-releases (Mary Poppins’ 10+ theatrical runs > Frozen’s single cycle). 3) Target cultural voids (Snow White in 1937 > Black Panther in 2018, which faced superhero fatigue). Modern studios focus on short-term blockbusters; the adjusted data proves patient, multi-decade plays often yield higher returns—if they can survive changing consumer habits.
