Common Myths About Women and Net Worth
The first myth is that women and net worth is a simple math problem: if women earn less, they’ll naturally accumulate less. The reality is more complex. Wage gaps alone don’t explain why, by retirement, women’s median net worth is just 35% of men’s. The missing piece? Caregiving penalties. A Pew Research analysis found that women spend nearly twice as many hours weekly on childcare and eldercare as men—a labor market tax that shrinks earning potential and derails career trajectories. The myth ignores how these unpaid roles create a wealth time bomb: years spent out of high-earning roles or working part-time to manage family obligations mean fewer years to contribute to 401(k)s or invest in assets that appreciate over time. Another persistent claim is that women lack financial literacy, making them poor stewards of wealth. The evidence contradicts this. A 2022 TIAA Institute study found women outperform men in retirement planning, with higher savings rates and better debt management. The issue isn’t competence—it’s access. Women are less likely to receive financial education early in life, and when they seek advice, they’re often steered toward conservative products that yield lower returns. The myth of financial incompetence obscures the real barrier: a system that doesn’t equip women with the tools or confidence to play the same wealth-building game as men. The third myth frames women and net worth as a binary—either you’re a high-earning executive or you’re struggling. In truth, the gap is widest at the extremes. Women in the top 10% of earners still trail men by 28% in net worth, while those in the bottom 50% see a 40% disparity. The middle class, where most women fall, is where the systemic cracks show: fewer opportunities for promotions, less access to high-yield investments, and a cultural bias that assumes men are the "breadwinners" even in dual-income households.Myth 1: Women Earn Less, So They Build Less Wealth
The wage gap is undeniable, but it’s not the sole driver of the women and net worth divide. A 2021 Brookings Institution report found that even when controlling for hours worked and education, women’s wages lag by 5%—a figure that grows when factoring in race and industry. However, the wealth gap persists even among high-earning women. For example, a female physician with 20 years of experience may earn 92% of her male counterpart’s salary, yet her net worth could still be 30% lower due to differences in asset ownership. The problem isn’t just income; it’s asset accumulation. Men are more likely to inherit wealth, receive higher-value bonuses tied to stock options, or benefit from spousal financial support that women rarely access. The solution isn’t just closing the wage gap—it’s rewriting the rules of wealth transfer. Consider real estate, the largest asset class for most households. Women are 18% less likely to own their primary home, and when they do, the properties are often smaller or located in less appreciating markets. Policies that favor first-time homebuyers—like down payment assistance—rarely account for the fact that women are more likely to be single parents or caregivers, making it harder to qualify for mortgages. The myth that women and net worth is purely an income issue ignores how wealth compounds through ownership, inheritance, and systemic advantages that men inherit by default.Myth 2: Women Are Bad Investors
The stereotype of women as "risk-averse" investors is overblown—and often weaponized to justify why they’re excluded from high-growth opportunities. A 2020 Fidelity study found women investors outperform men by 0.4% annually, thanks to lower trading volumes and a focus on long-term strategies. Yet women are systematically steered away from volatile but high-reward assets like venture capital or cryptocurrency. A Harvard Business Review analysis revealed that female entrepreneurs receive just 2% of venture capital funding, despite launching businesses with higher survival rates. The myth of financial incompetence is a self-fulfilling prophecy: if women are told they’re not "built for risk," they’ll never be invited to the table where those risks are taken. The real issue is social capital. Men dominate the networks that control access to alternative investments—think private equity clubs, angel investor circles, or old-boy networks that hand out seed funding. Women, even high-net-worth ones, are often sidelined. Take the case of a female tech executive who co-founded a unicorn startup: she held 30% equity but was excluded from the board until a gender diversity push forced her inclusion. By then, the company had already issued millions in stock options to male employees. The myth that women are bad investors ignores the fact that they’re often excluded from the games that create wealth in the first place.Myth 3: The Wealth Gap Is Just About Saving Habits
Personal finance gurus love to blame the wealth gap on "bad habits"—women spending more on "lifestyle" or failing to budget aggressively. The data tells a different story. Women save more than men, with an average savings rate of 6.3% compared to men’s 5.4%. The problem isn’t discipline; it’s opportunity. A woman saving $500/month in a high-yield savings account will earn minimal returns, while a man with the same savings might invest in a startup that 10x in value. The gap isn’t about frugality—it’s about who gets to gamble on the next Amazon. Consider the world of real estate investing, where women own just 2% of commercial properties. The barrier isn’t financial acumen; it’s access to capital. A male investor with a $200,000 down payment might secure a $1 million property with a bank loan, while a woman with the same savings is more likely to be steered toward safer, lower-return investments. The myth that women and net worth is a matter of personal responsibility ignores the fact that wealth is built on leverage—and women are consistently denied the tools to leverage their assets effectively.
What Holds Up to Scrutiny
Three verifiable truths emerge when examining women and net worth: first, the gap is widest among older women, where decades of wage suppression and caregiving penalties accumulate. Second, women’s wealth is more precarious—they’re more likely to live on fixed incomes in retirement and face longer lifespans with fewer assets to draw from. Third, the strategies that work for men—aggressive investing, high-risk career bets—don’t always translate for women, who need different playbooks to build generational wealth. The data also shows that women who do accumulate significant net worth often do so through collective strategies. Take the case of Black women, who have the lowest median net worth of any group. Yet those who achieve wealth often rely on community-based investing—pooling resources to buy property or start businesses. A 2023 study by the Women’s Institute for a Secure Retirement found that women who joined investment circles with other women saw their portfolios grow 22% faster than those investing solo. The solution to women and net worth isn’t individualism; it’s systemic support."Wealth isn’t built by saving alone—it’s built by owning things that appreciate, by inheriting opportunities, and by being in rooms where decisions about capital are made. Women are still excluded from those rooms." —Diane Morefield, economist and author of The Billionaire Raj
| Common Belief | What the Evidence Says |
|---|---|
| Women save less than men. | Women save more (6.3% vs. 5.4%), but their assets grow slower due to limited access to high-yield investments. |
| Financial literacy is the main barrier. | Women outperform men in retirement planning, but they’re excluded from high-growth networks and assets. |
| The wealth gap will close as more women enter leadership. | Even high-earning women face asset gaps—men inherit wealth, receive higher-value bonuses, and control key investment networks. |
Why the Confusion Persists
The narrative around women and net worth is stuck in a loop because it serves powerful interests. Financial institutions profit from selling women "safe" products with low returns, while policymakers avoid addressing structural issues like inheritance taxes or caregiving support. The myth of the "financially irresponsible woman" also plays into gender stereotypes, making it easier to justify why she shouldn’t be trusted with high-stakes investments. Meanwhile, the media amplifies outliers—like the female CEO or influencer who "made it"—while ignoring the systemic barriers that keep 90% of women from replicating those outcomes. The confusion also stems from how wealth is measured. Net worth is a snapshot, but it doesn’t capture liquid assets or human capital—the skills and networks that could translate into future wealth. A woman who owns her home but has no retirement savings might appear "poor" on paper, but her asset could be worth millions. The conversation about women and net worth needs to move beyond static numbers and focus on wealth mobility—how women can turn their resources into lasting financial security.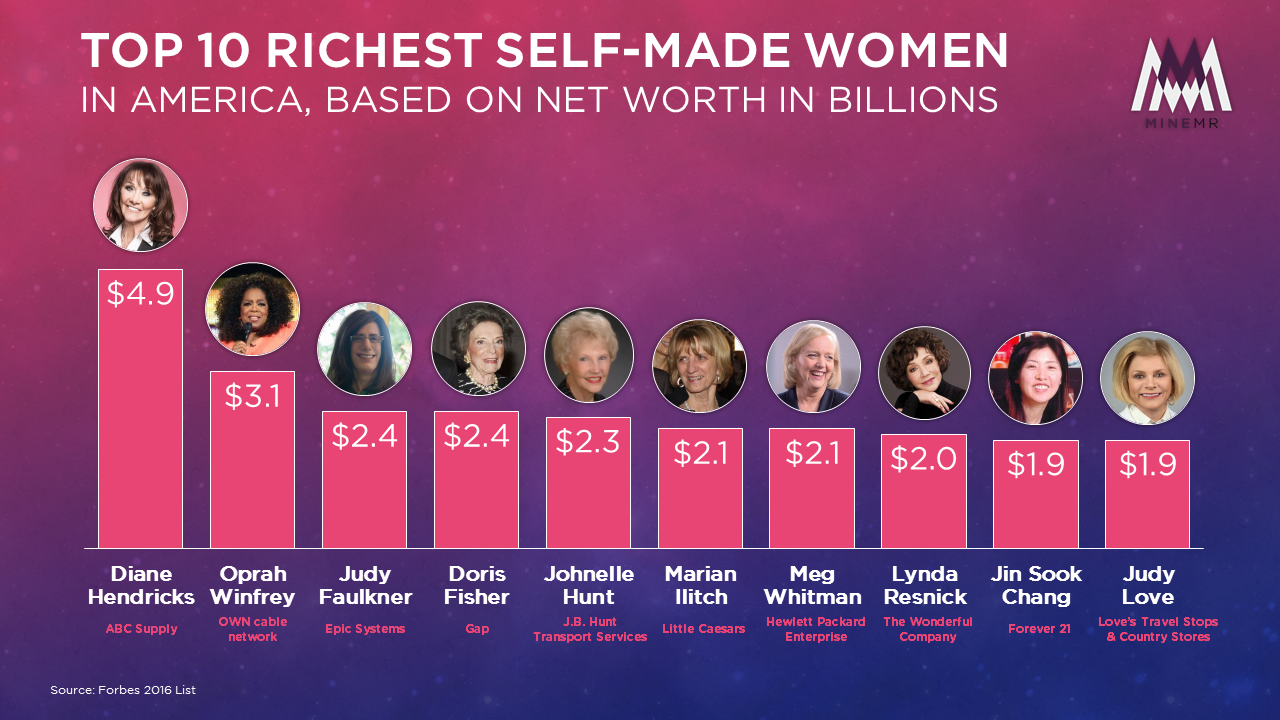
Conclusion
The story of women and net worth isn’t one of failure—it’s one of uneven playing fields. Women aren’t bad at building wealth; they’re denied the tools to do so at scale. The solution requires dismantling the myths that blame individuals while ignoring the structural forces at play. It means rethinking policies that favor inherited wealth over earned wealth, expanding access to high-growth assets, and recognizing that wealth isn’t just about money—it’s about power. The good news? The data shows that when women are given the right opportunities, they thrive. The challenge is creating those opportunities at scale—not just for the next Sheryl Sandberg, but for the millions of women who are currently invisible in the wealth equation.Comprehensive FAQs
Q: Why do women’s net worth figures lag so far behind men’s, even when they earn similar salaries?
A: The gap persists because wealth isn’t just about income—it’s about asset ownership, inheritance, and access to high-growth opportunities. Women are less likely to inherit wealth, receive stock options, or benefit from spousal financial support. Even when earning similarly, men are more likely to invest in assets that appreciate faster (like real estate or startups), while women are steered toward lower-return products. Caregiving penalties also play a role: women spend more time out of high-earning roles, reducing their ability to contribute to retirement or invest in appreciating assets.
Q: Are there industries or professions where women actually outperform men in net worth?
A: Yes, but they’re often female-dominated fields with structural advantages. For example, women in healthcare (especially nursing) tend to have lower net worth due to wage suppression, but those in specialized roles—like physician assistants or nurse practitioners—can build significant wealth through long-term savings and asset accumulation. Another example is education: women make up 57% of college graduates, and those who enter high-paying fields like law or finance (where they’re still underrepresented) can close the gap—though they often face glass ceiling barriers in promotions. The key is industries with strong retirement benefits, union protections, or asset-building opportunities (like real estate investing).
Q: How can women start closing the wealth gap if they’re already behind?
A: The first step is asset diversification beyond savings accounts. Women should prioritize:
- Homeownership (even if it’s a starter home in a growing market).
- Retirement accounts (Roth IRAs and 401(k)s with employer matches).
- Alternative investments (REITs, crowdfunded real estate, or women-led funds).
- Estate planning (to ensure wealth transfers to future generations).
Q: What’s the biggest misconception about women and financial independence?
A: The biggest myth is that financial independence is an individual achievement. In reality, it’s collective. Women who build wealth often do so through community support—whether it’s co-signing loans, pooling resources for real estate, or leveraging female-led investment networks. The narrative that "you’re on your own" ignores how systemic barriers (like lack of access to capital or caregiving penalties) make it harder for women to accumulate wealth. True financial independence requires structural change, not just personal discipline.
Q: Are there countries where the gender wealth gap is narrower?
A: Yes, but the differences often come down to policy, not culture. Nordic countries like Sweden and Norway have narrower gaps due to:
- Strong parental leave policies (reducing caregiving penalties).
- Progressive taxation that reduces wealth concentration.
- Gender quotas in corporate boards, increasing women’s access to high-paying roles.
