6 Things Worth Knowing About Net Worth of Retirees Comparison
The net worth of retirees comparison isn’t just a matter of personal discipline—it’s a reflection of broader economic forces. Six key insights stand out when analyzing the data across demographics, regions, and generations.1. Geography Overrides Income in Retiree Wealth
A retiree in Hawaii or California will face a fundamentally different financial reality than one in Ohio or Texas, even if their pre-retirement incomes were identical. The net worth of retirees comparison by state shows that cost of living isn’t just about groceries and gas—it’s about housing, healthcare, and taxes. In high-cost states, retirees often downsize or relocate to lower-tax areas like Florida or Tennessee, where property taxes and income taxes are minimal. This migration isn’t just a lifestyle choice; it’s a wealth-preservation strategy. The numbers tell a clear story: retirees in states with no income tax tend to have higher median net worths, not because they earn more, but because their savings stretch further. A retiree couple in Florida with $500,000 in assets might have the same purchasing power as a couple in New York with $700,000—because the Florida couple isn’t bleeding money to state taxes or high rents. The net worth of retirees comparison by region often masks this geographic arbitrage, making it seem like some retirees are inherently wealthier when they’re simply optimizing their tax burden.2. The Generational Divide in Retirement Assets
Baby Boomers entered the workforce during a period of rising wages and strong unionization, while Gen X and Millennials faced stagnant wages, the 2008 financial crisis, and the student debt crisis. The net worth of retirees comparison between Boomers and younger retirees is stark: Boomers, now in their 70s and 80s, benefited from home equity growth, defined-benefit pensions, and bull markets in stocks and real estate. Many entered retirement with portfolios inflated by decades of compound growth. In contrast, younger retirees—those who left the workforce in the 2010s or 2020s—often rely on 401(k)s and IRAs, which were hammered by the 2008 crash and never fully recovered for many. The net worth of retirees comparison also shows that younger retirees are more likely to have student debt or caregiving expenses that erode their savings. While Boomers might retire with $1 million or more, Gen X retirees in their early 60s often struggle with balances under $300,000. This gap isn’t just about saving habits; it’s about the economic conditions they inherited.3. Healthcare Costs Are the Silent Wealth Killer
Most discussions about retirement focus on income replacement, but the net worth of retirees comparison reveals that healthcare expenses are the single biggest threat to long-term financial security. A 65-year-old couple today can expect to spend $300,000–$500,000 on healthcare in retirement, according to Fidelity estimates. For retirees with modest savings, this can wipe out decades of accumulation. The net worth of retirees comparison between those with employer-sponsored retiree health benefits and those without shows a chasm—some retirees face healthcare costs that eat 20% of their annual income, while others pay a fraction of that. Long-term care is where the disparities become most brutal. A single year in a nursing home can cost $100,000 or more, and most retirees don’t have long-term care insurance. The net worth of retirees comparison often shows that those who didn’t plan for healthcare end up liquidating assets or relying on family—while those who did may have portfolios that seem artificially inflated because they set aside funds specifically for medical expenses.4. Homeownership Remains the Great Equalizer
Owning a home is the single biggest driver of retiree wealth for most Americans. The net worth of retirees comparison between homeowners and renters is one of the most striking in financial literature: homeowners over 65 have a median net worth 10 times higher than renters of the same age. This isn’t just about the value of the home—it’s about equity that can be tapped through reverse mortgages, downsizing, or simply selling to fund retirement. But homeownership isn’t a universal advantage. Retirees who bought homes during the 2000s housing bubble saw their equity wiped out in the crash, and many never recovered. The net worth of retirees comparison also shows that Black and Latino retirees are far less likely to own homes with significant equity, due to historical redlining and discriminatory lending practices. For these retirees, the lack of home equity means relying on Social Security alone, which for most couples replaces only about 40% of pre-retirement income.5. Inheritances and Windfalls Distort the Picture
The net worth of retirees comparison often obscures the role of inheritances, which can make the difference between a comfortable retirement and a precarious one. Studies suggest that one-third of retirees receive some form of inheritance, and for many, this is the only reason their net worth exceeds $500,000. A retiree who inherits a family home or investment portfolio might appear wealthy in the data, while someone with identical savings but no inheritance struggles to meet basic needs. This is particularly true for women, who are more likely to live longer and thus benefit from spousal inheritances. The net worth of retirees comparison by gender shows that married women often have lower personal net worths than married men—but higher combined household net worths because they inherit assets after their spouses pass away. The data here is messy, but the takeaway is clear: wealth begets wealth, and retirees who start with a financial head start are far more likely to end their lives with one.6. The Role of Defined-Benefit Pensions Is Shrinking
In 1980, nearly 60% of private-sector workers had access to a defined-benefit pension. Today, that number is below 20%. The net worth of retirees comparison between those who retired with a pension and those who didn’t shows a dramatic shift: retirees with pensions have 30–50% higher median net worths than those relying solely on 401(k)s and Social Security. Pensions provide a guaranteed income stream that eliminates market risk, allowing retirees to keep their savings intact.
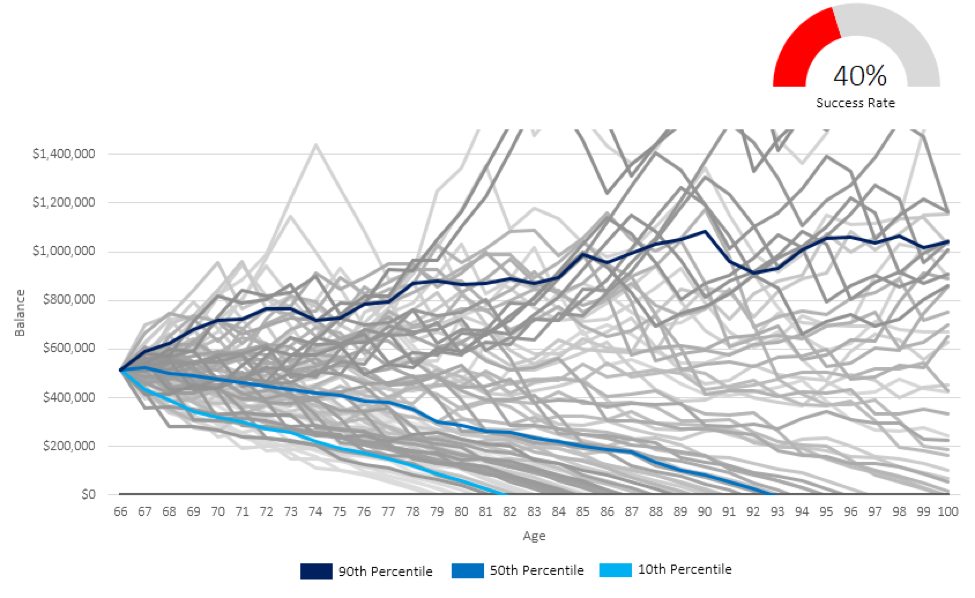
But the decline of pensions has forced retirees to take on more risk themselves. The net worth of retirees comparison now reflects a world where retirees must manage their own investments, navigate sequence-of-returns risk (where bad market timing early in retirement can devastate a portfolio), and live longer than ever before. Without pensions, retirees are increasingly reliant on home equity, annuities, or part-time work—none of which are guaranteed.
How These Facts Connect
The net worth of retirees comparison isn’t just about individual choices—it’s about the cumulative effect of economic policies, labor market trends, and geographic luck. When you overlay these six factors, a pattern emerges: retirees who benefited from strong pensions, home equity growth, and low healthcare costs are the ones with the highest net worths. Those who missed out on homeownership, faced stagnant wages, or retired during a market downturn are the ones struggling. The system isn’t neutral; it rewards certain paths and penalizes others. This isn’t just a story about saving more—it’s about recognizing that retirement wealth is shaped by forces beyond an individual’s control. A retiree in Florida with a pension and a paid-off home will have a different net worth trajectory than a retiree in Chicago with student debt and no employer benefits. The net worth of retirees comparison reveals that the biggest divide isn’t between those who saved and those who didn’t—it’s between those who had access to the right tools (pensions, homeownership, low taxes) and those who didn’t.| Factor | Impact on Net Worth | Example |
|---|---|---|
| Geography | Can increase or decrease net worth by 30–50% | A retiree in Texas vs. a retiree in Massachusetts with identical savings |
| Generational Timing | Boomers have 2–3x the net worth of Gen X retirees | A 1980s retiree with a pension vs. a 2010s retiree with a 401(k) |
| Homeownership | Homeowners have 10x the net worth of renters | A couple who paid off their mortgage vs. a couple who never owned |
| Healthcare Costs | Can erode 20–40% of retirement savings | A retiree with Medicare Advantage vs. one without supplemental insurance |
| Inheritances | Can add $200K–$500K+ to net worth | A retiree who inherits a home vs. one who doesn’t |
Conclusion
The net worth of retirees comparison isn’t just a dry statistical exercise—it’s a mirror held up to the economic realities of aging in America. The data shows that retirement security isn’t just about how much you save; it’s about when you saved, where you lived, and what kind of safety net you had along the way. For policymakers, this means recognizing that retirement planning isn’t a one-size-fits-all proposition. For individuals, it means understanding that the traditional playbook—save aggressively, buy a home, rely on Social Security—no longer guarantees comfort in old age. The biggest takeaway? Retirement wealth is a product of systemic advantages as much as personal discipline. The retirees who thrive are often those who navigated the system’s biases—whether through homeownership, geographic mobility, or inheriting wealth. The rest are left playing catch-up. The question for the future isn’t just how to save more, but how to design a system where retirement security isn’t left to luck.Comprehensive FAQs
Q: How does Social Security replace pre-retirement income?
Social Security replaces about 40% of the average worker’s pre-retirement income for couples and 30–35% for single retirees, according to the Social Security Administration. However, benefits are progressive—lower earners replace a higher percentage of their income, while high earners see a smaller replacement rate. The net worth of retirees comparison shows that those relying solely on Social Security often have net worths below $200,000, while those with pensions or investments can afford to take smaller Social Security benefits without financial strain.
Q: Can retirees afford to downsize their homes?
Downsizing is a common strategy to boost retirement income, but the net worth of retirees comparison reveals mixed results. Retirees who sell a home and move to a cheaper area can free up $200,000–$500,000 in equity, but transaction costs, taxes, and potential capital gains taxes can eat into profits. Additionally, moving disrupts social networks and healthcare access—factors that can indirectly affect long-term well-being. Some retirees use reverse mortgages to tap home equity without selling, but these come with risks, including high fees and potential debt passing to heirs.
Q: How do retirees in different states compare?
The net worth of retirees comparison by state shows wide variations. Retirees in Florida, Texas, and Tennessee tend to have higher median net worths due to low taxes and affordable living costs, while those in California, New York, and Massachusetts often have lower net worths despite higher incomes because of high housing and tax burdens. States with strong public pension systems (e.g., California, New Jersey) see retirees with higher guaranteed income streams, while others rely more on private savings. The net worth of retirees comparison also highlights that retirees in high-cost states often delay retirement or work longer to compensate.
Q: What’s the biggest mistake retirees make with their savings?
The net worth of retirees comparison consistently shows that retirees who withdraw too much too soon from their portfolios face the highest risk of running out of money. The "4% rule" (withdrawing 4% annually) is a common guideline, but retirees who pull out more—especially in early retirement—can deplete their savings faster than expected. Another mistake is underestimating healthcare costs, which can force retirees to liquidate assets or take on debt. Finally, retirees who ignore inflation in their spending plans often find their savings stretched thinner than anticipated over decades.
Q: How do retirees with student debt compare to those without?
Retirees with student debt—often from children or their own education—face a net worth of retirees comparison that’s 20–30% lower than those without debt. Student loans are rare among retirees (only about 5% of retirees have them), but for those who do, the burden is significant. Many retirees take on loans in their 60s to pay for grandchildren’s college or their own late-in-life degrees, which can delay retirement or force them to work longer. The net worth of retirees comparison shows that retirees with student debt are more likely to rely on part-time work or reverse mortgages to stay afloat.
