
Common Myths About African American Net Worth
The first myth is that African American net worth is improving at a steady pace. In reality, progress has been erratic, tied to economic cycles rather than systemic change. The wealth gap narrowed slightly after the 2008 financial crisis—not because Black families recovered, but because white families lost ground. By 2020, the gap had widened again, with the median white family worth $188,200 compared to $24,100 for Black families. This isn’t a failure of individual effort; it’s a failure of policy. Another persistent myth is that African American wealth is primarily tied to entrepreneurship. While Black-owned businesses are growing, they face higher failure rates due to limited access to capital. A 2021 study found that Black entrepreneurs receive just 0.5% of venture capital, despite making up 13% of the U.S. population. The narrative of the "self-made" Black millionaire ignores the fact that most wealth accumulation in America relies on inherited assets, home equity, and stock portfolios—areas where Black families are systematically locked out. The third myth is that African American financial struggles are a result of cultural attitudes toward money. This ignores the historical context: redlining, predatory lending, and the deliberate dismantling of Black institutions like banks and credit unions. Even today, Black families pay higher interest rates on loans and mortgages, a direct legacy of discriminatory practices that persist in modern lending algorithms.Myth 1: The wealth gap is closing
The idea that African American net worth is catching up to white households is a statistical illusion. While the median income gap has narrowed slightly, wealth is a different story. Wealth includes assets like homes, stocks, and businesses—areas where Black families have historically been excluded. A 2023 Brookings Institution report found that African American net worth would need to grow at three times the rate of white households just to close the gap by 2050. That’s not happening. The confusion arises because income and wealth are often conflated. Black families may earn more in certain professions, but their ability to convert income into assets is severely limited. For example, Black homeownership rates remain 20 percentage points lower than white homeownership rates, despite similar levels of income. Home equity is the largest wealth-building tool for most Americans—and Black families are systematically denied access to it.Myth 2: Black entrepreneurship is the key to wealth
The narrative that African American financial growth depends on entrepreneurship ignores the reality of capital access. Black-owned businesses generate $150 billion annually, but they receive a fraction of the funding that white-owned businesses do. A 2022 Harvard Business School study found that Black founders are half as likely to receive venture capital as white founders, even when their businesses show identical growth potential. Even when Black entrepreneurs succeed, their wealth is often concentrated in a few sectors (retail, services, personal care) rather than high-growth industries like tech or finance. Without access to the same networks, mentorship, and capital, African American net worth built through business remains fragile. The solution isn’t just "start a business"—it’s leveling the playing field so that Black entrepreneurs have the same opportunities as their white counterparts.Myth 3: Personal responsibility explains the gap
The argument that African American financial struggles are due to poor spending habits or lack of discipline ignores the role of systemic barriers. Black families are more likely to live in high-cost urban areas with limited grocery options, forcing them to spend a larger portion of their income on necessities. They’re also more likely to be targeted by predatory lenders, paying higher fees for everything from car loans to credit cards. Historically, Black families have been excluded from wealth-building tools like 401(k) matches, stock ownership programs, and home equity loans. Even when they earn similar incomes, Black workers are less likely to receive promotions or raises that could boost their long-term wealth. The myth of personal responsibility obscures the fact that African American net worth is shaped by policies that have denied Black families access to generational wealth for decades.
What Holds Up to Scrutiny
The most reliable data on African American net worth comes from the Federal Reserve’s Survey of Consumer Finances, which tracks wealth by race over time. The numbers are stark: in 2022, the median white family had $188,200 in net worth, while the median Black family had $24,100. This isn’t a temporary dip—it’s a long-term trend. Even in the post-civil rights era, Black families have seen no sustained growth in wealth relative to white families. What’s less discussed is how African American net worth is concentrated in liquid assets like cash and retirement accounts, rather than illiquid assets like homes and businesses. Black families are more likely to rely on savings for emergencies, leaving them vulnerable to economic shocks. Meanwhile, white families benefit from home equity lines of credit, inherited wealth, and stock market gains—tools that Black families rarely access."Wealth is not just about income—it’s about access. Black families have been excluded from the tools that build wealth for generations. Until we address that, the gap won’t close." — Darrick Hamilton, economist and professor at The New School
| Common Belief | What the Evidence Says |
|---|---|
| Black families are poor because they don’t save enough. | Black families save at similar rates to white families, but their savings are eroded by higher costs (housing, healthcare, education) and limited asset growth. |
| Entrepreneurship is the fastest path to wealth for Black Americans. | Black businesses face higher failure rates due to lack of capital, mentorship, and access to high-growth industries. |
| The wealth gap is shrinking. | It widened after 2020, with Black families losing ground in homeownership and stock market participation. |
| Celebrity net worth reflects the average Black family. | Outliers like Oprah or Beyoncé represent less than 0.1% of Black households; the median net worth is far lower. |
Why the Confusion Persists
Part of the problem is that African American net worth is often discussed in isolation from its historical context. The wealth gap didn’t emerge in the 1960s—it was built during slavery, reinforced by Jim Crow, and perpetuated by modern policies like mass incarceration and predatory lending. Without this framework, conversations about wealth become superficial, focusing on individual behavior rather than systemic change. Another factor is the media’s tendency to highlight outliers. Stories about Black millionaires dominate headlines, while the struggles of the average Black family go unreported. This creates a distorted perception of African American financial standing, making it seem as though wealth is more widespread than it is. The reality is that 90% of Black families have net worth below the national median.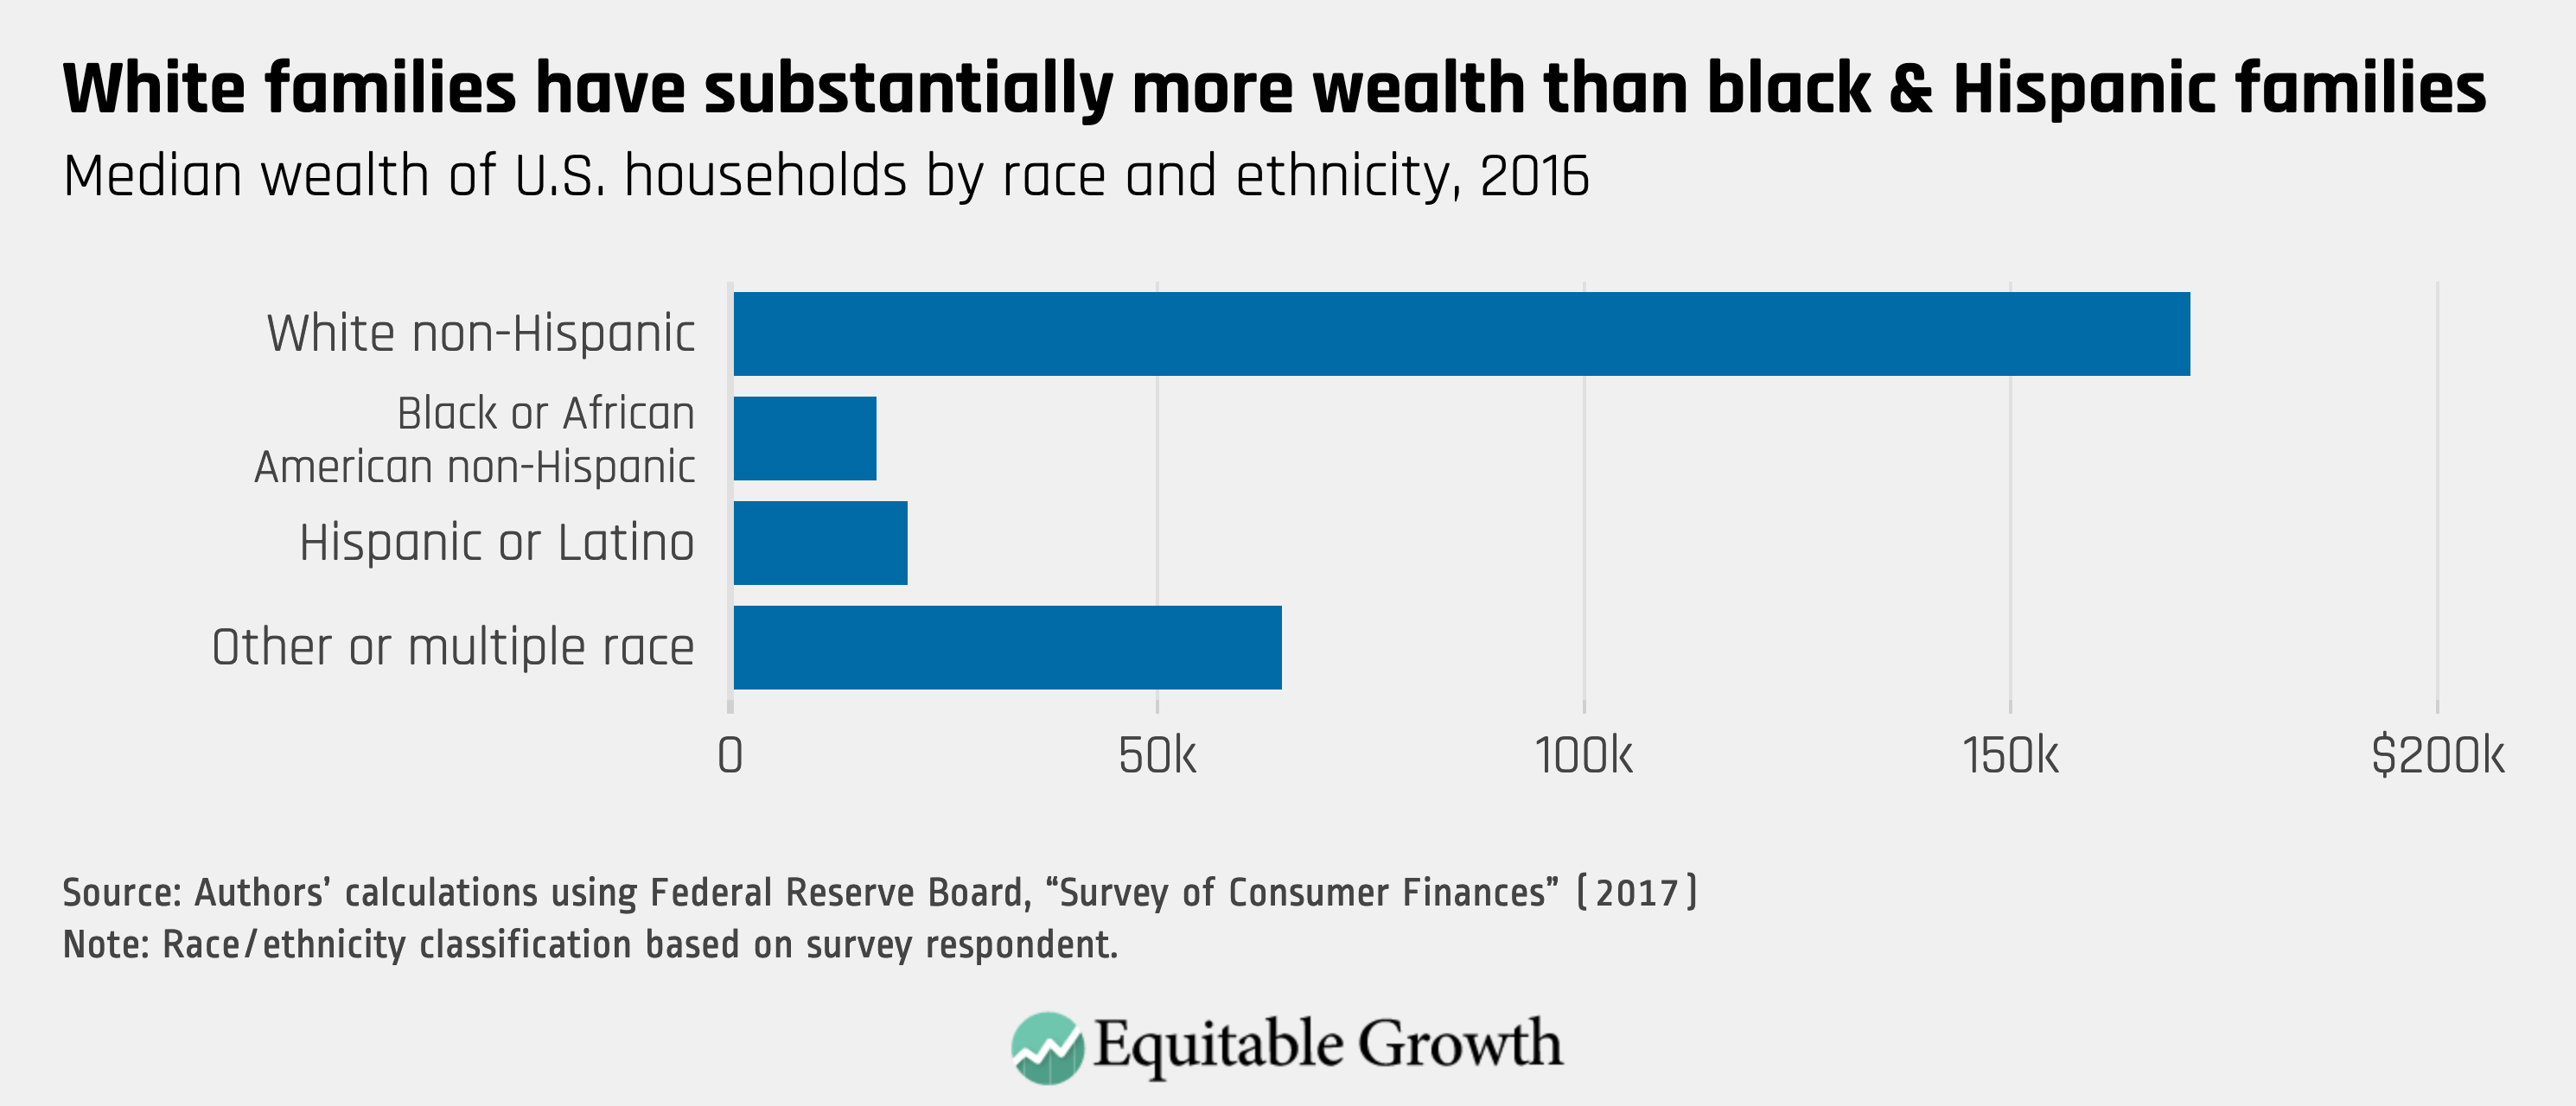
Conclusion
The data on African American net worth is clear: systemic barriers—not personal failure—explain the wealth gap. Homeownership, inheritance, and access to capital are the biggest drivers of wealth, and Black families have been excluded from all three for generations. The solution isn’t just financial literacy programs or entrepreneurship incentives—it’s policy change: expanding homeownership opportunities, closing the racial wealth gap through reparations discussions, and ensuring fair access to capital. Until then, the conversation about African American financial health will remain stuck between myth and reality. The numbers don’t lie: Black families need more than motivation—they need opportunity.Comprehensive FAQs
Q: Why is the wealth gap between Black and white families so large?
A: The gap stems from centuries of policy, including slavery, Jim Crow laws, redlining, and modern predatory lending. Black families have been systematically excluded from wealth-building tools like homeownership, stock ownership, and inheritance. Even today, Black workers earn less, face higher costs, and have limited access to capital—all of which prevent wealth accumulation.
Q: Can Black families close the wealth gap through entrepreneurship?
A: Entrepreneurship helps, but it’s not enough. Black-owned businesses receive far less funding than white-owned businesses, and they’re concentrated in lower-growth industries. Without policy changes—like better access to venture capital, mentorship, and fair lending—entrepreneurship alone won’t bridge the gap.
Q: Do high-profile Black millionaires change the narrative about African American net worth?
A: No. While figures like Oprah Winfrey or Michael Jordan represent success, they’re outliers. The median African American net worth remains far below the white median. Celebrating individual success doesn’t address the systemic barriers that affect the majority of Black families.
Q: What policies could help narrow the wealth gap?
A: Key solutions include baby bonds (government-funded accounts for children), expanded homeownership programs, fair lending reforms, and closing the racial wage gap. Some economists also argue for reparations discussions to address historical injustices. Without structural changes, the gap will persist.
Q: Is the wealth gap getting worse?
A: Yes. After a slight narrowing post-2008, the gap widened again in the 2010s and 2020s. The pandemic exacerbated the issue, with Black families losing jobs and home equity at higher rates than white families. Without intervention, the gap will continue to grow.
