
Common Myths About Top Shoe Brands Net Worth
The sneaker industry’s financial narrative is cluttered with half-truths. One persistent myth is that top shoe brands net worth can be reliably compared using revenue alone. Nike’s $51 billion in 2023 revenue dwarfs Adidas’s $27 billion, but that ignores Adidas’s higher profit margins in its premium segment or Nike’s aggressive reinvestment in R&D. Another false assumption is that luxury footwear—like Christian Louboutin or Bottega Veneta—generates outsized profits simply by charging premium prices. In reality, these brands often operate on razor-thin margins, with 60–70% of revenue eaten by material costs and supply-chain logistics. Then there’s the streetwear fallacy: the idea that brands like Supreme or Stüssy are worth billions based on secondary-market hype. While resale platforms like StockX and GOAT inflate perceptions, these labels rarely disclose full financials. A Supreme hoodie selling for $1,200 on Grailed doesn’t translate to a $10 billion valuation for the parent company—if it even has one. The confusion deepens when private equity firms acquire minority stakes in heritage brands (e.g., LVMH’s 2021 purchase of Berluti’s parent company) without revealing the full purchase price. The result? A market where perception often outpaces reality.Myth 1: Nike’s Net Worth Is Just Its Publicly Traded Value
Nike’s market capitalization—fluctuating around $150–$200 billion—is the easiest figure to cite. But that only accounts for its publicly traded shares. The company’s top shoe brands net worth extends far beyond Wall Street. Nike’s intellectual property portfolio, including trademarks like "Air" and "Just Do It," is valued in the tens of billions independently. Then there’s its real estate empire: factories in Vietnam, distribution hubs in Memphis, and even a $1.5 billion headquarters in Beaverton. Add in unreported revenue from unconsolidated subsidiaries (like Converse, which Nike acquired for $3.5 billion in 2003 but doesn’t fully integrate into its books), and the true valuation balloons. The problem? Nike’s private assets aren’t audited as a single entity. Analysts at firms like Bernstein estimate Nike’s total enterprise value—including off-balance-sheet IP and real estate—could exceed $300 billion. Yet this figure is speculative. Even Nike’s CFO, Mark Parker, has noted in earnings calls that "our brand value is our most important asset," a statement that underscores how little of it appears on financial statements. The gap between public perception and private reality is where the myth persists.Myth 2: Adidas’s Struggles Mean It’s Losing to Nike
Adidas’s stock has underperformed Nike’s for over a decade, but that doesn’t mean it’s a lesser brand financially. The company’s top shoe brands net worth is propped up by two pillars: its premium segment (Yeezy, Gazelle) and its global sports partnerships. While Nike dominates in North America, Adidas leads in Europe and Asia—regions where football (soccer) culture drives sneaker sales. The 2022 acquisition of Runtastic, a fitness app with 50 million users, hints at Adidas’s shift toward digital monetization, an area Nike is also investing in but hasn’t yet matched in execution. The confusion arises from how Adidas reports its segments. Unlike Nike, which bundles performance and lifestyle under one umbrella, Adidas splits its books into "Originals" (streetwear) and "Sports Performance." This fragmentation makes direct comparisons messy. Industry estimates suggest Adidas’s total brand value—including Originals’ cultural cachet—could rival Nike’s if consolidated differently. The key takeaway? Adidas isn’t losing; it’s playing a different game, one where heritage and regional dominance outweigh pure revenue numbers.Myth 3: Luxury Shoe Brands Are Always Profitable
Hermès’ Birkin bag commands headlines, but its shoes—like the $1,200 leather loafers—are often an afterthought in luxury portfolios. The misconception is that top shoe brands net worth in the luxury tier translates to consistent profitability. In reality, these brands operate on margins as low as 20–30%, with 40% of costs tied to Italian leather and French craftsmanship. Balenciaga’s 2021 shoe collection, for instance, sold out in hours but required years of supply-chain coordination to meet demand. The result? A brand that appears "worth" billions based on retail price tags but may struggle to turn a profit on individual lines. Private equity’s role exacerbates the confusion. When Kering acquired Bottega Veneta in 2016 for $2.5 billion, analysts praised its shoe division—only for the brand to later report declining profits. The issue isn’t valuation; it’s execution. Luxury shoe brands often prioritize exclusivity over scalability, a strategy that works for status but not for balance sheets. The top shoe brands net worth in this segment is less about revenue and more about maintaining an aura of scarcity—one that investors may not fully account for.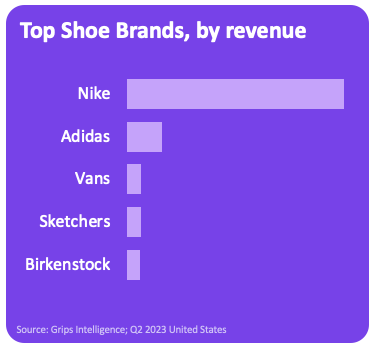
What Holds Up to Scrutiny
Three metrics consistently surface when dissecting top shoe brands net worth: revenue growth, brand equity valuations, and supply-chain control. Revenue is the most transparent—Nike’s $51 billion in 2023 is a fact—but it’s also the most static. Brand equity, however, is where the real story lies. Firms like Interbrand and Brand Finance assign Nike a valuation of $35–$40 billion, while Adidas lags at $15–$20 billion. These figures reflect consumer perception, not just sales. Supply-chain control is the wildcard: Nike owns 70% of its factories, while Adidas relies on third-party manufacturers. That vertical integration is why Nike’s margins (42% in 2023) dwarf Adidas’s (28%). The most reliable indicator? Resale activity. Brands like Nike and New Balance see 30–40% of their sneakers end up on StockX or GOAT, where a pair of Air Jordans might resell for 2x retail. This secondary market isn’t just hype—it’s a barometer of brand loyalty. When top shoe brands net worth is discussed in boardrooms, resale data often carries more weight than quarterly earnings."The sneaker isn’t just a product; it’s a liquid asset. If a brand can’t command resale value, it doesn’t matter how much it’s worth on paper." — Oliver Chen, Partner at Bain & Company (Footwear Practice)
| Common Belief | What the Evidence Says |
|---|---|
| Nike’s worth is its stock price. | Its IP and real estate add $100B+ to its enterprise value. |
| Adidas is losing to Nike. | It leads in Europe/Asia and has higher premium margins. |
| Luxury shoes are always profitable. | Margins are often <30% due to material costs. |
Why the Confusion Persists
The sneaker industry’s financial opacity stems from two factors: private ownership and the intangible nature of brand value. When LVMH acquires Berluti or Richemont snaps up Stuart Weitzman, the purchase prices aren’t disclosed. Analysts rely on proxies—like comparable deals or revenue multiples—but these are educated guesses. Even publicly traded brands like Nike and Lululemon (which entered footwear with its Mirror app) play fast and loose with segment reporting. Nike’s "Direct-to-Consumer" line item, for example, bundles e-commerce, retail stores, and even digital subscriptions—making it hard to isolate shoe-specific performance. Cultural hype further distorts perceptions. A single collaboration—like Nike x Travis Scott—can boost a brand’s stock by 5%, but the financial impact is fleeting. Investors chase trends without always understanding the underlying business. The result? A market where top shoe brands net worth is as much about narrative as it is about numbers. Until brands standardize how they report footwear-specific metrics, the confusion will persist.
Conclusion
The top shoe brands net worth landscape is a study in contrasts. Publicly traded giants like Nike and Adidas offer transparency—but only up to a point. Private labels like Hermès and New Balance operate in shadows, where valuations are whispers. And then there are the disruptors: brands like On Running or Altra, which redefine value through sustainability and performance. The key insight? Top shoe brands net worth isn’t just about revenue or even profit margins. It’s about control—over supply chains, over cultural narratives, and over the intangible equity that turns a shoe into a status symbol. For investors, the lesson is clear: don’t trust headlines. For consumers, the takeaway is simpler: the next sneaker you buy might be worth more than its retail price—if the brand behind it plays the game right.Comprehensive FAQs
Q: Which shoe brand has the highest net worth?
A: Nike leads with an estimated enterprise value exceeding $300 billion when including off-balance-sheet assets like IP and real estate. Adidas follows, with a total valuation around $100–$120 billion, but its premium segment (Yeezy, Gazelle) adds significant intangible value.
Q: How do private shoe brands (like Hermès) compare to public ones?
A: Private brands like Hermès or Berluti don’t disclose full valuations, but industry estimates place Hermès’ total brand value (including shoes) at $50–$60 billion. The challenge? Their financials are opaque—luxury houses often prioritize exclusivity over profitability, making direct comparisons to Nike or Adidas difficult.
Q: Can a sneaker’s resale value affect a brand’s net worth?
A: Absolutely. Brands like Nike and New Balance see 30–40% of their sneakers resold at premiums, which signals strong demand. While resale data isn’t part of official valuations, private equity firms increasingly use it to gauge brand health. A sneaker selling for 2x retail on StockX is a vote of confidence in the brand’s long-term equity.
Q: Why does Adidas’s stock underperform Nike’s if it’s a top brand?
A: Adidas’s stock struggles due to segment fragmentation (splitting Originals and Sports Performance) and slower growth in North America. However, its premium lines (Yeezy, Gazelle) and football (soccer) dominance in Europe/Asia provide strong margins. Analysts argue Adidas is undervalued if its segments were consolidated differently.
Q: Are luxury shoe brands (like Louboutin) more profitable than athletic brands?
A: Not necessarily. Luxury brands operate on thin margins (20–30%) due to high material costs, while Nike’s athletic lines achieve 40%+ margins through vertical integration. Louboutin’s profitability hinges on exclusivity—its shoes rarely go on sale—but that strategy limits scalability compared to mass-market athletic footwear.
Q: How do new brands (like On Running) measure up to established ones?
A: Direct-to-consumer disruptors like On Running (valued at ~$1 billion pre-IPO) rely on sustainability and performance to justify their valuations. While they lack Nike’s revenue, their growth rates (On Running’s 2023 revenue up 50%) and loyal customer bases suggest they’re carving out niche equity. The challenge? Proving long-term profitability in a market dominated by legacy brands.
Q: What’s the biggest financial risk for top shoe brands?
A: Supply-chain disruptions. Nike’s 2020 factory shutdowns in Vietnam cost it $1 billion in lost revenue. Adidas’s reliance on third-party manufacturers exposes it to labor strikes or material shortages. Even luxury brands like Hermès face risks from leather shortages or geopolitical tensions in Italy. The brands that mitigate risk through vertical integration (Nike) or regional diversification (Adidas) tend to outperform.
