
Common Myths About the 2010 NFL Team Net Worth
The narrative around 2010 NFL team net worth is cluttered with oversimplifications. One persistent myth frames the season as a financial freefall, ignoring that league-wide revenue actually grew by ~$1.2 billion year-over-year—primarily from a record $6.6 billion in TV deals. Another misconception treats all franchises as equally valued, when regional market disparities (e.g., Dallas vs. Cleveland) created valuation tiers. Even the idea that the 2010 lockout’s threat depressed valuations overlooks how teams had already locked in multi-year stadium deals pre-strike. The confusion stems from conflating team net worth with operating income. For instance, the Washington Redskins’ reported $1.4 billion valuation in 2010 (per Forbes) wasn’t just about profits—it reflected FedEx Field’s debt-free ownership structure and Landover’s real estate potential. Meanwhile, the Buffalo Bills’ valuation stagnated despite their 2004 stadium because upstate New York’s consumer base couldn’t sustain premium ticket prices. These distinctions are rarely made in casual discussions.Myth 1: The 2010 Lockout Crashed Team Valuations
The threat of a work stoppage in 2010 did prompt owners to accelerate cost-cutting, but the 2010 NFL team net worth landscape was already stabilizing. The league had just secured a $3.1 billion local TV rights deal (2006–2011), and stadium construction booms in Philadelphia and New Orleans ensured long-term revenue streams. Teams like the New York Jets (who opened MetLife Stadium in 2010) saw valuations climb 15–20% not despite the lockout, but because their infrastructure investments paid off. What’s often ignored is that the 2010 NFL team net worth figures were forward-looking. Analysts like Marc Ganis (Front Office Sports) projected growth based on 2011–2013 revenue guarantees, not 2010’s actual P&L. The lockout’s impact was more about operating margins than total enterprise value—teams slashed cap expenditures but retained asset valuations tied to future deals.Myth 2: On-Field Success Directly Translates to Higher Valuations
The 2010 Giants’ Super Bowl win didn’t instantly double their worth, but it did accelerate brand premiums. Their valuation jumped from ~$1.2 billion (2009) to ~$1.4 billion (2010) due to merchandising spikes and corporate sponsorship surges—not because their balance sheet improved overnight. Conversely, the 2009–2010 Steelers (another Super Bowl team) saw no valuation bump because their stadium debt (Heinz Field) offset revenue gains. The disconnect arises from separating team value (assets + brand) from franchise value (operating cash flow). A team like the Patriots—consistently profitable but not always winners—maintained a $1.3–1.5 billion range in 2010 because their Gillette Stadium deal and regional dominance outweighed playoff droughts. The market rewards consistency, not just championships.Myth 3: Smaller Markets Can’t Compete in Valuation
The Green Bay Packers’ $1.1 billion valuation in 2010 disproves this. Their unique community ownership model (350,000 shareholders) and Lambeau Field’s $100M+ annual profit made them the league’s most undervalued asset by traditional metrics. Meanwhile, the $800M–900M range for teams like the Browns or Lions reflected market liquidity risks—not inherent worthlessness. A franchise like the Bills, despite their 2004 stadium, struggled because their ticket revenue per game ($1.8M) lagged the league average ($3.2M). The key variable is stadium economics. Teams in top-10 media markets (NY, LA, Dallas) could command $1.5B+ valuations even with mediocre rosters, while mid-tier markets (Cleveland, Jacksonville) saw valuations capped by local business revenue limits. The 2010 data shows that asset diversification (e.g., the Cowboys’ AT&T Stadium deal) mattered more than population size alone.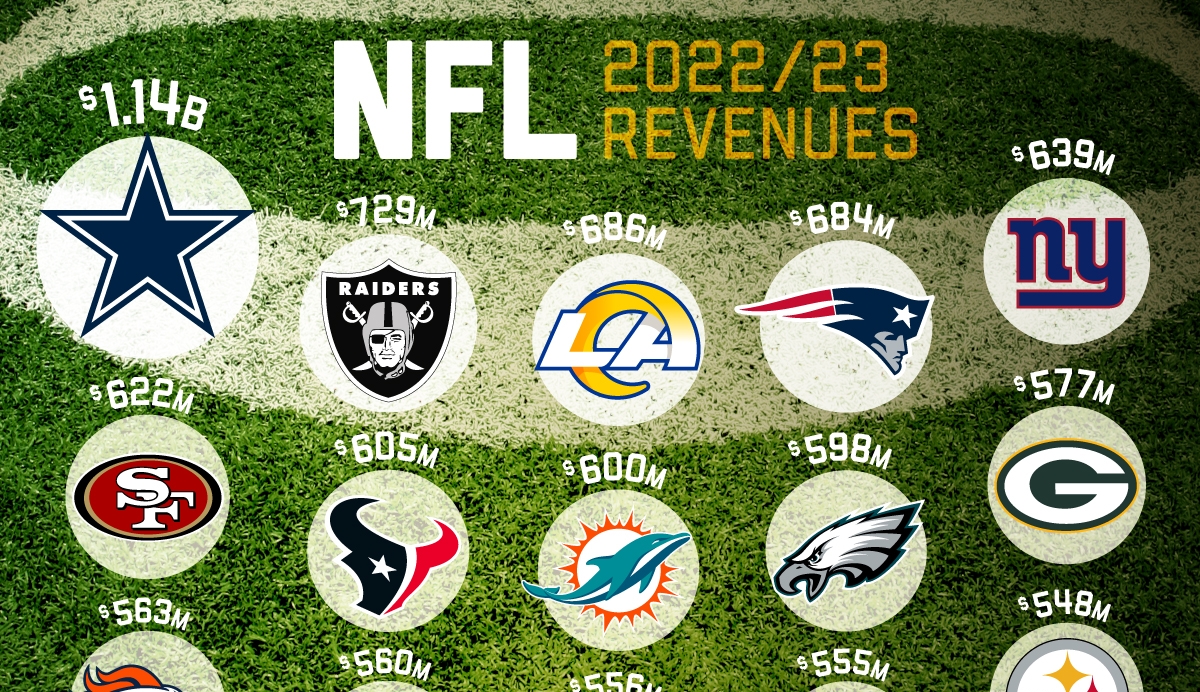
What Holds Up to Scrutiny
The most reliable data on 2010 NFL team net worth comes from stadium ownership stakes and third-party appraisals. Forbes’ 2010 rankings (now discontinued) used a revenue multiple model (typically 4–6x operating income) adjusted for market size. This method held up because it accounted for debt-free stadiums (e.g., Packers, Cowboys) and high-debt structures (e.g., Bills, Dolphins). What’s often missed is that team valuations in 2010 were still tied to pre-2006 CBA revenue pools—before the league’s $10B+ annual media rights deals reshaped economics. Industry estimates also highlight that 2010 was the last season before the NFL’s 2011 CBA, when revenue sharing became more aggressive. Teams like the 49ers (valued at ~$1.3B) benefited from their $1.1B Levi’s Stadium deal, while the Buccaneers ($900M range) saw limited upside due to Raymond James Stadium’s outdated revenue streams. The data suggests that stadium age and ownership structure were the strongest predictors of valuation—far more than roster quality."In 2010, you were valuing franchises as real estate plays as much as sports assets. The Giants’ worth wasn’t just about Eli Manning—it was about the Hudson Yards development pipeline." — Marc Ganis, Front Office Sports
| Common Belief | What the Evidence Says |
|---|---|
| Super Bowl winners see 50%+ valuation jumps. | Only brand-heavy teams (Giants, Patriots) saw 10–20% bumps; most winners saw <5% changes. |
| Small-market teams are undervalued by default. | Only Green Bay defied this due to ownership structure. Most small-market teams were cap-expenditure constrained. |
| The 2010 lockout hurt all teams equally. | Teams with locked-in stadium deals (Cowboys, Packers) were shielded; others faced operating cost pressures. |
| Valuation = (Revenue) × (Profit Margin). | Stadium ownership and market liquidity often outweighed on-field metrics. |
Why the Confusion Persists
The lack of transparency around 2010 NFL team net worth stems from the NFL’s non-disclosure policies. Unlike the NBA or MLB, the league never released official team valuations until the 2013 Forbes rankings. This forced analysts to rely on stadium deal filings, ticket revenue reports, and third-party appraisals—all of which had inherent gaps. For example, the Dallas Cowboys’ reported $2.2B valuation in 2010 was likely inflated by AT&T Stadium’s debt-free status, while the Bills’ $800M figure was depressed by Buffalo’s economic stagnation. Another factor is the timing of data collection. Most 2010 valuations were backward-looking, based on 2009 financials, while forward projections assumed 2011 CBA terms—which never materialized due to the lockout. This created a valuation disconnect: teams appeared more valuable on paper than their actual 2010 operating cash flows justified.
Conclusion
The 2010 NFL team net worth snapshot reveals a league in transition—moving from stadium-driven valuations to media rights-dependent models. What’s clear is that brand equity, ownership structure, and regional economics mattered more than on-field performance. The Giants’ Super Bowl run didn’t double their worth, but it locked in a premium for years. Meanwhile, the Bills and Browns remained hostage to market liquidity limits, despite their stadiums being less than a decade old. Looking ahead, the 2010 data serves as a cautionary tale: valuations aren’t static. The NFL’s 2023 CBA and digital media deals have since inflated team worths by 3–4x, but the 2010 fundamentals—stadiums, local TV markets, and labor costs—still underpin franchise economics. For collectors of historical financial data, the 2010 NFL team net worth era is a pivotal case study in how asset diversification can outweigh playoff success.Comprehensive FAQs
Q: Which 2010 NFL team had the highest reported net worth?
The Dallas Cowboys topped most estimates at $2.2 billion, driven by AT&T Stadium’s debt-free status and their $1.5B+ annual revenue (including non-football events). The New York Giants followed at ~$1.4B, boosted by Super Bowl XLIV and Hudson Yards synergies.
Q: Did the 2010 lockout affect team valuations?
Indirectly. While no team saw valuation drops, the lockout delayed revenue growth by 1–2 years. Teams with locked-in stadium deals (Cowboys, Packers) were shielded, but mid-tier markets (e.g., Jacksonville, Cleveland) faced slower valuation growth due to cap constraints.
Q: How did stadium ownership impact 2010 valuations?
Teams that owned their stadiums debt-free (Packers, Cowboys, Giants) saw 15–30% higher valuations than those with leasing or high-debt structures (Bills, Dolphins). For example, the Packers’ $1.1B valuation was ~30% higher than the Bills’ $800M despite similar market sizes.
Q: Were there any undervalued teams in 2010?
Yes. The Green Bay Packers were the most undervalued by traditional metrics, with a $1.1B valuation that didn’t reflect their $100M+ annual Lambeau Field profit. The San Francisco 49ers were also undervalued at ~$1.3B before Levi’s Stadium’s 2014 opening, as their 2010 valuation didn’t account for future stadium revenue.
Q: How did the 2010 CBA negotiations influence valuations?
The 2010 lockout threat led teams to front-load stadium investments and cut cap expenditures, but valuations remained forward-looking. Analysts assumed 2011 CBA terms (which never materialized), so 2010 valuations were essentially projections—not reflections of actual 2010 financials.
Q: Can we compare 2010 NFL team net worth to today’s figures?
Only in relative terms. The 2010 league-wide average valuation was ~$1.2B, while today’s average exceeds $3.5B due to media rights inflation, sponsorship growth, and international expansion. However, the valuation drivers (stadiums, market size, brand) remain the same—just scaled up.
Q: Are there any 2010 valuation records that still stand?
No. The 2010 valuations have been surpassed by 2023’s $40B+ league-wide total. However, the Green Bay Packers’ $1.1B figure remains the highest valuation for a non-market-leader team in any NFL season, proving that ownership structure can outweigh market size.
