The Complete Overview of Gaming Companies Net Worth
The landscape of gaming companies net worth has evolved from a niche curiosity to a global economic benchmark. In 2023, the top 20 gaming publishers collectively generated over $160 billion in revenue, with the industry’s gross valuation—when factoring in private equity, acquisitions, and unlisted firms—easily surpassing $1 trillion. This isn’t just about blockbuster titles or AAA studios; it’s about the entire ecosystem, from cloud gaming infrastructure to esports teams that operate like sports franchises. The shift toward live-service games has redefined what constitutes "value." A title like Fortnite doesn’t just earn money from sales; it monetizes through microtransactions, concerts, and even real-world merchandise, creating a self-sustaining economy that traditional valuations struggle to capture. Meanwhile, the rise of mobile gaming has democratized entry points, allowing studios like gaming companies net worth darlings such as Genshin Impact’s MiHoYo to achieve unicorn status without relying on console exclusives. What makes this sector unique is its volatility. A single misstep—like a failed live-service update or a regulatory crackdown—can erase billions in perceived worth overnight. Take Zynga, once valued at $12 billion in 2011, now trading at a fraction of that after struggling to adapt to mobile gaming’s maturation. Conversely, gaming companies net worth in the esports space have seen explosive growth, with teams like TSM (Tournament Streamers Management) reportedly valued at over $100 million, driven by sponsorships and media rights deals. The key variable isn’t just revenue but asset liquidity—how easily a company’s IP, user base, or tech can be monetized in secondary markets. This is why companies like Epic Games, with its Unreal Engine and Fortnite franchise, command valuations that dwarf traditional publishers. The equation has changed: it’s no longer about selling games, but owning the platforms that sell attention.Historical Background and Evolution
The modern era of gaming companies net worth began in the late 1990s, when Electronic Arts (EA) became the first gaming company to surpass $1 billion in revenue. At the time, the industry was still tied to physical media, and valuations were straightforward: multiply unit sales by average price. But the real inflection point came with the rise of digital distribution. Valve’s Steam platform, launched in 2003, didn’t just change how games were sold—it created a secondary market where gaming companies net worth could be indirectly measured by trade-in values and mod economies. This was the first hint that gaming was becoming a service economy, not just a product one. By 2010, the acquisition of Myspace by News Corp. for $580 million—followed by its almost immediate devaluation—served as a cautionary tale for gaming companies chasing social media hype. The lesson? Gaming companies net worth was about recurring revenue, not one-off hits. The 2010s saw the next seismic shift: the mobile gaming boom and the birth of live-service models. Supercell’s Clash of Clans became a case study in how a single game could generate $1 billion+ in lifetime revenue, propelling its parent company to a valuation exceeding $10 billion. Meanwhile, Tencent’s aggressive acquisition strategy—buying stakes in Epic, Riot, and even a minority share in Activision—transformed it into the world’s most valuable gaming company by gaming companies net worth, with figures often exceeding $300 billion in private markets. The esports explosion further blurred the lines between gaming and traditional sports, with teams like Cloud9 and Fnatic securing valuations that rivaled those of minor-league sports franchises. Today, the industry’s valuation isn’t just about games; it’s about ecosystems—where a company’s worth is tied to its ability to integrate hardware, software, and social platforms into a single, monetizable experience.Core Mechanisms: How It Works
The valuation of gaming companies net worth hinges on three pillars: recurring revenue models, IP scalability, and platform control. Recurring revenue—whether through subscriptions (Xbox Game Pass), battle passes (Apex Legends), or in-game purchases (Genshin Impact)—creates predictable cash flows that investors favor. This is why companies like Microsoft, with its $70 billion acquisition of Activision Blizzard, aren’t just buying games; they’re buying long-term subscription pipelines. IP scalability refers to a company’s ability to repurpose its assets across multiple mediums. Take Call of Duty: its IP extends to movies, documentaries, and even fitness apps, each adding layers to its valuation. Platform control is the wild card. Companies like Sony (with PlayStation) and Nintendo (with Switch) derive significant value from hardware sales, but even software-focused firms like Epic now leverage their engines (Unreal) as revenue streams. The result? A valuation model that’s part tech stock, part media conglomerate, and part gambling operation, where future bets on unproven IP can swing worth by billions. The dark side of this model is its opacity. Many gaming companies net worth—especially in Asia—operate with minimal financial disclosures, relying on private equity rounds to set valuations. This creates a two-tiered market: publicly traded firms like Take-Two Interactive (makers of Grand Theft Auto) must adhere to SEC reporting, while private studios like gaming companies net worth leader MiHoYo can adjust valuations based on investor whims. The rise of blockchain gaming adds another layer of complexity. Projects like Axie Infinity’s $4.3 billion valuation in 2021 were as much about speculative token economics as they were about gameplay. When the market corrected, so did those valuations, proving that gaming companies net worth in the Web3 space is as volatile as cryptocurrency itself.Key Benefits and Crucial Impact
The financial might of gaming companies net worth extends beyond balance sheets, reshaping global economies. In South Korea, gaming revenue accounts for nearly 1% of GDP, while in China, Tencent’s ecosystem supports millions of jobs across development, streaming, and esports. The industry’s ability to generate high-margin revenue—with mobile games often boasting 40%+ profit margins—makes it a magnet for investors. For developers, this means access to capital previously unimaginable, but it also means consolidation risk. Smaller studios face pressure to either sell out to larger publishers or pivot to live-service models to stay relevant. The impact on culture is equally profound: gaming has become a global lingua franca, with titles like League of Legends and Among Us transcending language barriers. This cultural dominance translates into brand value, where a studio’s worth isn’t just in its games but in its ability to shape trends. The downside? The same forces that inflate gaming companies net worth can also create monopolistic tendencies. Epic’s legal battle with Apple over app store fees, or Microsoft’s near-monopoly on console gaming after its Activision deal, highlight how concentration risks stifling innovation. Yet for the industry’s stakeholders—developers, investors, and even governments—the benefits often outweigh the risks. Gaming is now a strategic asset, with nations like Japan and South Korea actively courting studios to boost their tech sectors. The question isn’t whether gaming companies net worth will keep rising, but how quickly—and at what cost."Gaming isn’t just an industry anymore. It’s an economic operating system—one that’s rewriting the rules of entertainment, finance, and even geopolitics." — Mark Rein, former Microsoft executive
Major Advantages
- Recurring revenue dominance: Live-service games and subscriptions create predictable cash flows, making gaming companies net worth more stable than traditional software firms.
- IP as liquid asset: Franchises like Fortnite or Minecraft can be licensed, adapted, and monetized across multiple mediums, increasing valuation.
- Global scalability: Unlike film or music, gaming has low localization costs, allowing studios to expand into emerging markets with minimal overhead.
- Cross-industry synergies: Gaming companies now intersect with esports, streaming, and even fitness, diversifying revenue streams.
- Investor appetite: With tech valuations at a premium, gaming’s high-margin model makes it a safe bet in uncertain markets.
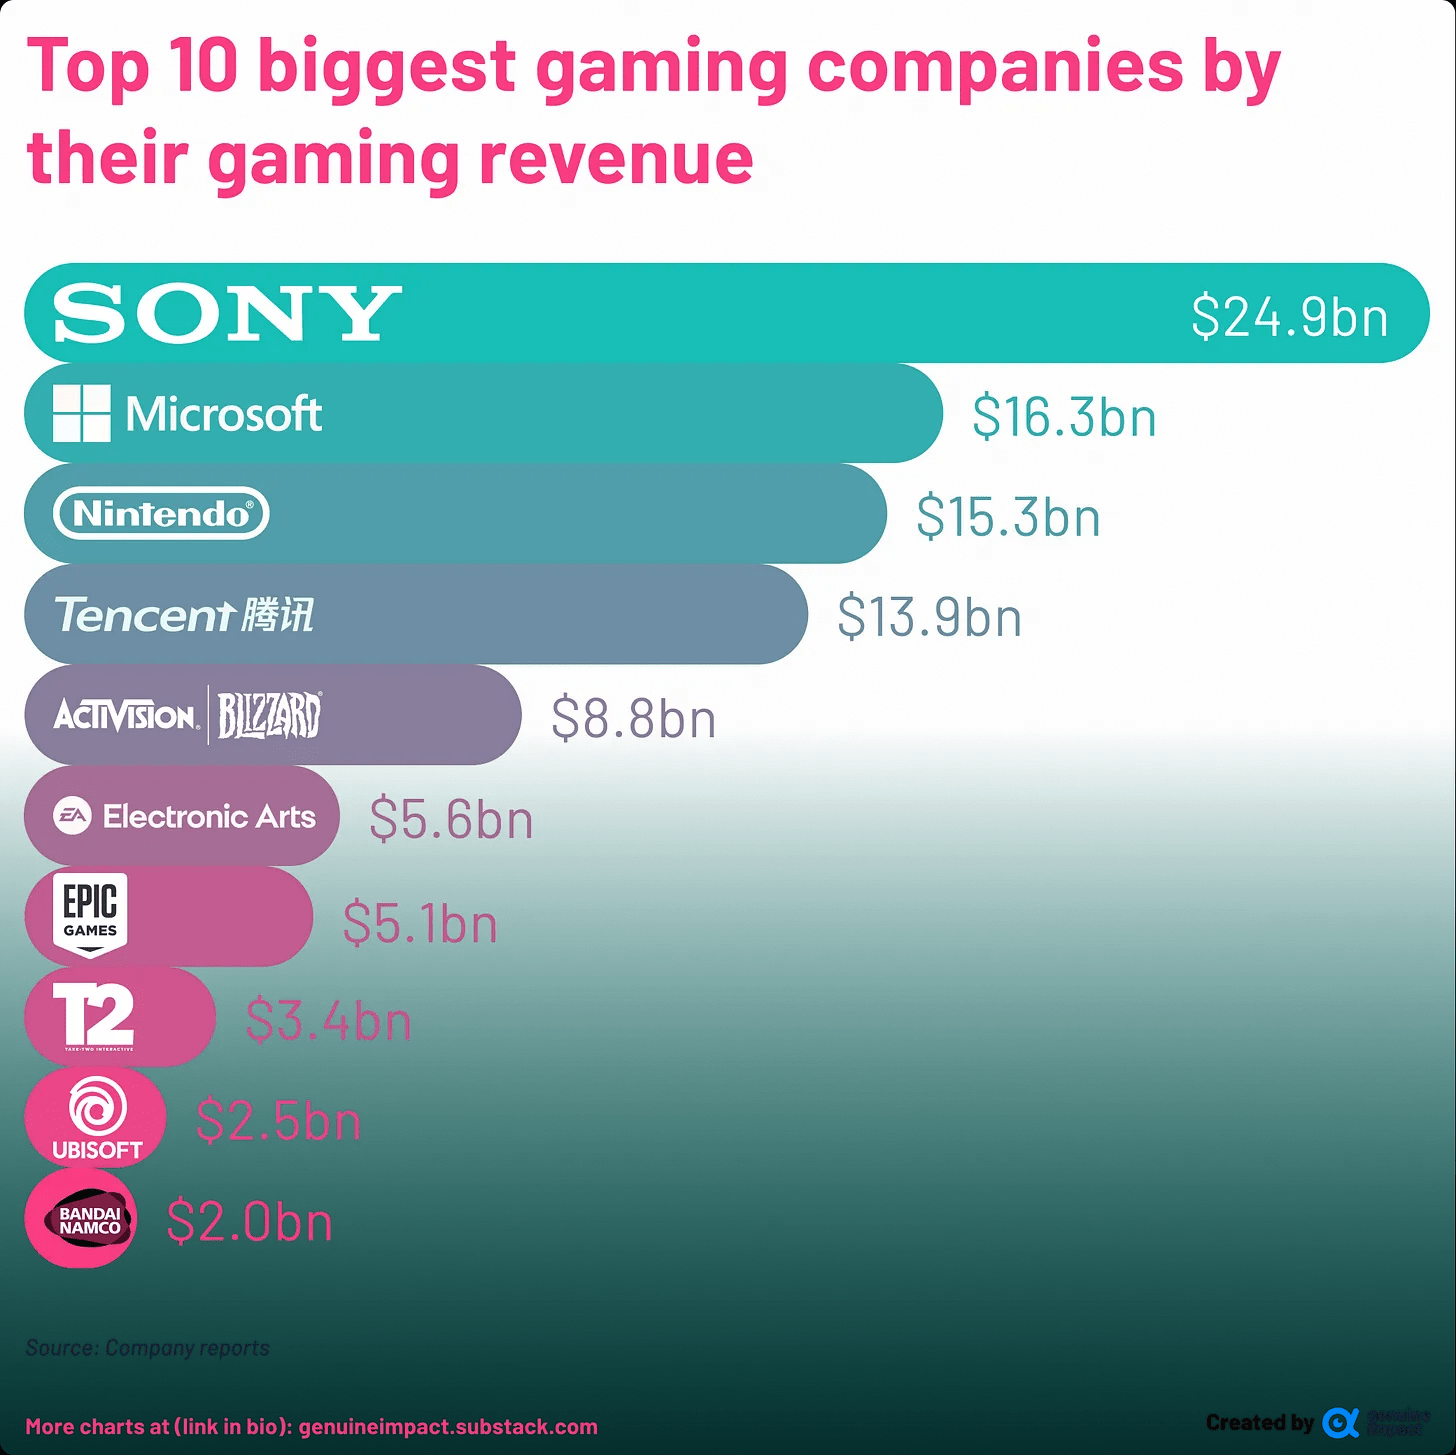
Comparative Analysis
| Company | Key Valuation Drivers |
|---|---|
| Tencent | Ownership stakes in Riot, Epic, Supercell; mobile gaming dominance in Asia; esports investments. |
| Microsoft (post-Activision) | Console hardware (Xbox), cloud gaming (Xbox Cloud), and live-service IP (Call of Duty, Diablo). |
| Sony | PlayStation hardware sales, exclusive IP (God of War, The Last of Us), and high-margin third-party deals. |
| Nintendo | Switch hardware profitability, niche but loyal fanbase, and merchandising synergy (Animal Crossing, Mario). |
Future Trends and Innovations
The next frontier for gaming companies net worth lies in AI-driven development and metaverse integration. Tools like Unity’s AI-assisted design or NVIDIA’s Omniverse are poised to slash production costs, allowing smaller studios to compete with AAA budgets. This could democratize gaming companies net worth, but it also risks further consolidation as only the largest firms can afford the R&D. The metaverse—often dismissed as hype—may yet become a valuation multiplier. Companies like Roblox and Epic are already betting on virtual economies where user-generated content creates self-sustaining revenue. If successful, these platforms could redefine gaming companies net worth by shifting value from game sales to digital real estate. The wildcard remains regulatory scrutiny: as gaming’s financial power grows, so does the risk of antitrust actions or revenue-sharing crackdowns, which could destabilize current valuation models. One certainty? The line between gaming and other industries will blur further. We’re already seeing gaming companies net worth intersect with fashion (virtual clothing in Fortnite), finance (play-to-earn models), and even education (gamified learning platforms). The companies that thrive will be those that own the infrastructure, not just the content—whether that’s cloud servers, AI tools, or social platforms. For now, the race is on to monetize attention in ways we’ve only begun to imagine.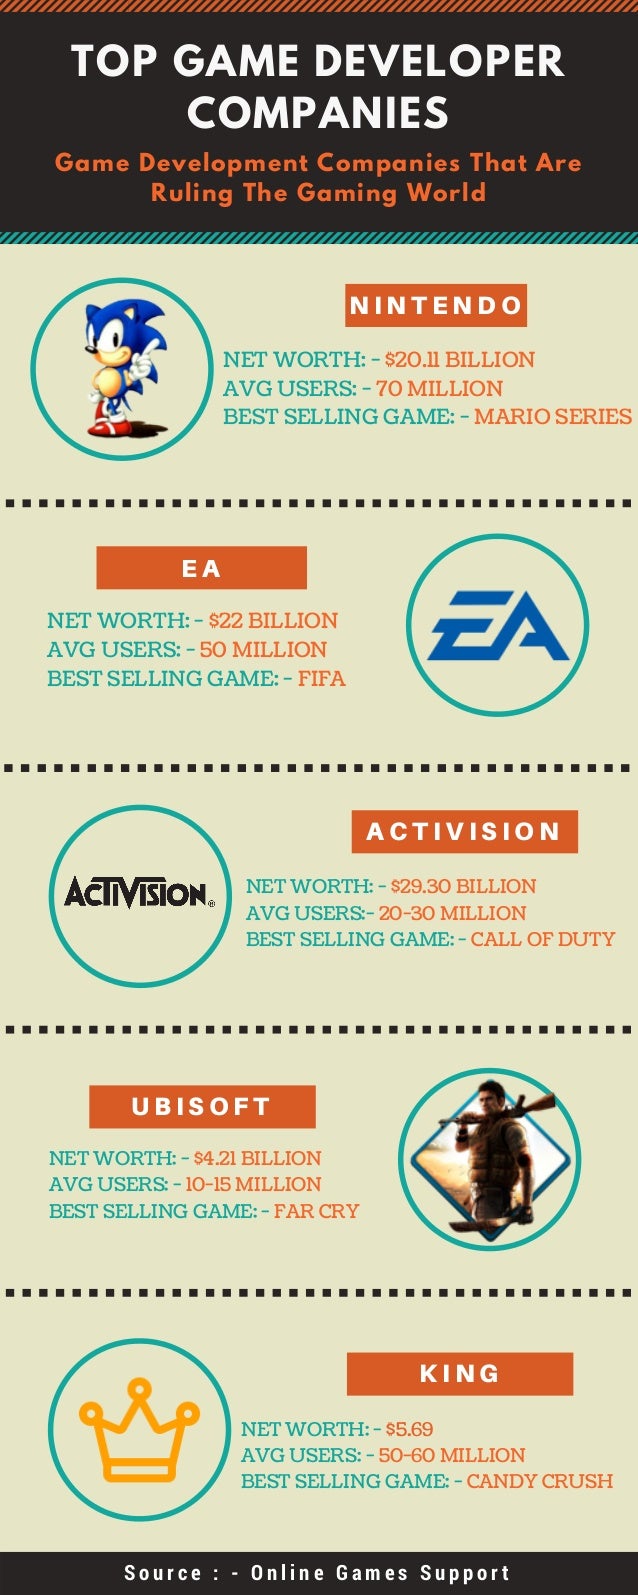
Conclusion
The story of gaming companies net worth is one of exponential growth masked by volatility. What was once a niche hobby has become a trillion-dollar juggernaut, where a single studio’s valuation can swing based on a tweet, a regulatory ruling, or a viral meme. The industry’s resilience—its ability to reinvent itself from arcades to cloud gaming—is its greatest strength, but also its Achilles’ heel. As consolidation deepens and new technologies emerge, the question isn’t whether gaming companies net worth will keep rising, but who will control the levers that determine those valuations. The answer may lie not in bigger budgets, but in smarter ecosystems—where a studio’s worth isn’t just in its games, but in its ability to own the future of play. For investors, developers, and policymakers alike, the takeaway is clear: gaming isn’t just another industry. It’s a financial and cultural force that demands a new way of thinking about value. The companies that navigate this landscape will write the next chapter in an industry where billions aren’t just made—they’re redefined.Comprehensive FAQs
Q: How do private gaming companies (like MiHoYo) determine their net worth without public financials?
A: Private gaming companies net worth are typically assessed through private equity rounds, where investors evaluate metrics like user growth, retention rates, and monetization efficiency. Valuations are often based on comparables—how much similar companies (e.g., Supercell, Genshin Impact’s peers) have raised in recent funding rounds. Analysts also consider IP potential, such as a game’s ability to cross into merchandise or esports, which can inflate perceived worth without traditional revenue proof.
Q: Why did Zynga’s net worth plummet after its 2011 peak, while Supercell’s kept rising?
A: Zynga’s decline stemmed from over-reliance on Facebook’s walled garden and failure to adapt to mobile gaming’s maturation. Its games (FarmVille) became oversaturated, and its monetization models grew stale. Supercell, meanwhile, mastered mobile’s long-tail economics: Clash of Clans and Clash Royale thrived by balancing free-to-play accessibility with high-margin microtransactions, while Zynga’s titles struggled with paywalls and fatigue. Supercell’s ability to reinvest profits into R&D also kept it ahead of competitors.
Q: Can indie developers realistically achieve unicorn status like gaming companies net worth giants?
A: While rare, it’s not impossible—if they leverage niche markets or viral moments. Among Us’s creators, Innersloth, reportedly turned down a $200 million offer, proving that organic community-driven growth can rival traditional funding. However, most indies rely on crowdfunding (Kickstarter), publisher deals, or live-service pivots to scale. The key is scalable IP: a game like Stardew Valley succeeds because its modding community and merchandise extend its lifespan, much like AAA studios—but without the budget.
Q: How does esports impact gaming companies net worth compared to traditional gaming revenue?
A: Esports adds three valuation layers: 1. Sponsorships & media rights (e.g., Riot’s League of Legends World Championship generates hundreds of millions in ad revenue). 2. Team valuations (TSM, Fnatic, and others are now traded like sports franchises, with valuations exceeding $100M). 3. Live-service synergy (games like Valorant or Fortnite use esports to drive player engagement, boosting in-game purchases). For companies like gaming companies net worth leader Tencent, esports is a growth engine, while for indies, it’s often a secondary revenue stream—unless they strike a major deal (e.g., Rocket League’s esports integration).
Q: What’s the biggest risk to gaming companies net worth in the next 5 years?
A: Regulatory backlash and market saturation pose the greatest threats. - Antitrust scrutiny (e.g., Microsoft’s Activision deal, Apple’s app store fees) could force asset divestitures, slashing valuations. - Live-service fatigue (players growing tired of grind-heavy games) may push studios toward shorter, high-quality releases, disrupting recurring revenue models. - Blockchain gaming’s collapse (if play-to-earn models fail) could drain speculative valuations from projects like Axie Infinity. The wild card? AI-generated content—if tools like Unity’s AI design make human-led development obsolete, mid-tier studios may struggle to compete, accelerating consolidation.
