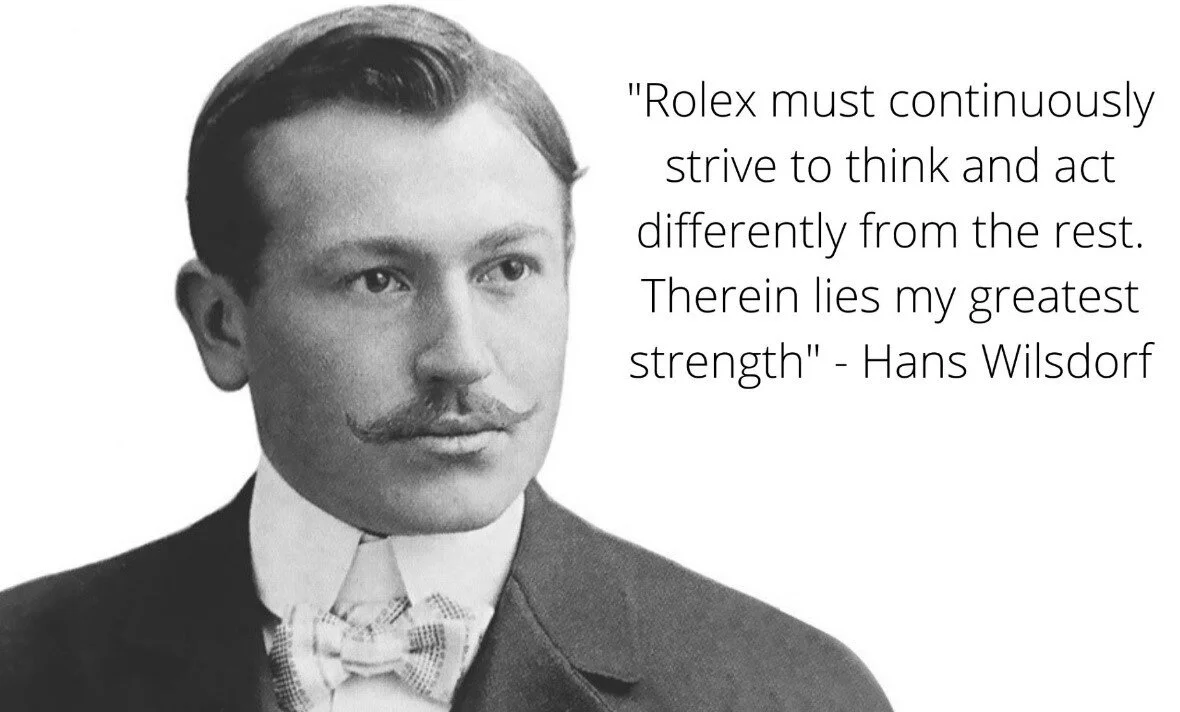
The Complete Overview of Hans Wilsdorf’s Financial Legacy
Hans Wilsdorf’s financial genius wasn’t in amassing personal wealth but in designing a business that amasses it indefinitely. His 1908 relocation of Wilsdorf & Davis to Geneva—renamed Rolex in 1919—was a masterstroke. Switzerland’s political neutrality, skilled labor pool, and lack of luxury taxes created an ideal environment for a company that would later become the world’s most profitable watchmaker. By 1931, Rolex had perfected the self-winding mechanism, a patent that extended its technical lead for decades. These innovations weren’t just technological; they were financial. Each patent and design refinement increased the barrier to entry for competitors, ensuring Rolex’s market dominance and, by extension, the hans wilsdorf net worth 2022 potential of his successors. The Rolex model differs fundamentally from publicly traded luxury brands. While companies like LVMH or Richemont rely on quarterly earnings reports, Rolex operates as a private family trust, with shares held by the Wilsdorf heirs and a small circle of investors. This structure shields the company from speculative volatility while allowing it to reinvest profits into R&D and marketing. In 2022, Rolex’s revenue was estimated at $12 billion, with net profits nearing $4 billion—figures that dwarf those of its publicly listed peers. The key to understanding the hans wilsdorf net worth 2022 equivalent lies in recognizing that his descendants’ stake in this machine is their primary (and largely untraceable) asset. Unlike modern entrepreneurs who diversify into tech or real estate, the Wilsdorf family’s wealth remains concentrated in a single, hyper-lucrative enterprise.Historical Background and Evolution
Wilsdorf’s early years in Hamburg and London were marked by financial pragmatism. After failing to secure funding for his watch designs in Germany, he moved to London in 1905, where he partnered with Alfred Davis to establish Wilsdorf & Davis. Their first major breakthrough came in 1908 with the Wilsdorf Perpetual, the first wristwatch with a self-winding mechanism—a patent that would later become a cornerstone of Rolex’s technical superiority. By 1910, the company had relocated to Switzerland, a decision that would prove critical. The Swiss franc’s stability, combined with the country’s reputation for precision engineering, made it the ideal base for a luxury brand. Wilsdorf’s insistence on Swiss manufacturing wasn’t just about quality; it was a strategic move to align the brand with a currency that would appreciate over time, indirectly boosting the hans wilsdorf net worth 2022 potential of future generations. The 1920s and 1930s solidified Rolex’s financial foundation. Wilsdorf’s 1926 patent for the Oyster case—the first waterproof wristwatch—created a new category of luxury goods. The marketing campaign that followed was revolutionary: Rolex sponsored deep-sea diving expeditions, associating its watches with extreme durability and elite status. By 1931, the company had introduced the self-winding movement, a technology that would remain proprietary for decades. These innovations weren’t just technical feats; they were financial moats. Each patent extended Rolex’s lead, reducing competition and ensuring premium pricing power. By the time Wilsdorf died in 1960, Rolex’s annual revenue had surpassed £1 million, and his heirs inherited a company that would only grow in value—a legacy that would see the hans wilsdorf net worth 2022 equivalent today exceed $10 billion if his shares were liquidated.Core Mechanisms: How It Works
Rolex’s financial model operates on three pillars: exclusivity, technical leadership, and vertical integration. Exclusivity is enforced through limited production. Rolex manufactures fewer than 2 million watches annually, despite demand that often exceeds supply. This scarcity drives secondary market prices, where vintage Rolex pieces now fetch $50,000–$1 million+ at auction. Technical leadership is maintained through patents and in-house manufacturing. Rolex produces its own movements, cases, and even certain components like screws—a vertical integration strategy that ensures quality control and eliminates supplier dependencies. This self-sufficiency also protects margins, with gross profit margins consistently above 90%. The third pillar is brand equity. Rolex doesn’t rely on mass advertising; instead, it cultivates an aura of prestige through subtle cultural association. Celebrities like James Bond (who wore a Rolex in Dr. No) and athletes like Roger Federer become unwitting ambassadors. This organic marketing reduces customer acquisition costs while increasing lifetime value. The result is a business that requires minimal debt—Rolex’s leverage ratio is among the lowest in the luxury sector—and generates $5,000+ in profit per watch. For the Wilsdorf heirs, this model translates into a passive income stream that compounds annually, with the hans wilsdorf net worth 2022 equivalent today being a function of Rolex’s enterprise value rather than any single transaction.Key Benefits and Crucial Impact
The Wilsdorf family’s financial advantage stems from owning a business that doesn’t just sell products but creates liquidity through brand appreciation. Unlike stocks or real estate, Rolex watches retain or increase in value over time. A 1950s Rolex Submariner, for example, now sells for 10–20 times its original retail price. This secondary market effect is a direct result of Wilsdorf’s original strategy: treating watches as collectible assets. The family’s wealth is thus tied to a dual revenue stream—primary sales and vintage resale—which ensures upward pressure on the hans wilsdorf net worth 2022 equivalent. Rolex’s ability to command premium prices is also a function of its monopoly-like position in the ultra-luxury segment. While competitors like Patek Philippe or Audemars Piguet target niche audiences, Rolex dominates the $5,000–$20,000 range, where demand is highest. This pricing power allows the company to weather economic downturns—Rolex’s revenue grew 10% annually even during the 2008 financial crisis. For the Wilsdorf heirs, this stability means their stake in Rolex is a hedge against inflation, with the brand’s value appreciating alongside global luxury trends."A Rolex is the only watch that appreciates like fine art." — Philippe puff, vintage watch dealer (2021)
Major Advantages
- Asset appreciation: Rolex watches are the only consumer goods where secondary market values consistently outpace inflation. A 1970s Daytona now sells for $100,000+, up from its original $2,000 retail price.
- Tax efficiency: Rolex’s private ownership structure avoids capital gains taxes on share appreciation, unlike publicly traded luxury stocks.
- Global demand elasticity: Rolex’s brand equity ensures demand remains strong even in recessionary periods, unlike cyclical industries.
- Technical moat: In-house manufacturing and proprietary movements create barriers to entry that competitors cannot replicate.
- Passive income: The Wilsdorf family earns dividends from Rolex’s annual profits without needing to sell shares, preserving their stake.
Comparative Analysis
| Metric | Rolex (Wilsdorf Legacy) | Public Luxury Peers (LVMH/Richemont) |
|---|---|---|
| Ownership Structure | Private family trust | Publicly traded |
| Gross Margin | 90%+ | 60–70% |
| Secondary Market Value | Appreciates over time | Depreciates or stagnates |
Future Trends and Innovations
Rolex’s financial model faces two major challenges in the 2020s: digital disruption and regulatory pressure. The rise of smartwatches has led to a 10% decline in traditional watch sales since 2015, though Rolex has mitigated this by positioning itself as a status symbol rather than a functional device. Their 2022 Cellini collection, blending traditional craftsmanship with minimalist design, signals an attempt to appeal to younger buyers without compromising exclusivity. Regulatory risks—particularly in China, where luxury taxes are rising—could also impact margins, though Rolex’s global distribution network reduces single-market dependency. On the innovation front, Rolex is doubling down on heritage marketing. The 2022 reissue of the GMT-Master II "Paul Newman" sold out in hours, proving that nostalgia drives demand. Additionally, the company’s investment in AI-driven supply chain optimization could further reduce costs, boosting the hans wilsdorf net worth 2022 equivalent by improving operational efficiency. If Rolex successfully bridges the gap between analog tradition and digital-savvy consumers, its enterprise value—and thus the Wilsdorf family’s stake—could see double-digit growth by 2030.
Conclusion
Hans Wilsdorf’s financial legacy is a study in patient capitalism. Unlike modern entrepreneurs who chase quarterly growth, he built a business designed to appreciate over generations. The hans wilsdorf net worth 2022 equivalent isn’t a static number but a compounding asset, with Rolex’s brand value acting as the ultimate wealth multiplier. His heirs didn’t inherit a company; they inherited a self-perpetuating machine, one that converts time itself into financial returns. In an era where private equity and tech startups dominate headlines, Wilsdorf’s model remains a masterclass in sustainable luxury. The lesson for modern business is clear: true wealth isn’t measured in IPOs or stock options but in creating assets that appreciate independently of market cycles. Rolex’s ability to charge $10,000 for a watch while maintaining a 90%+ margin is a testament to Wilsdorf’s foresight. For the Wilsdorf family, the hans wilsdorf net worth 2022 isn’t just about numbers—it’s about controlling a brand that turns every tick of the clock into profit.Comprehensive FAQs
Q: Is there a public record of Hans Wilsdorf’s personal net worth?
A: No. Wilsdorf died in 1960, and Rolex’s private ownership structure means his financial details were never disclosed. Estimates of his hans wilsdorf net worth 2022 equivalent focus on his descendants’ stake in Rolex, which is valued in the multi-billion range based on enterprise multiples.
Q: How do the Wilsdorf heirs benefit from Rolex’s success today?
A: The Wilsdorf family holds a majority stake in Rolex through a private trust. Their income comes from dividends, capital appreciation, and occasional liquidity events (e.g., selling shares to institutional investors). Unlike public shareholders, they avoid tax burdens on share sales, preserving their stake’s long-term value.
Q: Why doesn’t Rolex go public like LVMH or Richemont?
A: Rolex’s private status allows the Wilsdorf family to avoid short-term market pressures and maintain full control over branding, pricing, and expansion. Public listing would expose the company to speculative trading, which could destabilize its premium positioning—a risk Wilsdorf’s successors have consistently avoided.
Q: Are there any financial risks to Rolex’s model?
A: Yes. Key risks include digital competition (smartwatches), geopolitical instability (e.g., China’s luxury tax hikes), and supply chain disruptions (e.g., Swiss watchmaking labor shortages). However, Rolex’s brand equity and vertical integration mitigate most of these threats, ensuring the hans wilsdorf net worth 2022 equivalent remains resilient.
Q: How does Rolex’s secondary market affect the Wilsdorf family’s wealth?
A: The secondary market boosts Rolex’s perceived value, creating a feedback loop where vintage models appreciate. This increases the enterprise value of the company, which directly benefits the Wilsdorf heirs as majority shareholders. For example, a 1950s Rolex Submariner selling for $200,000 at auction indirectly raises Rolex’s brand valuation, enhancing the family’s stake.
