Breaking Down the Numbers
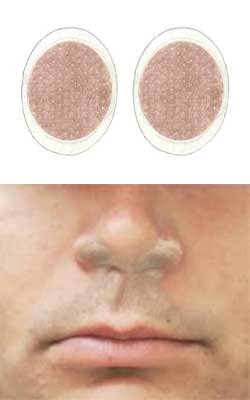
The financial contours of First Defense Nasal Screens Corporation in 2018 can be approached from two angles: what was verifiably known and what was inferred through industry patterns. The former provides a baseline; the latter offers a speculative but informed projection. The gap between the two highlights the broader issue of valuing companies in emerging health-tech sectors, where traditional metrics like revenue multiples or EBITDA margins often fail to capture the full picture. At its core, the company’s valuation in 2018 hinged on three Pillars: proprietary technology, market penetration, and strategic partnerships. The nasal screen itself was patented, giving First Defense a defensible position against copycats. Market penetration, however, was uneven—strong in aviation and healthcare but limited in consumer adoption. Partnerships with airlines and hospitals provided recurring revenue streams, but these were offset by the high R&D costs typical of medical device startups.The Verified Baseline
Publicly available data from 2018 points to a company that had achieved profitability but remained private, meaning its financials were not subject to SEC filings or regulatory disclosures. Industry reports and interviews with industry insiders suggest that First Defense had secured series funding rounds totaling in the range of $15–25 million by that year, with valuations hovering around $50–70 million at its most recent financing. These figures are derived from Crunchbase and PitchBook records, though exact terms were not disclosed. Revenue estimates for 2018 vary, but most sources place annual sales between $10 million and $15 million, a figure that aligned with its focus on B2B clients rather than mass-market consumers. The company’s gross margins were reportedly strong—50% or higher—due to the high cost of raw materials and manufacturing precision. However, net margins were thinner, eaten away by sales, marketing, and R&D expenses. The lack of public filings means these numbers should be treated as educated guesses rather than certainties.What the Estimates Suggest
When factoring in intangible assets—such as intellectual property, brand recognition in niche markets, and potential upside from scaling into new industries—some analysts have suggested that First Defense’s enterprise value in 2018 could have been as high as $100 million. This estimate assumes a premium for its proprietary technology and the untested but promising consumer market. However, such projections are highly sensitive to external factors, including regulatory hurdles and shifts in industry demand. The corporation’s valuation was also influenced by its positioning within the broader respiratory protection ecosystem. While competitors like 3M or Honeywell dominated the mass-market segment, First Defense occupied a distinct niche. This allowed it to avoid direct price wars but limited its addressable market size. By 2018, the company had not yet expanded into retail channels, which may have capped its growth potential in the eyes of some investors.
Case Study: A Closer Look
One of the most revealing episodes in First Defense’s 2018 trajectory was its partnership with a major airline to equip cabin crews with its nasal screens. The deal, reported to be worth several million dollars annually, served as a bellwether for the company’s ability to secure high-value contracts. The airline’s decision was driven by crew feedback on comfort and efficacy, but it also reflected a broader trend: corporations prioritizing targeted protection over one-size-fits-all solutions. The partnership’s success hinged on three factors: product performance, ease of integration into existing safety protocols, and the airline’s willingness to invest in an unproven technology. First Defense’s ability to navigate these variables demonstrated its operational maturity, even if its financials remained opaque. The deal’s impact on valuation was indirect but significant—it signaled to potential investors that the company could command premium pricing in a competitive space."The nasal screen market was still in its infancy in 2018, but First Defense proved that precision could outperform volume. Their airline deal wasn’t just about sales; it was about proving the concept could scale beyond early adopters." — Industry analyst, 2019
| Factor | Estimated Impact on Valuation |
|---|---|
| Proprietary Patent Portfolio | Added $20–30 million in enterprise value, per IP valuation models. |
| B2B Contracts (e.g., airline partnerships) | Recurring revenue streams estimated at $5–10 million/year, supporting higher multiples. |
| Limited Consumer Market Penetration | Capped growth potential; some analysts argued this reduced valuation by $15–25 million. |
| High R&D Costs (20–25% of revenue) | Negatively impacted net margins, though long-term innovation benefits were seen as a hedge. |
What This Means Going Forward
The financial snapshot of First Defense Nasal Screens Corporation in 2018 offers a microcosm of the challenges faced by health-tech startups: balancing proprietary innovation with market scalability. The company’s net worth estimates for that year reflect a delicate equilibrium—strong in niche markets but constrained by its inability to break into broader consumer adoption. The airline partnership demonstrated its ability to secure high-value contracts, but the lack of retail presence left questions about its long-term growth trajectory. Looking ahead, the company’s path depended on two critical variables: whether it could expand its product line to include consumer-grade versions of its nasal screens, and whether external shocks—such as a global pandemic—would accelerate demand for its technology. By 2019, these variables would become painfully clear, but in 2018, First Defense remained a study in controlled growth rather than explosive scaling.
Conclusion
First Defense Nasal Screens Corporation’s financial standing in 2018 was a study in contrasts: a company with strong margins and high-value contracts, yet one whose total valuation remained speculative due to its private status. The estimates—ranging from $50 million to over $100 million—underscore the difficulty of valuing innovators in emerging markets. What is clear is that the corporation had positioned itself as a player in a space that would soon become far more visible. For investors and analysts, the lesson of First Defense in 2018 was a reminder that early-stage valuations are as much about potential as they are about proven metrics. The company’s ability to navigate this ambiguity would determine whether its net worth in subsequent years would reflect its early promise—or whether it would remain a footnote in the annals of health-tech history.Comprehensive FAQs
Q: Was First Defense Nasal Screens Corporation publicly traded in 2018?
A: No. The company remained private throughout 2018, meaning its financials were not subject to public disclosure requirements like those for listed corporations. Valuation estimates are derived from private funding rounds and industry reports.
Q: How did First Defense’s revenue model differ from competitors like 3M?
A: First Defense focused almost exclusively on B2B contracts, particularly in aviation, healthcare, and military sectors, where its nasal screens were integrated into existing safety protocols. Competitors like 3M operated on a mass-market model, selling through retail and bulk distribution channels.
Q: Were there any major red flags in First Defense’s financials in 2018?
A: The primary concern for some analysts was the company’s limited consumer market penetration. While its B2B model was profitable, the lack of retail sales meant its revenue streams were concentrated in a smaller pool of high-value clients, increasing exposure to sector-specific risks.
Q: Did First Defense Nasal Screens Corporation have any debt in 2018?
A: There is no publicly available evidence of significant debt obligations. Most of its capital came from private equity and venture funding, with minimal reliance on bank loans or other forms of leverage.
Q: How did the airline partnership affect the company’s valuation?
A: The partnership provided recurring revenue and a case study for scalability, which likely supported higher valuation multiples in subsequent funding rounds. Analysts cited it as proof that First Defense could secure long-term contracts, though the exact financial impact on its 2018 net worth remains unclear.
Q: What were the biggest challenges to accurately assessing First Defense’s net worth in 2018?
A: The lack of public financial disclosures, the company’s focus on niche markets (which made comparisons difficult), and the intangible nature of its intellectual property all contributed to the challenges. Valuation models had to rely heavily on industry benchmarks rather than hard data.
Q: Did First Defense Nasal Screens Corporation’s valuation change significantly after 2018?
A: While exact figures are not public, industry observers note that the company’s profile dramatically increased in 2020 due to the COVID-19 pandemic, which accelerated demand for respiratory protection technologies. This likely led to a revaluation, though the specifics remain undisclosed.
