
Where It All Began
The origins of top export countries trace back to the 15th century, when Portugal and Spain broke the Mediterranean monopoly on trade. Their caravels carried spices, silk, and gold from Asia and the Americas back to Europe, sparking the first global supply chains. But it was the Dutch who codified the modern export economy. By the 17th century, the Dutch East India Company (VOC) controlled half the world’s trade, using Amsterdam’s financial innovations to underwrite ventures from Java to the Cape of Good Hope. Their success hinged on three principles still vital today: specialization, infrastructure, and risk mitigation. The VOC’s shipyards turned out vessels that could cross oceans; its merchants standardized contracts to reduce fraud; and its bankers created the first futures markets to hedge against price swings. The Industrial Revolution then rewrote the rules. Britain’s coal-fired factories produced textiles and steel at scale, while its navy protected merchant routes. By 1850, Manchester’s mills supplied one-fifth of global cotton exports, and London’s financial district became the hub for trade financing. The top export countries of the 19th century weren’t just selling goods—they were selling systems. Germany’s Mittelstand firms proved that small, high-quality producers could outcompete mass manufacturers. Meanwhile, the U.S. leveraged its vast land and railroad networks to export agricultural surpluses, from wheat to pork bellies. The pattern was clear: export dominance required more than raw materials or labor—it demanded a feedback loop of innovation, logistics, and political stability.The Early Signs
The late 19th century saw the first glimpses of today’s leading export nations. Japan’s Meiji Restoration (1868) transformed the country from a feudal society into an industrial powerhouse, with silk and later steel becoming cornerstones of its trade. Meanwhile, Switzerland’s watchmakers perfected precision engineering, turning a niche craft into a global luxury staple. These weren’t accidents. Japan’s government actively recruited foreign experts to modernize its factories; Switzerland invested in vocational training to ensure quality control. The lesson was simple: export success wasn’t about natural resources alone—it was about cultivating a culture of excellence in production. The 20th century brought another shift. The Marshall Plan (1948) didn’t just rebuild Europe—it created export-oriented economies. West Germany’s Wirtschaftswunder (economic miracle) was built on exporting cars and machinery, while Italy’s Distretto Industriale model showed how clusters of small firms could dominate niches like leather goods and furniture. Even smaller players like Singapore and South Korea entered the game by focusing on what they did best: Singapore with shipping and refining, South Korea with electronics and shipbuilding. The blueprint was always the same: identify a gap, fill it with relentless efficiency, and then scale.The Turning Point
The 1970s marked the inflection point for top export countries. The oil crises revealed the vulnerabilities of over-reliance on single commodities, while Japan’s auto exports proved that manufacturing could be both high-volume and high-quality. The real turning point came in 1980, when China began its Reform and Opening-Up policy. Deng Xiaoping’s decision to establish Special Economic Zones in Shenzhen and other coastal cities didn’t just attract foreign investment—it created a new model for export-led growth. Factories sprang up overnight, assembling goods for brands like Nike and Dell, while China’s infrastructure—ports, highways, and railways—was built to move those goods to market. The shift wasn’t just about China. The same decade saw the rise of export powerhouses in unexpected places: Ireland’s tax incentives lured multinational corporations, turning it into Europe’s second-largest exporter per capita; the UAE’s Dubai transformed from a trading post into a global logistics hub. The common thread? These nations didn’t just sell products—they sold access. China offered cheap labor and manufacturing scale; Ireland offered a gateway to the EU; the UAE offered a neutral, efficient transit point. By the 1990s, the top export countries were no longer just suppliers—they were the architects of global supply chains."Trade is not about goods. It’s about the rules that govern how goods move—and who writes those rules." — Martin Wolf, Chief Economics Commentator, Financial Times

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1980–1990 |
|
| 1990–2000 |
|
| 2000–2010 |
|
| 2010–Present |
|
Lessons From the Journey
- Diversification is survival. Nations that bet too heavily on single commodities (e.g., Saudi Arabia’s oil reliance) face volatility, while top export countries like Germany and South Korea spread risk across sectors.
- Infrastructure is the silent enabler. The Panama Canal, China’s Belt and Road ports, and Germany’s Autobahn weren’t built for prestige—they were built to move goods faster and cheaper.
- Education and skills matter more than raw materials. Singapore’s export success hinges on its workforce’s proficiency in English and technical fields, not its natural resources.
- Geopolitics shapes supply chains. The U.S.-China trade war proved that even the most efficient export powerhouses can be disrupted by tariffs and sanctions.
- First-mover advantage fades. Japan dominated steel in the 1960s; China did in the 2000s. Today, Vietnam and India are poised to challenge in textiles and pharmaceuticals.
Where Things Stand Today
Today’s top export countries are a study in contrasts. China remains the undisputed leader, with exports reportedly valued at over $3 trillion annually—though growth has slowed as wages rise and geopolitical tensions mount. Germany’s Mittelstand firms still punch above their weight, exporting everything from luxury cars to precision tools, while the Netherlands’ Rotterdam port handles more containers than any other in Europe. Meanwhile, Vietnam has become the "next China," luring manufacturers with lower costs and free trade agreements. Even smaller players like Switzerland and Ireland thrive by specializing in high-margin niches: pharmaceuticals and financial services, respectively. Yet the landscape is shifting. Climate change is forcing export powerhouses to reconsider their strategies—droughts in Brazil threaten coffee and sugar exports, while melting Arctic ice opens new shipping routes that could disrupt traditional trade flows. Technology is another wildcard. The rise of 3D printing could decentralize manufacturing, reducing the need for leading export nations as intermediaries. And then there’s the labor factor: automation is eroding the cost advantage of low-wage producers like Bangladesh and Cambodia, pushing them to upskill or risk obsolescence. The question isn’t whether the current top export countries will remain dominant—it’s which ones will reinvent themselves before disruption forces their hand.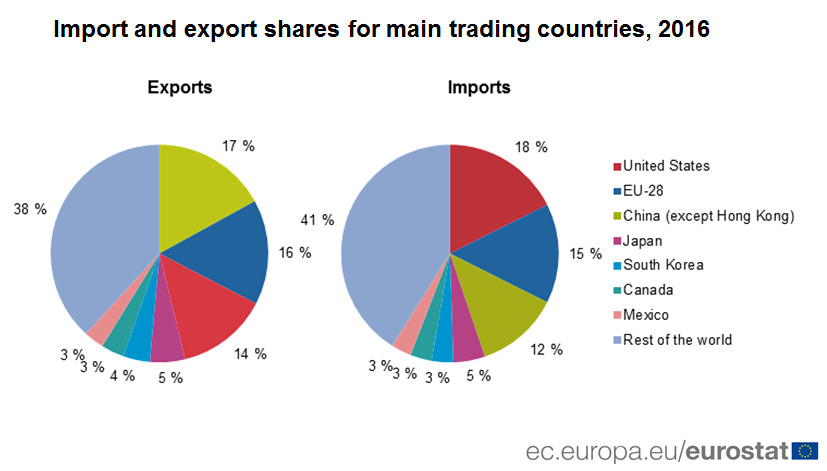
Conclusion
The story of top export countries is more than a ledger of numbers. It’s a testament to human ingenuity—the ability to turn sand into silicon, rubber into tires, and raw ambition into global influence. Yet history shows that no nation stays on top forever. The Dutch lost their dominance to Britain; Britain to Germany; Germany to Japan and later China. The cycle of rise and fall is inevitable, but the survivors are those who adapt. They’re the ones who see a shift in demand and pivot—like South Korea transitioning from shipbuilding to semiconductors, or Germany investing in green tech exports. The future belongs not to the complacent, but to those who treat export power as a verb, not a noun. One thing is certain: the leading export nations of 2050 won’t look like today’s. They’ll be shaped by climate resilience, digital infrastructure, and perhaps even off-world supply chains. For now, the titans of trade remain the same—China, Germany, the U.S., Japan—but the game has changed. The question is whether they’ll play to win, or get left behind.Comprehensive FAQs
Q: Which country is currently the world’s largest exporter?
A: As of recent data, China holds the top spot, with exports reportedly exceeding $3 trillion annually. Its dominance stems from a mix of manufacturing scale, infrastructure, and strategic trade policies. However, growth has slowed due to geopolitical tensions and rising domestic wages.
Q: How do small countries like Singapore or Switzerland become major exporters?
A: These nations leverage specialization and strategic positioning. Singapore’s success hinges on its port infrastructure, tax policies, and multilingual workforce, making it a hub for global trade. Switzerland excels in high-value niches like pharmaceuticals and luxury goods, where precision and branding matter more than scale.
Q: What role does infrastructure play in export success?
A: Infrastructure is the backbone of top export countries. Efficient ports (like Rotterdam or Shanghai), railways, and digital networks reduce costs and delays. For example, China’s high-speed rail system connects factories to coastal ports, enabling just-in-time manufacturing—a critical advantage in global supply chains.
Q: Are there risks to relying on a single export product?
A: Absolutely. Nations like Nigeria (oil) or Chile (copper) face volatility when commodity prices fluctuate. Export powerhouses like Germany and South Korea mitigate risk by diversifying across sectors—from cars to semiconductors—ensuring resilience against market shocks.
Q: How has the U.S.-China trade war affected global export patterns?
A: The trade war accelerated nearshoring and friend-shoring, with companies relocating supply chains closer to home or to politically aligned nations. Mexico, Vietnam, and India have gained as manufacturers seek alternatives to China. The war also highlighted vulnerabilities in over-reliance on single-source suppliers.
Q: Can a country become a top exporter without natural resources?
A: Yes. Top export countries like Japan, South Korea, and Switzerland prove it. They succeed by investing in education, innovation, and high-value industries. Japan’s robotics exports and Switzerland’s pharmaceuticals show that intangible assets—like R&D and brand reputation—can outweigh physical resources.
Q: What’s the biggest challenge facing today’s export leaders?
A: Climate change and automation pose existential threats. Rising temperatures disrupt agricultural exports (e.g., coffee, cocoa), while AI and robotics reduce the labor-cost advantage of low-wage producers. Export powerhouses must invest in green tech and reskilling to stay competitive.
Q: Will Africa ever produce a top 10 exporter?
A: Potential exists, but structural barriers remain. Countries like Ethiopia (textiles) and Côte d’Ivoire (cocoa) are rising, but challenges include infrastructure gaps, political instability, and reliance on raw materials. Success will require long-term investments in education, logistics, and diversification—lessons leading export nations have mastered over centuries.
