
6 Things Worth Knowing About the Lowest Forbes 400 Net Worth
The lowest Forbes 400 net worth entries are a study in contrasts: between inherited privilege and earned grit, between old-economy stability and new-economy precarity. These six insights cut to the heart of what defines this group—and why their fortunes matter beyond the raw numbers.1. The $2 Billion Threshold Is a Fragile Perch
The Forbes 400’s cutoff isn’t arbitrary. It’s the point where wealth becomes visible in ways that sub-$2 billion fortunes aren’t—through tax filings, political donations, or media scrutiny. But for those at the bottom of the Forbes 400, the difference between inclusion and exclusion is often a matter of timing. A single year of poor performance can demote a family from the list, while a lucky IPO or asset sale can propel a newcomer in. The volatility is acute in sectors like retail, where traditional department stores (think Macy’s heirs) see their valuations erode faster than tech or energy fortunes. The psychological toll of hovering at this threshold is underdiscussed. A $2 billion net worth might sound like a safety net, but in the context of Forbes 400 peers, it’s a constant reminder of vulnerability. The list isn’t just about wealth; it’s about permanence. For families like the Waltons (whose fortunes have dipped below $2 billion in recent years), the stakes are existential. The lowest Forbes 400 net worth members live with the knowledge that one misstep could erase decades of accumulation.2. Many Are Heirs, Not Self-Made Entrepreneurs
Contrary to the narrative of the rugged billionaire, roughly 40% of the lowest Forbes 400 net worth individuals are heirs to fortunes built by earlier generations. The Pritzker family, for instance, has seen its fortune dip below $3 billion in recent years, relying on real estate and private equity to stay afloat. Similarly, the Mars family—heirs to the candy empire—have diversified into pharmaceuticals and tech, but their core assets remain tied to legacy businesses facing disruption. These families aren’t just preserving wealth; they’re engaged in a high-stakes game of asset rotation to avoid falling off the list entirely. The dynamic shifts when comparing heirs to self-made founders. While heirs like the Koch brothers (now below $40 billion but historically in the lowest Forbes 400 net worth range) have leveraged family capital to dominate industries, self-made figures at the bottom—such as the founders of niche manufacturing or regional media companies—often lack the liquidity to weather downturns. The lowest Forbes 400 net worth segment is where dynastic wealth and entrepreneurial risk collide, often with uneven results.3. Real Estate and Family Offices Are Their Lifelines
When public markets turn hostile, private assets become the last bastion of stability. For those at the lowest Forbes 400 net worth, real estate and family offices are the default strategies to preserve capital. The Pritzker family, for example, has long relied on commercial real estate and private equity to offset declines in their Hyatt hotel empire. Similarly, the Walton family’s Arvest Bank holdings and retail properties act as ballasts when Walmart’s stock underperforms. These assets aren’t just investments; they’re insurance policies against demotion. The rise of family offices—private wealth management arms—has become a defining feature of this group. Unlike the ultra-wealthy who can deploy capital in public markets, those at the bottom of the Forbes 400 often lack the scale to go public. Their family offices become the hub for deploying capital across illiquid assets: timberland, vineyards, or even art collections. The result? A quiet arms race to diversify before the next market correction pushes them out of the top 400.4. Philanthropy as a Status Symbol
For the lowest Forbes 400 net worth members, philanthropy isn’t just charity—it’s a way to signal permanence. The MacKenzie Scott, whose fortune dipped below $20 billion in 2023 but remains in the lowest Forbes 400 net worth range, has become synonymous with massive, public donations. But even smaller-scale philanthropists—like the heirs to the Campbell Soup fortune—use giving to reinforce their place on the list. A $100 million donation to a university or museum isn’t just altruism; it’s a statement: We’re still relevant. The irony? Philanthropy can accelerate wealth erosion. Large donations reduce taxable assets, and in some cases, trigger capital gains taxes that further shrink net worth. Yet the pressure to give persists, especially for families who’ve built their identities around legacy. For those at the lowest Forbes 400 net worth, every check written is both a risk and a reassurance—a gamble that their name will remain on the list next year.5. Political Influence Is a Double-Edged Sword
"The moment you’re no longer on the Forbes 400, your access changes. Lobbyists take your calls less often. Your name gets dropped from high-stakes policy discussions." — Former aide to a Fortune 500 executivePolitical power correlates closely with net worth, and the lowest Forbes 400 net worth members wield influence disproportionate to their fortunes. The Koch network, for instance, has spent decades shaping conservative policy while its net worth fluctuated near the bottom of the list. But when fortunes dip, so does leverage. The Waltons, once among the most politically active heirs, have seen their influence wane as their wealth has contracted. For these families, staying on the Forbes 400 isn’t just about money—it’s about maintaining a seat at the table where laws are made. The flip side? Political engagement can be a wealth-preservation tool. Tax policy, regulatory rollbacks, and infrastructure spending directly impact the assets these families control. A single legislative victory—like a tax break on carried interest—can mean the difference between staying in the lowest Forbes 400 net worth tier and falling out entirely. The line between philanthropy and political spending blurs here, as donations to think tanks or super PACs serve dual purposes: social good and self-preservation.
6. The List Is a Moving Target
Forbes’ methodology changes yearly, and so does the composition of the lowest Forbes 400 net worth ranks. In 2023, the 400th spot was occupied by a figure whose fortune was estimated at just over $2 billion—down from $2.5 billion the prior year. The reason? A combination of market downturns, divestitures, and currency fluctuations. What’s striking is how quickly fortunes can shift: a single bad quarter for a family’s core business (like a decline in luxury goods sales for the Wertheimer heirs) can reorder the list. The lowest Forbes 400 net worth segment is also where new industries make their debut. Cryptocurrency fortunes, for example, have yet to crack the top 400, but as blockchain ventures mature, we may see founders like Sam Bankman-Fried’s successors (if any) vying for these spots. Meanwhile, old-economy families are being replaced by tech inheritors—like the children of early internet moguls—who’ve yet to build their own empires but ride the coattails of their parents’ success.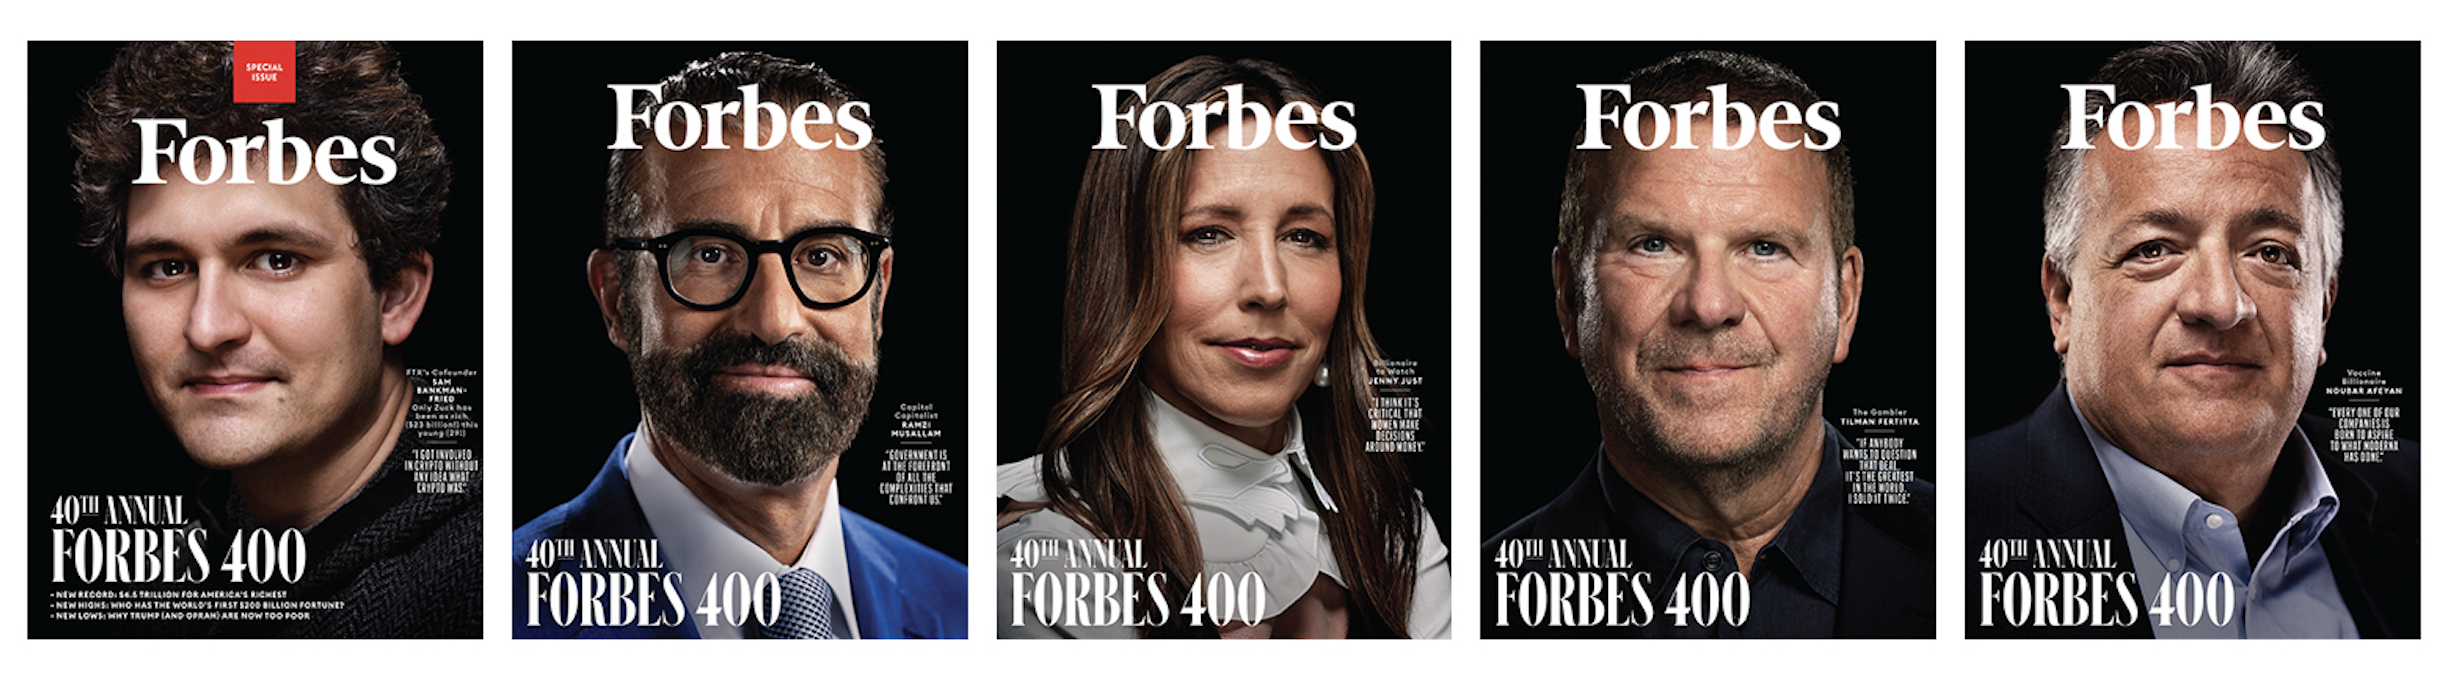
How These Facts Connect
The lowest Forbes 400 net worth isn’t just a footnote in the story of American wealth—it’s a pressure cooker where legacy, risk, and resilience intersect. These individuals are caught between two worlds: the old guard of industrial dynasties and the new guard of tech-driven fortunes. Their strategies—diversification, philanthropy, political engagement—aren’t just tactics; they’re survival mechanisms in an era where the rules of wealth accumulation are shifting faster than ever. What’s clear is that the bottom of the Forbes 400 is no longer a safe harbor. The days when a family could rest on the laurels of a single business (like the Rockefellers with Standard Oil) are over. Today’s lowest Forbes 400 net worth members must constantly innovate, whether by spinning off new ventures, lobbying for favorable policies, or making high-profile donations to stay in the public eye. Their stories reveal a harsh truth: wealth, even at this scale, is never guaranteed.| Key Insight | Implication | Example |
|---|---|---|
| Fragile $2B Threshold | One bad year can demote a family | Pritzker family’s Hyatt-related declines |
| Heirs vs. Self-Made | Legacy wealth requires active management | Mars family’s shift to pharmaceuticals |
| Real Estate as Ballast | Illiquid assets become critical | Walton family’s Arvest Bank holdings |
| Philanthropy as Signal | Giving reinforces status but erodes capital | MacKenzie Scott’s high-profile donations |

Conclusion
The lowest Forbes 400 net worth entries are often dismissed as the "also-rans" of the ultra-wealthy, but they’re far more interesting than that. They represent the tension between preservation and innovation, between old-money inertia and the need to adapt. For these families and founders, the list isn’t just a ranking—it’s a battleground. The question isn’t just how they got there, but how long they can stay. As markets evolve and new industries emerge, the bottom of the Forbes 400 will continue to shift. Some will fall out entirely, replaced by the next generation of self-made billionaires or tech heirs. Others will cling to the list through sheer force of diversification and political savvy. What remains constant is the pressure—financial, social, and psychological—to remain relevant. In an era where wealth is increasingly concentrated at the top, the lowest Forbes 400 net worth members are the ones who remind us that even at $2 billion, the stakes are everything.Comprehensive FAQs
Q: How often does the Forbes 400 list change?
The Forbes 400 is published annually, and the composition shifts every year due to market fluctuations, divestitures, and new entrants. The lowest Forbes 400 net worth spots are particularly volatile, with families moving in and out based on performance. For example, the Pritzker family’s position has fluctuated in recent years as their Hyatt-related assets underperformed.
Q: Can someone be on the Forbes 400 without a public company?
Yes. Many at the lowest Forbes 400 net worth levels rely on private assets—real estate, family offices, or illiquid investments—to meet the $2 billion threshold. Heirs like the Mars family or the Walton siblings often maintain their status through private equity and real estate holdings rather than public stock.
Q: What’s the biggest risk for someone at the bottom of the Forbes 400?
The biggest risk is market or industry decline. A single bad quarter for a core business (like a retail downturn for a department store heir) can push a family below the $2 billion mark. Additionally, tax policies, regulatory changes, or shifts in consumer behavior can erode fortunes faster than expected.
Q: Do all Forbes 400 members have to be U.S. citizens?
No. While the majority are U.S.-based, the Forbes 400 includes global figures whose wealth is tied to American assets or businesses. For example, some Canadian or European heirs may appear on the list if their fortunes are denominated in U.S. dollars or managed through American entities.
Q: How do family offices help preserve wealth at the lowest Forbes 400 levels?
Family offices provide diversification and control. They allow heirs to deploy capital across private assets—real estate, venture capital, or alternative investments—without the volatility of public markets. For those at the lowest Forbes 400 net worth, a well-managed family office can mean the difference between staying on the list and falling out.
Q: Are there any industries where the lowest Forbes 400 members are concentrated?
Yes. Retail, real estate, and legacy manufacturing are common among the lowest Forbes 400 net worth entries. Families tied to department stores (like Macy’s heirs) or regional manufacturing dynasties often find their fortunes under pressure from e-commerce and automation.
Q: Can a self-made billionaire stay on the Forbes 400 without growing their wealth?
It’s extremely difficult. The lowest Forbes 400 net worth threshold requires not just initial accumulation but ongoing asset appreciation. Even if a founder’s business plateaus, inflation, taxes, and market conditions can erode net worth over time. Most self-made figures at this level must either reinvest aggressively or diversify to maintain their spot.
