Common Myths About Countries with the Least Debt
The narrative around countries with the least debt is often oversimplified. One persistent myth is that these nations achieve their balance sheets through austerity alone—cutting public spending to the bone while citizens endure hardship. The reality is far more nuanced. Some of these economies thrive on revenue diversification, where multiple income streams—tourism, remittances, or digital services—offset the need for borrowing. Others leverage structural surpluses, where tax systems and expenditure controls create natural buffers against deficits. The assumption that low debt equals economic stagnation ignores how these countries reinvest surpluses into infrastructure, education, or reserves, ensuring long-term growth without debt servitude. Another misconception is that countries with minimal debt are immune to economic volatility. While their debt-to-GDP ratios may be enviable, their exposure to global commodity prices, climate risks, or geopolitical instability can still destabilize budgets. For instance, a nation with negligible debt might face a crisis if its primary export—say, bananas or fish—collapses due to disease or overfishing. The resilience of these economies lies not in debt avoidance alone but in their ability to adapt without relying on loans to weather storms. Their financial health is a function of structural flexibility, not just arithmetic balance sheets.Myth 1: Low Debt Means Low Government Spending
The idea that countries with the least debt must have underfunded public services is a common oversimplification. In truth, many of these nations spend efficiently, not necessarily frugally. Take Brunei, where oil revenues fund universal healthcare and education without resorting to borrowing. The government’s ability to tax windfall profits—rather than relying on debt—allows for high spending levels without accumulating liabilities. Similarly, Singapore’s sovereign wealth fund (temporarily suspended due to COVID-19) acts as a fiscal stabilizer, enabling generous social programs without debt. The confusion arises from conflating debt levels with spending priorities. A country might invest heavily in infrastructure or social welfare while maintaining low debt through savings-driven models. For example, Norway’s oil wealth is saved in a sovereign fund, allowing the government to spend on public goods without increasing debt. The key distinction is between consumption-driven debt (borrowing to fund current expenses) and investment-driven debt (borrowing for long-term growth). The former is risky; the latter can be sustainable if managed well. Even among countries with the least debt, some prioritize debt-free growth over short-term stimulus—a trade-off that limits immediate spending but secures future stability.Myth 2: Small Populations Automatically Mean Low Debt
It’s tempting to assume that countries with the least debt are simply too small to accumulate significant liabilities. While population size does play a role, the relationship between debt and national size is more complex. Consider Bhutan, with a population of around 780,000 and a debt-to-GDP ratio below 50%. Its low debt isn’t just a function of scale but of deliberate fiscal policies, including a gross national happiness framework that prioritizes sustainable development over rapid economic expansion. Meanwhile, larger nations like Japan or Switzerland—both with low debt relative to GDP—demonstrate that size alone doesn’t determine fiscal health. The real driver is institutional capacity. Smaller nations may have fewer borrowing opportunities, but they also face fewer demands on public funds. However, some microstates—like Monaco or Liechtenstein—maintain low debt through high-income taxation and strategic borrowing (e.g., issuing bonds to finance infrastructure). The myth ignores that countries with the least debt often combine small size with high revenue efficiency, whether through tourism, financial services, or natural resource management. Population alone is a red herring; governance and economic structure matter far more.Myth 3: Debt-Free Equals Crisis-Proof
The belief that countries with the least debt are inherently safe from economic shocks is dangerous. Even the most disciplined fiscal policies can unravel when external factors intervene. The 2008 financial crisis exposed vulnerabilities in Iceland, which had maintained low debt but saw its banking sector collapse due to speculative lending. Similarly, Kuwait’s oil-dependent economy faced budget deficits when oil prices plummeted in the 1980s, forcing it to dip into reserves rather than borrow. These examples show that low debt does not equal immunity—it merely reduces one type of risk. The resilience of countries with minimal debt depends on diversification. Nations that rely on a single revenue source—whether oil, tourism, or remittances—remain vulnerable despite low debt levels. For instance, Timor-Leste’s debt-to-GDP ratio is negligible, but its economy is highly dependent on oil revenues, making it susceptible to price fluctuations. The lesson is that fiscal prudence must coexist with economic diversification to truly insulate a country from crises. Debt-free status is a tool, not a guarantee.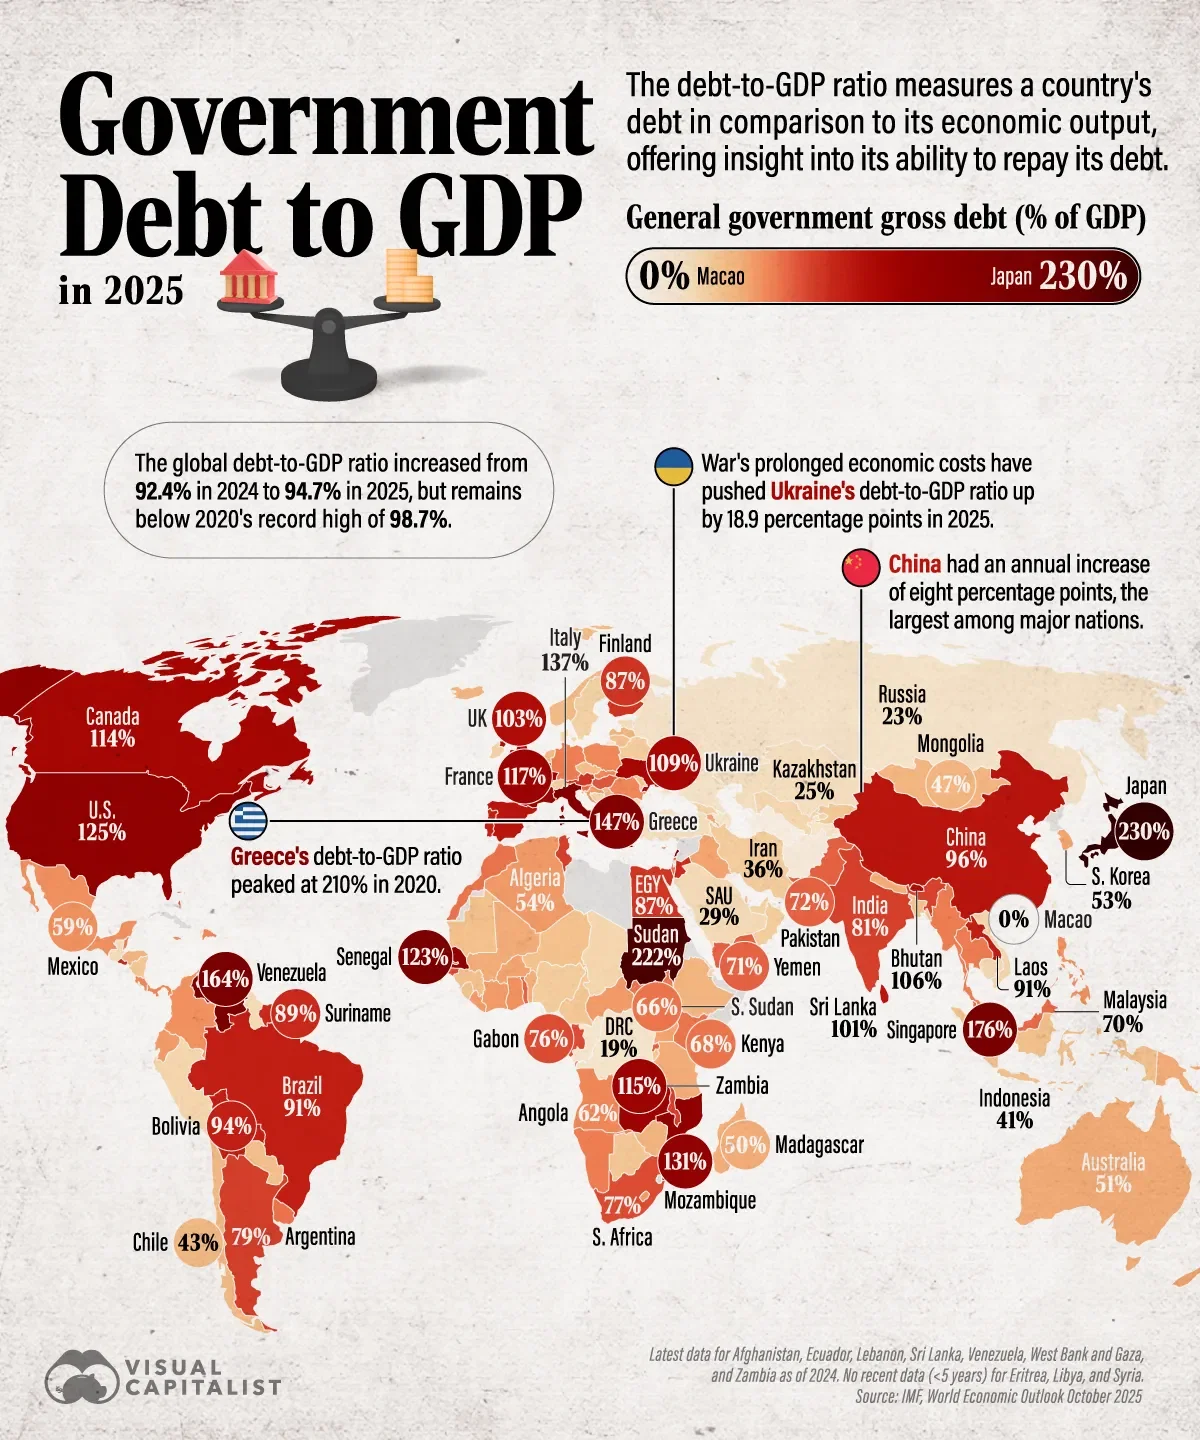
What Holds Up to Scrutiny
At the core, countries with the least debt share three verifiable traits: revenue discipline, long-term planning, and transparency. Revenue discipline isn’t about cutting spending arbitrarily but about aligning expenditures with sustainable income streams. For example, Qatar’s low debt stems from oil revenue management, where surplus funds are saved rather than spent. Long-term planning involves multi-generational budgeting, as seen in Norway’s sovereign wealth fund, which invests oil revenues globally to ensure returns outlast the resource itself. Transparency—audited budgets, independent fiscal agencies—reduces corruption and ensures debt (when it exists) is deployed efficiently. These traits aren’t unique to small or wealthy nations. Countries with minimal debt often emerge from post-conflict reconstruction, where debt is avoided to prevent future instability. Rwanda, for instance, rebuilt after the 1994 genocide with minimal borrowing, focusing instead on aid and domestic revenue. The evidence suggests that fiscal responsibility is a choice, not a geographic or economic inevitability. Even among countries with the least debt, however, outliers exist—nations that appear debt-free but mask hidden liabilities, such as off-balance-sheet obligations or pension fund deficits."Debt is not the enemy; mismanagement is. The goal isn’t to eliminate debt entirely but to ensure it serves productivity, not consumption." — IMF Fiscal Affairs Department, 2022
| Common Belief | What the Evidence Says |
|---|---|
| Countries with the least debt are always wealthy. | Some are resource-rich (e.g., Brunei), but others rely on agriculture (e.g., Bhutan) or services (e.g., Singapore). Wealth isn’t a prerequisite. |
| Low debt means no public investment. | Many reinvest surpluses (e.g., Norway’s sovereign fund) or use debt strategically for infrastructure (e.g., Switzerland’s rail network). |
| Small populations guarantee low debt. | Size matters less than governance. Microstates like Monaco borrow selectively, while larger nations like Japan prioritize debt sustainability. |
| Debt-free countries are recession-proof. | External shocks (e.g., Iceland’s 2008 banking crisis) show even low-debt economies can face crises if unprotected. |
| Transparency isn’t necessary for low debt. | Nations with hidden liabilities (e.g., pension debts) often appear debt-free but face future risks. Transparency is critical. |
Why the Confusion Persists
The gap between perception and reality stems from media bias and data limitations. Headlines focus on debt crises—Greece, Argentina, Lebanon—while countries with the least debt receive scant attention unless they’re outliers (e.g., North Korea’s opaque finances). The IMF and World Bank publish debt statistics, but their reports often prioritize high-debt nations, assuming low-debt cases are uninteresting. Additionally, debt definitions vary: some nations exclude certain liabilities (e.g., military spending), while others inflate figures to secure aid. This inconsistency obscures comparisons. Another factor is political narrative. Governments with low debt may downplay their achievements to avoid scrutiny, while those with high debt use it to justify austerity. The result is a selective spotlight that reinforces stereotypes: debt is a problem for the "irresponsible," while countries with minimal debt are either ignored or romanticized as "too good to be true." The truth lies in the middle—these economies succeed through deliberate policies, not luck. Without acknowledging their strategies, the global conversation on fiscal health remains incomplete.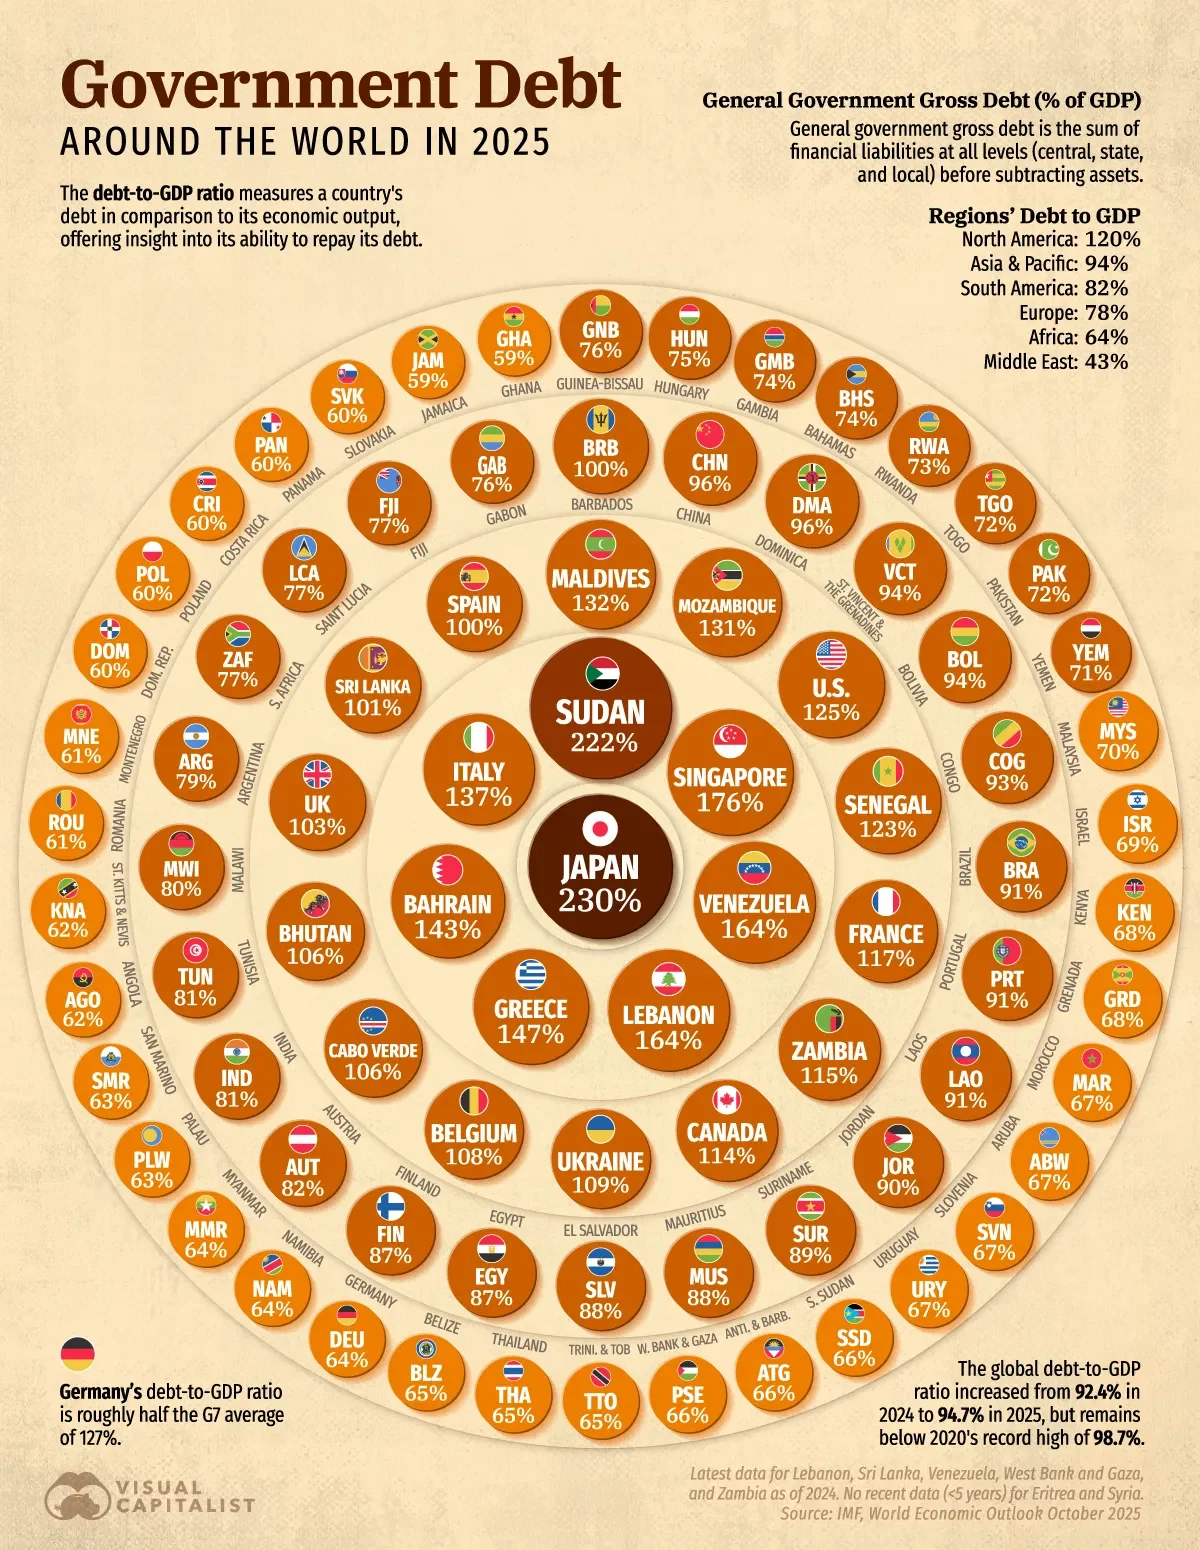
Conclusion
The study of countries with the least debt reveals that financial prudence is less about arithmetic and more about systems. Whether through resource management, institutional design, or revenue diversification, these nations demonstrate that debt isn’t an inevitable consequence of governance. Their models offer blueprints for others—though not without trade-offs. For instance, countries with minimal debt often sacrifice short-term stimulus for long-term stability, a choice that may limit immediate growth but secures future resilience. The takeaway isn’t to emulate their debt levels but to adapt their principles. Transparency, diversification, and long-term planning are tools applicable to any economy, regardless of size or wealth. The confusion around countries with the least debt persists because their success challenges simplistic narratives about fiscal policy. By examining their strategies—rather than just their balance sheets—we uncover lessons that extend far beyond the numbers.Comprehensive FAQs
Q: Are there any countries with zero debt?
A: No country has truly zero debt, though some—like Estonia or Hong Kong—have debt-to-GDP ratios below 20%. Even these nations hold reserves or have off-balance-sheet liabilities (e.g., pension funds). The closest examples are microstates like Liechtenstein or Monaco, but their debt is often held by sovereign wealth funds rather than public accounts.
Q: Can a country with low debt still face economic trouble?
A: Absolutely. Countries with the least debt can collapse due to external shocks (e.g., Iceland’s 2008 banking crisis) or structural weaknesses (e.g., Timor-Leste’s oil dependency). Debt is one risk among many—diversification, governance, and adaptability matter more. For example, Kuwait’s debt was negligible in the 1980s, but oil price drops forced it to rely on reserves.
Q: How do small nations like Bhutan maintain low debt?
A: Bhutan combines revenue controls (e.g., tariffs on imports) with aid dependency (e.g., grants from India) and gross national happiness policies that prioritize sustainable growth over rapid expansion. Its debt is kept low by limiting public sector wages and borrowing only for essential infrastructure, such as hydropower projects.
Q: Is Singapore’s debt-free status realistic?
A: Singapore’s debt-to-GDP ratio is among the world’s lowest, but its sovereign wealth fund (GIC, Temasek) holds trillions in assets—some of which could be deployed as needed. The government technically borrows but uses proceeds to invest in assets (e.g., infrastructure, sovereign bonds) rather than fund current spending. This asset-backed approach blurs the line between debt and investment.
Q: Do oil-rich countries like Norway avoid debt by default?
A: No. Norway’s low debt stems from disciplined fiscal rules, including the Government Pension Fund Global, which saves oil revenues for future generations. The country borrows selectively (e.g., for infrastructure) but repays quickly using oil windfalls. Its model proves that resource wealth alone doesn’t guarantee low debt—institutional design does.
Q: Are there African countries with low debt?
A: Yes, but they’re exceptions. Botswana (debt-to-GDP ~20%) and Rwanda (post-genocide reconstruction with minimal borrowing) are notable. Most African nations face high debt due to aid dependency or commodity price volatility. The continent’s low-debt outliers often rely on strong governance, foreign investment, or natural resources (e.g., Mauritius’ tourism revenue).
Q: Can a country with low debt still have high inflation?
A: Yes, but it’s rare. Countries with the least debt typically avoid monetary financing (printing money to cover deficits), which causes inflation. However, supply shocks (e.g., food shortages) or currency devaluations can still drive inflation even with low debt. For example, Zimbabwe’s hyperinflation wasn’t debt-driven but stemmed from monetary mismanagement—a risk even for low-debt economies if fiscal discipline wavers.
Q: What’s the biggest misconception about low-debt economies?
A: The biggest myth is that countries with the least debt are naturally immune to crises. In reality, their vulnerabilities lie elsewhere—commodity dependence, governance risks, or external shocks. Debt is just one metric; structural resilience is what truly matters. For instance, Brunei’s low debt doesn’t protect it from oil price swings, while Singapore’s debt-free status is underpinned by global financial integration—a double-edged sword in crises.
