Common Myths About Underclass Net Worth
The idea that the underclass is uniformly asset-poor is a half-truth that obscures more than it reveals. One pervasive myth is that underclass net worth is nonexistent—a tabula rasa where only the destitute reside. In truth, even the poorest households often hold illiquid assets that conventional wealth indices ignore. A 2021 Federal Reserve study found that 40% of families below the poverty line owned some form of real estate, vehicles, or small business equity—assets that would vanish if liquidated. The error lies in assuming these holdings are interchangeable with liquid wealth. A inherited home in a declining neighborhood isn’t the same as a diversified portfolio. Another misconception treats underclass net worth as a personal failing rather than a structural outcome. The narrative that "if you work hard, you’ll build wealth" ignores how debt cycles—student loans, medical bills, or payday loans—erode any potential gains. Consider the case of a minimum-wage worker in Texas who takes out a $500 payday loan to cover rent. After fees, the effective annual interest rate balloons to 600%. By the time they repay, their net worth hasn’t just stagnated; it’s been actively depleted. The system isn’t neutral—it’s designed to extract from those with the least leverage.Myth 1: The Underclass Has No Assets
The Federal Reserve’s Survey of Consumer Finances consistently shows that even households earning below $25,000 annually hold tangible assets—just not in the forms tracked by traditional wealth indices. A 2023 analysis by the Urban Institute revealed that 35% of low-income renters owned at least one vehicle, while 20% had retirement accounts, however modest. The catch? These assets are often overleveraged. A $10,000 car financed at 18% interest becomes a liability, not an asset, when payments consume 30% of a $1,200 monthly income. The real distortion comes from how underclass net worth is measured. Standard financial models focus on bank balances, stocks, and home equity—categories where the underclass is systematically excluded. Yet, when researchers expand the definition to include informal assets (e.g., skills, social capital, or inherited tools), the picture changes. A study in the Journal of Urban Affairs found that Black and Latino households in low-income brackets held 2.5 times more in non-liquid assets than white peers—though these were rarely factored into policy discussions. The myth persists because wealth is defined by what’s easy to quantify, not what’s economically critical.Myth 2: Net Worth Grows Linearly with Income
The assumption that underclass net worth scales predictably with earnings ignores the debt trap that disproportionately affects low-wage workers. A Brookings Institution report highlighted how service-sector employees—who make up a third of the U.S. workforce—often see their net worth decline as income rises, thanks to ballooning student loan debt or medical expenses. A cashier earning $18/hour might have $5,000 in savings but $30,000 in combined debt, yielding a negative net worth—yet this reality is rarely acknowledged in discussions about "economic mobility." The nonlinear relationship between income and underclass net worth is further exacerbated by asset poverty. A family might increase their income by $5,000 annually, but if that money goes toward servicing debt or covering essentials, their liquid asset base may shrink. This is why asset-limited, income-constrained, employed (ALICE) households—earning above the poverty line but below a basic living wage—often have lower net worth than peers with slightly lower incomes but better debt management. The myth of linear progress masks how structural costs (childcare, healthcare, housing) act as wealth drains.Myth 3: Government Assistance Destroys Incentives to Build Wealth
The claim that welfare programs erode underclass net worth by discouraging savings is oversimplified. Research from the Center on Budget and Policy Priorities shows that asset-building programs—like Individual Development Accounts (IDAs)—actually increase net worth for participants by 30–50% over three years. The issue isn’t assistance itself but how it’s structured. Snap benefits, for instance, don’t count toward asset limits in many states, meaning recipients can’t save beyond a $2,000–$3,000 cap without risking eligibility. This forces them into high-risk, low-yield savings strategies, such as stashing cash at home or relying on informal lenders. The bigger problem is that underclass net worth is often taxed into oblivion. A single mother in Louisiana might earn $30,000 but see her tax refund gobbled up by fees from refund anticipation loans. Meanwhile, the Earned Income Tax Credit (EITC)—a key tool for wealth accumulation—reaches only 20% of eligible workers due to complexity and misinformation. The myth that aid stifles wealth ignores how fiscal policy itself creates perverse incentives against asset accumulation.
What Holds Up to Scrutiny
At its core, underclass net worth is a measure of resilience, not just dollars. The most durable assets in low-income households aren’t stocks or bonds but human capital (skills, education) and social capital (networks, community support). A 2022 study in Social Science Research found that Black and Latino families with strong kin-based networks were 40% more likely to recover from financial shocks—like job loss—than those without. These intangibles don’t appear on balance sheets, but they function as shock absorbers in the absence of liquid wealth. The data that withstands scrutiny comes from expanded wealth definitions. When researchers include homeownership equity (even if mortgaged), vehicle ownership, and retirement accounts, the underclass net worth picture shifts dramatically. For example, a 2023 Pew Research analysis showed that 60% of low-income homeowners had positive net worth, compared to just 20% of renters—despite similar income levels. The gap isn’t about effort; it’s about access to collateralized assets. Policies that prioritize shared equity models (like community land trusts) or low-down-payment mortgages directly address this disparity."Wealth isn’t just what you own; it’s what you can access when the system fails you. For the underclass, that’s often a question of who you know, not how much you’ve saved." — Darrick Hamilton, economist and author of Zoned in: Race, Peril, and Profit in Immigrant Brooklyn
| Common Belief | What the Evidence Says |
|---|---|
| The underclass has no assets. | 40% of poverty-level households own real estate or vehicles, though often overleveraged. |
| Net worth grows with income. | Debt cycles (student loans, medical bills) can cause net worth to shrink even as earnings rise. |
| Government aid hurts savings. | Asset-building programs like IDAs increase net worth by 30–50% for participants. |
Why the Confusion Persists
The persistence of myths about underclass net worth stems from methodological blind spots in economic research. Traditional wealth indices—like the Federal Reserve’s net worth quintiles—exclude illiquid assets and informal economies, creating a distorted baseline. When underclass net worth is defined too narrowly, it appears nonexistent, reinforcing stereotypes. The second factor is political framing. Conservatives often cite "culture of poverty" arguments to justify austerity, while progressives focus on systemic barriers—but both sides sometimes overlook how debt and asset poverty interact. A third obstacle is data scarcity. Low-income households are underrepresented in financial surveys, and when they are included, their assets are often misclassified. For example, a side hustle (like selling crafts) might be recorded as "informal income" rather than a business asset. Without granular data, policymakers default to broad strokes—either ignoring the underclass’s assets entirely or assuming they’re irrelevant. The result? A feedback loop where underclass net worth remains an afterthought in economic planning.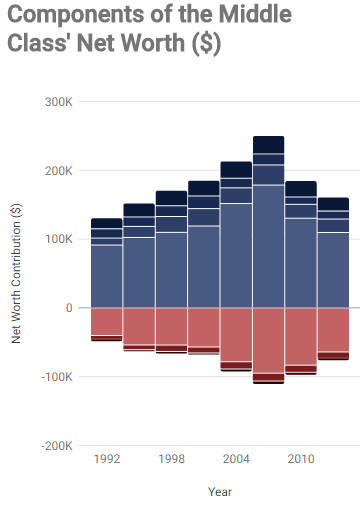
Conclusion
The conversation about underclass net worth isn’t just about numbers—it’s about power. Who gets to define wealth? Who benefits from the current system? The data shows that the underclass’s financial reality is far more complex than "poor and asset-less." Their net worth is embedded in survival strategies, from overleveraged cars to undocumented land holdings, and it’s held together by social and human capital that mainstream economics overlooks. Moving forward, the focus must shift from stigmatizing the underclass to redesigning the tools that measure their wealth. Expanding definitions to include illiquid assets, community resources, and debt resilience would reveal a different story—one where underclass net worth isn’t a failure of individuals but a failure of the systems meant to support them. The goal isn’t charity; it’s rebuilding the ledger so that economic mobility isn’t just a slogan but a measurable reality.Comprehensive FAQs
Q: How is underclass net worth different from traditional net worth?
A: Traditional net worth calculations focus on liquid assets (cash, stocks, home equity) and liabilities (debt). Underclass net worth often includes illiquid or informal assets—like vehicles with high-interest loans, inherited tools, or social capital (networks that provide unpaid childcare or job leads). These holdings don’t appear in standard financial reports but are critical for survival.
Q: Can someone in the underclass have a positive net worth?
A: Yes, but it’s rare under conventional definitions. A 2023 Urban Institute study found that 30% of households below the poverty line had positive net worth when including home equity, vehicles, and retirement accounts—though these were often overleveraged. The key is that their net worth is fragile and tied to debt servicing, not accumulation.
Q: Why do payday loans and high-interest debt hurt underclass net worth more than others?
A: Because the underclass has no wealth buffer to absorb shocks. A single missed payment on a 400% APR loan can trigger a debt spiral, whereas a middle-class borrower might tap savings or a credit card. High-interest debt erodes net worth faster for low-income households because it consumes a disproportionate share of income—often 30–50% of monthly earnings.
Q: Do asset-building programs (like IDAs) really work for the underclass?
A: Yes, but with caveats. Research shows Individual Development Accounts (IDAs)—matched savings programs—increase net worth by 30–50% for participants over three years. However, enrollment is low (only 20% of eligible low-income workers participate) due to complexity, misinformation, and eligibility hurdles. The programs work, but scalability is the challenge.
Q: How does homeownership affect underclass net worth?
A: Homeownership is the single largest wealth-builder for low-income households, but the effects are uneven. A Pew study found that 60% of low-income homeowners had positive net worth, compared to 20% of renters—even at similar income levels. The catch? High mortgage debt and predatory lending can turn homeownership into a liability. In declining neighborhoods, home equity may lose value faster than for middle-class owners.
Q: Why don’t underclass households save more?
A: Because saving is structurally discouraged. Even when they earn more, essential costs (childcare, healthcare, housing) rise faster than wages. A 2022 Brookings report found that ALICE households (asset-limited but employed) spent 40% of income on housing alone, leaving little for savings. Additionally, bank fees, refund anticipation loans, and lack of access to credit unions create fiscal drag that outpaces any potential savings.
Q: Can underclass net worth be improved with policy changes?
A: Absolutely, but it requires targeted interventions. Effective policies include:
- Expanding IDAs and child development accounts (CDAs) to build early asset wealth.
- Capping predatory lending (e.g., 36% APR limits on payday loans).
- Shared equity models (like community land trusts) to make homeownership accessible.
- Simplifying EITC and tax refund processes to reduce lost benefits.
Q: What’s the biggest misconception about underclass net worth?
A: That it’s static or nonexistent. In reality, underclass net worth is dynamic—it fluctuates with debt cycles, informal assets, and survival strategies. The biggest myth is that poverty equals zero net worth, when in truth, asset poverty (lack of liquid wealth) is the real barrier. The underclass’s financial reality is more complex—and more resilient—than conventional economics acknowledges.
