
The Short Answers
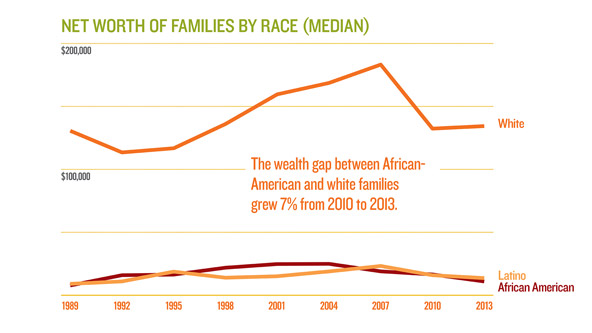
- The racial wealth gap in the U.S. means white households hold 10 times more wealth on average than Black households, with Hispanic families falling in between.
- Historical policies like redlining, predatory lending, and exclusion from New Deal programs directly shaped today’s net worth disparities.
- Homeownership is the single largest driver of racial wealth gaps, with white families owning homes at nearly 30 percentage points higher rates than Black families.
- Student loan debt disproportionately burdens Black and Hispanic borrowers, widening the wealth gap even as education levels rise.
- Policy solutions—like baby bonds, wealth-building programs, and closing the racial homeownership gap—could shrink disparities but face political resistance.
- The net worth of races isn’t just about income; it’s about inherited wealth, asset appreciation, and systemic access to financial tools.
Deep Dive: The Full Picture
The net worth of races isn’t a static snapshot—it’s a moving target shaped by forces older than the data tracking it. Before the Civil War, enslaved Black Americans contributed billions in unpaid labor, a debt the U.S. never repaid. After emancipation, Black families were denied land grants, excluded from agricultural subsidies, and systematically pushed into urban ghettos through discriminatory housing practices. The result? By the 1970s, white families had accumulated wealth at a rate 12 times faster than Black families, a divergence that only widened with each subsequent generation. Even today, the median white family has a net worth of $188,200, while the median Black family’s sits at $24,100—a gap that persists despite decades of civil rights progress. What’s less discussed is how this wealth gap plays out in real-time economic decisions. A white family with $100,000 in home equity can leverage that asset to start a business, send a child to college, or weather a layoff. A Black family with $20,000 in savings may lack the collateral for a small business loan or the buffer to avoid predatory financial products. The net worth of races isn’t just about dollars and cents—it’s about who gets to take risks and who is forced into survival mode. This isn’t theory; it’s the lived experience of millions, reinforced by data that shows Black and Hispanic families are twice as likely to face financial shocks that wipe out their savings.The Context You Need
To understand the net worth of races, you have to grasp two things: how wealth is built and who has been excluded from that process. Wealth isn’t just salary—it’s stocks, real estate, retirement accounts, and inherited assets. White families have benefited from centuries of untaxed wealth transfers, from land grants to home appreciation in predominantly white neighborhoods. Black and Hispanic families, meanwhile, have been shut out of these wealth-creating mechanisms through exclusionary zoning, discriminatory mortgage lending, and job discrimination that limited access to high-paying professions. The numbers tell a story of structural inequality. In 1983, the wealth ratio between white and Black families was 10:1. By 2019, it had grown to 13:1. The Great Recession of 2008 didn’t just widen the gap—it reset the baseline. White families lost 16% of their wealth on average; Black families lost 31%. The recovery didn’t bridge that divide because the tools to rebuild wealth—homeownership, stable employment, inheritance—weren’t equally distributed. The net worth of races isn’t a coincidence; it’s the culmination of policy, culture, and economics.The Mechanics
The mechanics of racial wealth disparity are less about individual failure and more about systemic exclusion. Take homeownership: white families own homes at a rate 28 percentage points higher than Black families. That’s not just a housing preference—it’s a wealth multiplier. A home isn’t just shelter; it’s an appreciating asset that builds equity over time. When Black families do buy homes, they’re more likely to be in high-cost, low-appreciation neighborhoods due to historical redlining maps that still influence lending today. Meanwhile, white families benefit from neighborhood effects—better schools, lower crime, and higher property values—that compound over generations. Then there’s the debt trap. Black and Hispanic borrowers are more likely to be targeted for subprime mortgages, payday loans, and high-interest credit cards, all of which erode net worth. Student loan debt exacerbates this: Black borrowers default at nearly twice the rate of white borrowers, not because they’re less educated but because they’re more likely to attend for-profit colleges with poor outcomes or take on debt for degrees that don’t translate to higher-paying jobs. The result? A negative wealth transfer where minority families pay more in interest and fees, further widening the gap.Details That Change the Picture
The net worth of races isn’t just about averages—it’s about who falls through the cracks. For example, Black women face a double penalty: they earn 38% less than white men and 21% less than white women, while also bearing the burden of caregiving roles that limit career advancement. Their median net worth? $5,000—less than half that of white women. Meanwhile, Asian families often get overlooked in these conversations, but their wealth stories are just as complex. Some subgroups, like Indian and Chinese Americans, have high median incomes and net worth, but others, like Cambodian and Vietnamese families, struggle with language barriers, low-wage employment, and lack of intergenerational wealth transfer. What’s often missing from the discussion is how public policy could reshape the net worth of races. Programs like the New Deal excluded Black farmers and domestic workers, while FHA mortgage programs in the 1930s explicitly barred Black families from homeownership. Today, proposals like baby bonds—where every child receives a trust fund at birth, funded by progressive taxation—could inject $6 trillion into the economy over a generation, disproportionately benefiting Black and Hispanic families. But political will remains the biggest hurdle. The net worth of races won’t close without direct wealth-building policies, not just income equality programs."Wealth isn’t just money—it’s power. And power in America has always been racialized." — Darrick Hamilton, economist and founder of the Institute on Assets and Social Policy
| Metric | White Families | Black Families |
|---|---|---|
| Median Net Worth (2022) | $188,200 | $24,100 |
| Homeownership Rate | 74% | 44% |
| Student Loan Debt Burden | Lower default rates, better repayment outcomes | Higher default rates, lower wealth accumulation |

Conclusion
The net worth of races isn’t a relic of the past—it’s a living, breathing measure of inequality that determines who thrives and who struggles in the economy. It’s not just about dollars; it’s about opportunity hoarding. White families have had 300 years of unbroken wealth accumulation, while Black and Hispanic families have faced centuries of extraction. The gap isn’t accidental; it’s the result of deliberate policy, cultural norms, and economic structures that favor some groups over others. Closing this divide won’t happen overnight, but it requires three things: acknowledging the history behind the numbers, implementing direct wealth-building policies, and shifting the cultural narrative from individual blame to systemic change. The net worth of races is more than a statistic—it’s a moral and economic imperative. Ignoring it means accepting a future where wealth inequality remains the most stubborn divider in America.Comprehensive FAQs
Q: Why does the net worth of races matter more than income inequality?
A: Income measures annual earnings, but wealth reflects accumulated assets, inheritance, and generational advantage. A family can have high income but zero wealth if they’re drowning in debt. The net worth of races exposes who has a financial safety net and who doesn’t—something income data can’t show.
Q: How did redlining directly impact the net worth of races?
A: Redlining—where banks denied mortgages to Black neighborhoods—meant Black families were locked out of homeownership, the primary wealth-building tool for white families. Even today, 90% of Black families live in neighborhoods that were once redlined, limiting their access to appreciating assets and quality schools.
Q: Can affirmative action or hiring programs close the net worth gap?
A: No. Affirmative action addresses income disparities by improving job access, but wealth gaps require asset-building policies like homeownership subsidies, wealth transfers, and student debt relief. Without direct wealth interventions, income gains won’t translate to closing the net worth divide.
Q: How does student loan debt disproportionately affect Black and Hispanic families?
A: Black borrowers are more likely to attend for-profit colleges with poor outcomes, take on higher debt loads for lower-paying degrees, and face higher default rates. This debt erodes net worth at a time when white families are building home equity and retirement savings.
Q: What’s the most effective policy to shrink the racial wealth gap?
A: Baby bonds—where every child receives a trust fund at birth, funded by progressive taxation—could inject $6 trillion into minority communities over a generation. Other solutions include wealth-building programs, closing the racial homeownership gap, and eliminating predatory lending in minority neighborhoods.
Q: Why do some Asian subgroups have high net worth while others don’t?
A: Wealth within Asian communities varies by immigration wave, education levels, and occupation. First-generation Chinese and Indian immigrants often have high incomes and savings, while Southeast Asian refugees face language barriers, low-wage jobs, and lack of intergenerational wealth transfer, leading to stark disparities even within the same racial category.
Q: How does the net worth of races affect political power?
A: Wealth translates to political influence—lobbying, campaign donations, and access to policymakers. White families, with 10x the wealth, have disproportionate power to shape policies that maintain their economic advantage. The net worth of races isn’t just economic; it’s a power imbalance that reinforces systemic inequality.
