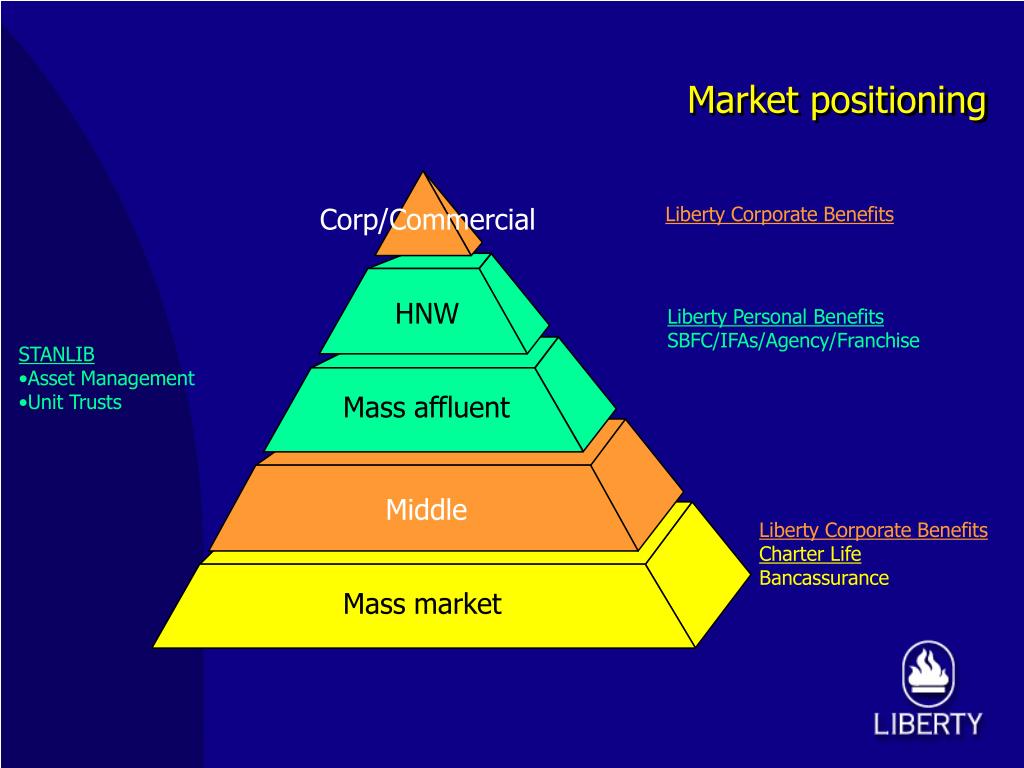
Breaking Down the Numbers
The financial thresholds separating these groups are fluid, but industry standards provide a framework. Mass affluent households are generally defined by liquid assets between $100,000 and $1 million, though some reports narrow this to $250,000–$500,000 for precision targeting. These individuals often represent the upper echelons of the middle class—doctors, executives, or tech founders with substantial savings but limited diversified portfolios. Their wealth is frequently concentrated in retirement accounts, primary residences, or high-yield savings, leaving little room for speculative investments. High net worth, conversely, begins at the $1 million mark (or higher, depending on the source), with ultra-high-net-worth (UHNW) thresholds starting at $30 million. The difference between mass affluent and high net worth isn’t just about the size of the bank account; it’s about the complexity of the financial ecosystem they inhabit. For mass affluent clients, financial planning revolves around cash flow management, tax-efficient savings, and protecting against unforeseen expenses. Their advisors focus on optimizing 401(k) contributions, refinancing mortgages, or navigating college tuition costs. High-net-worth individuals, however, deal with estate planning, dynastic trusts, and cross-border asset allocation. A mass affluent investor might consult a robo-advisor; an HNW client works with a team of specialists—attorneys, tax strategists, and private bankers. The distinction between mass affluent and high net worth also manifests in lifestyle: the former might dine at Michelin-starred restaurants occasionally, while the latter may own the restaurant or have a private jet on standby. The numbers don’t lie, but the behaviors they enable do.The Verified Baseline
Publicly available data from institutions like Credit Suisse and Capgemini confirms that mass affluent individuals outnumber HNW clients by a ratio of roughly 100:1. In the U.S., there are approximately 21 million households with liquid assets exceeding $100,000, compared to just 2.1 million HNW individuals. This disparity explains why financial services firms allocate more resources to mass affluent marketing—there are simply more of them. Verified figures also show that mass affluent households are more likely to be concentrated in urban centers, where salaries and property values inflate liquidity. High-net-worth individuals, meanwhile, are geographically dispersed, with significant populations in global hubs like London, Hong Kong, and Dubai, where tax optimization and privacy are priorities. The behavioral divide is equally measurable. Studies indicate that mass affluent investors are more reactive to market volatility, often pulling funds during downturns, while HNW clients maintain long-term strategies regardless of short-term fluctuations. This resilience stems from diversified portfolios that include private equity, hedge funds, and illiquid assets like fine wine or vintage cars—holdings that mass affluent individuals rarely access. The clearest verified difference between mass affluent and high net worth lies in their relationship with risk: the former seeks stability; the latter, controlled exposure to high-reward opportunities.What the Estimates Suggest
Industry estimates suggest that the mass affluent segment is growing faster than HNW populations, driven by remote work, stock market appreciation, and rising home values. According to some projections, the number of mass affluent households could swell by 20% over the next decade, while HNW growth remains stagnant at around 3–5% annually. This shift has led private banks and wealth managers to reallocate resources, with firms like UBS and Goldman Sachs expanding mass affluent divisions. Estimates also indicate that mass affluent clients are more likely to engage with digital banking tools, whereas HNW individuals prefer human advisors for complex transactions. The implied difference between mass affluent and high net worth in this context is one of accessibility: the former embraces technology; the latter demands personalized service. Hedged estimates further suggest that HNW individuals hold a disproportionate share of global wealth—around 40% of the total, despite comprising less than 1% of the population. Their spending power is concentrated in niche markets: luxury real estate, private aviation, and high-end art. Mass affluent spending, by contrast, fuels broader economic sectors like education, healthcare, and mid-tier travel. The estimated difference between mass affluent and high net worth in consumption patterns highlights why brands must tailor their approaches. A watchmaker like Patek Philippe might target HNW clients with bespoke timepieces, while a retailer like Neiman Marcus designs mass affluent campaigns around limited-edition collaborations.
Case Study: A Closer Look
Consider the hypothetical scenario of two professionals: Dr. Elena Vasquez, a mass affluent cardiologist in Austin, Texas, and Marcus Chen, a high-net-worth entrepreneur in Singapore. Dr. Vasquez earns $350,000 annually, owns a $900,000 home, and has $400,000 in retirement accounts and a high-yield savings fund. Her financial advisor helps her maximize her 401(k) contributions and refinance her mortgage to secure a lower rate. Marcus Chen, meanwhile, co-founded a fintech startup sold for $200 million five years ago. His net worth exceeds $50 million, and his wealth is diversified across a family office, private equity stakes, and a collection of rare automobiles. His advisors focus on dynasty trusts, offshore holdings in the Cayman Islands, and philanthropic vehicles to reduce his taxable estate. The practical difference between mass affluent and high net worth in this case is stark. Dr. Vasquez’s wealth is tied to her career and a single property; Marcus Chen’s is decentralized, with assets spanning continents. When Dr. Vasquez considers a vacation home, she researches mortgage options and resale values. Marcus Chen acquires a $20 million villa in Tuscany as an investment, leveraging his family office’s global network to secure favorable terms. Their financial lives operate on different scales, but both require expertise—just of different kinds."The mass affluent client asks, ‘How do I protect what I have?’ The high-net-worth client asks, ‘How do I grow what I have while ensuring it never becomes a liability?’ The questions themselves reveal the divide." — Sophia Lin, Head of Private Wealth at a top-tier Asian bank
| Factor | Estimated Impact |
|---|---|
| Liquidity | Mass affluent: ~30–50% of assets liquid; HNW: 70–90%+ liquid or easily convertible. |
| Risk Tolerance | Mass affluent: Prefer conservative instruments (ETFs, bonds); HNW: Willing to allocate 10–30% to private equity or alternatives. |
| Advisor Relationship | Mass affluent: Often use digital platforms or hybrid advisors; HNW: Exclusive relationships with boutique firms. |
What This Means Going Forward
The evolving difference between mass affluent and high net worth will shape financial services in the coming years. As millennials and Gen Z enter the mass affluent bracket, demand for flexible, tech-driven financial tools will rise. High-net-worth clients, meanwhile, will continue to seek bespoke solutions, from AI-driven portfolio management to blockchain-based asset tracking. The blurring lines—such as the rise of "quiet luxury" appealing to both segments—highlight the need for adaptive strategies. Firms that fail to distinguish between these groups risk alienating one or the other; those that succeed will dominate niche markets. Regulatory changes will further accentuate the divide. Stricter reporting requirements for HNW clients (e.g., FATCA, CRS) may push more affluent individuals into the mass affluent category by obscuring their true net worth. Meanwhile, mass affluent clients will benefit from expanded access to previously exclusive products, like fractional ownership in private jets or art syndication. The future of the difference between mass affluent and high net worth lies in how well institutions can navigate this shifting landscape—balancing scalability with personalization.
Conclusion
The difference between mass affluent and high net worth is more than a matter of dollar signs; it’s a reflection of distinct financial mindsets, lifestyles, and market influences. Mass affluent individuals build wealth through discipline and opportunity, while high-net-worth individuals leverage complexity and scale. Understanding this divide isn’t just for bankers or luxury brands—it’s for anyone seeking to engage with these segments effectively. The key takeaway? Wealth management isn’t one-size-fits-all. The strategies that work for a mass affluent professional won’t suffice for an HNW family, and vice versa. As the global economy continues to evolve, the ability to recognize—and respect—these distinctions will separate the successful from the stagnant. For the mass affluent, the path to high net worth begins with education and access. For the already wealthy, the challenge lies in preserving and expanding their legacy. The gap between mass affluent and high net worth isn’t a chasm to be bridged but a spectrum to be understood. Those who master this distinction will thrive in an era where financial literacy and elite networking are equally valuable currencies.Comprehensive FAQs
Q: Can a mass affluent individual become high net worth?
A: Absolutely. Many mass affluent individuals transition to high net worth through career advancements, entrepreneurship, or strategic investments. The critical factor is liquidity—consistently growing investable assets beyond the $1 million threshold. However, the process requires disciplined financial planning, as sudden wealth spikes (e.g., stock options, inheritance) don’t always translate to sustainable net worth without proper management.
Q: Do high-net-worth individuals pay higher taxes?
A: Not inherently, but their tax strategies are far more complex. HNW individuals often use trusts, offshore accounts, and legal entities to minimize taxable exposure. Mass affluent taxpayers, by contrast, typically rely on standard deductions, retirement account contributions, and capital gains exemptions. The key difference lies in access to tax optimization tools—something mass affluent clients rarely have unless they engage premium advisory services.
Q: Are there financial products designed specifically for mass affluent clients?
A: Yes. Many banks and fintech firms now offer tiered products targeting mass affluent investors, such as premium credit cards with higher limits, exclusive investment platforms with lower minimums, and digital wealth management tools. These products bridge the gap between mainstream banking and private wealth services, often with features like embedded insurance or cash-back rewards tied to luxury purchases.
Q: How do high-net-worth individuals typically structure their wealth?
A: HNW individuals rarely hold assets in their personal names. Instead, they use structures like family limited partnerships (FLPs), private foundations, or international business companies (IBCs) to protect and grow wealth. Mass affluent clients, lacking the resources for such entities, rely on simpler structures like joint tenancy accounts or basic trusts. The structural difference is a function of scale—HNW wealth requires legal and financial engineering to remain secure and tax-efficient.
Q: What’s the biggest misconception about mass affluent vs. high net worth?
A: The assumption that all affluent individuals are alike. Many believe that once someone crosses a certain income threshold, their financial needs and behaviors converge. In reality, the psychological and operational differences between mass affluent and high net worth are profound. A mass affluent client might celebrate a $500,000 portfolio, while an HNW individual with $50 million might view it as a rounding error. The misconception leads to poor service delivery when firms treat these groups as homogeneous.
