The Complete Overview of What Does a Personal Statement of Net Worth Include
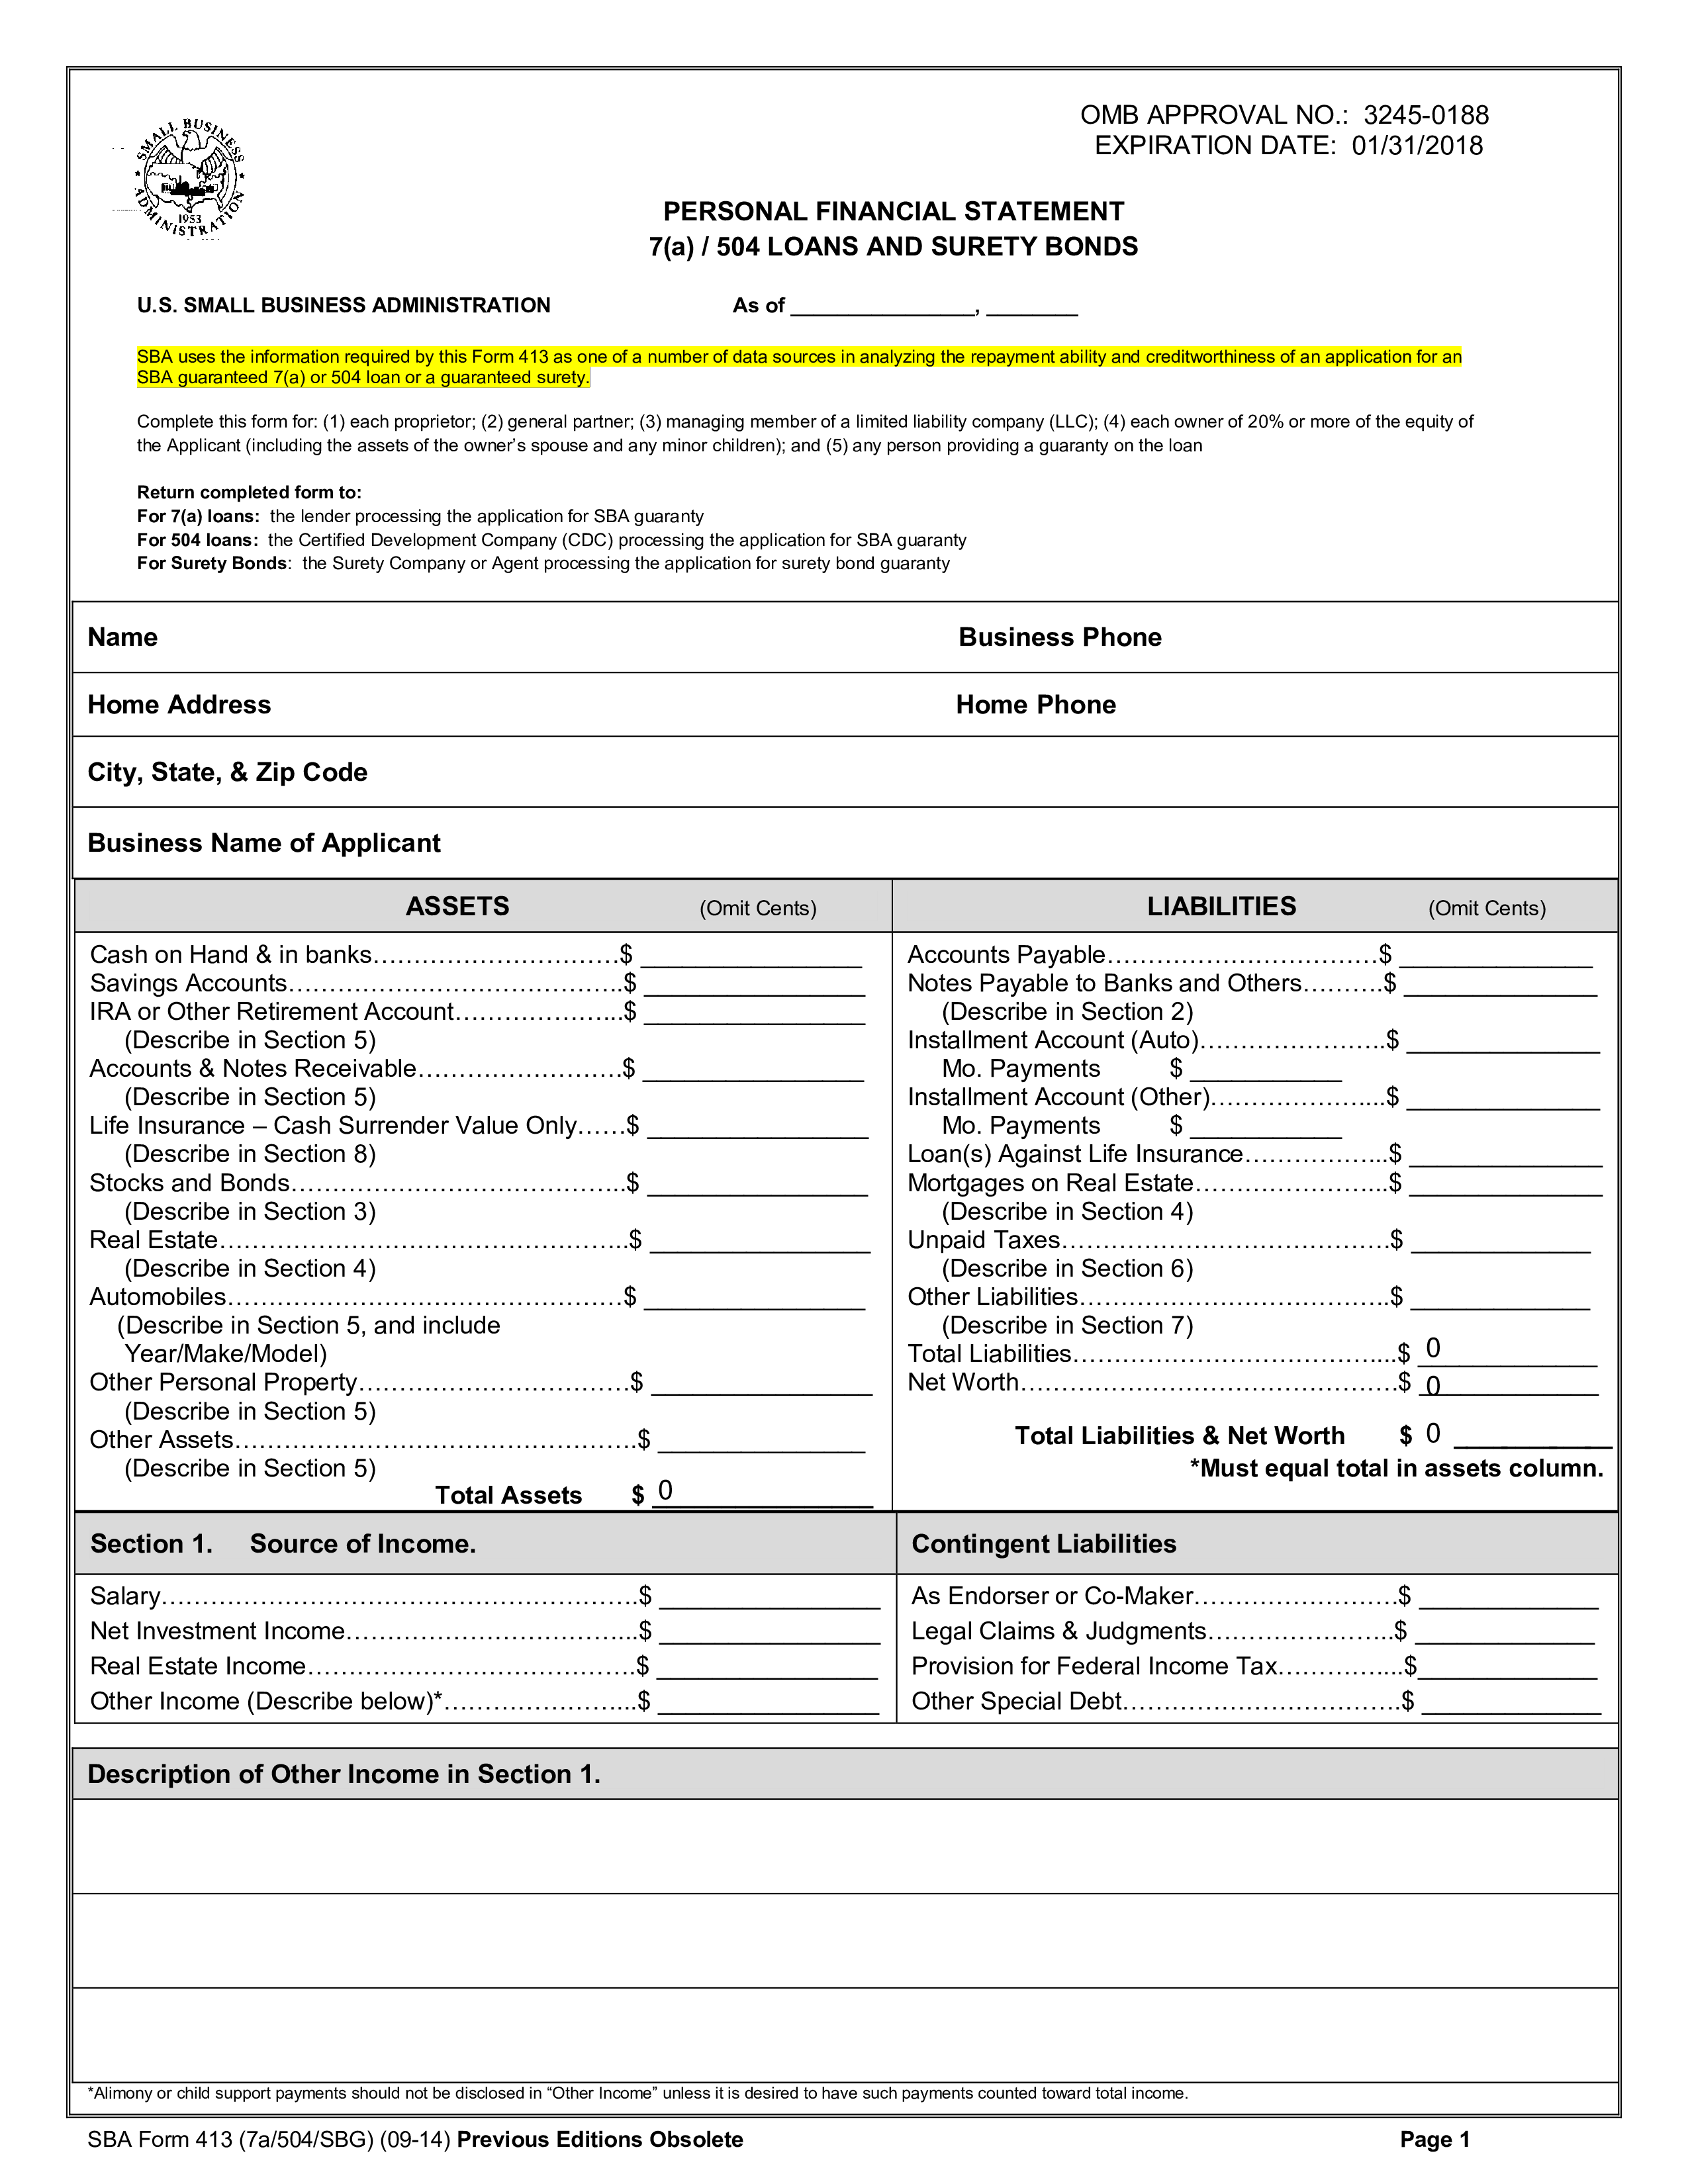
A personal statement of net worth is a living document, not a static one. It evolves with market fluctuations, career changes, and life events—like a marriage, a stock market crash, or an unexpected inheritance. The core purpose is to provide clarity: to separate what you own from what you owe, and to quantify the gap between the two. This isn’t just academic; it’s the foundation for retirement planning, risk assessment, and even lifestyle decisions. Someone with a net worth of $5 million in illiquid assets (e.g., a family business) faces entirely different challenges than someone with the same figure in diversified investments. The document itself can range from a handwritten list to a professionally prepared report, often used in legal proceedings or financial disclosures. For instance, during a divorce, courts may require both parties to submit what does a personal statement of net worth include to ensure equitable division of assets. Similarly, entrepreneurs pitching to venture capitalists must present a net worth statement to demonstrate personal stake in the business. The granularity matters: a vague "assets around $1 million" won’t suffice when a lender or investor needs to see the breakdown of a $200,000 vintage wine collection versus a $500,000 stake in a private equity fund.Historical Background and Evolution
The concept of tracking net worth dates back centuries, though its modern form emerged with the industrial revolution. Before then, wealth was often tied to land, livestock, or guild membership—assets that were easily auditable by local authorities. The rise of banking in the 18th century introduced the need for more precise financial documentation, particularly among merchants and aristocrats. By the 19th century, personal balance sheets became standard for the elite, used to secure loans, settle estates, or avoid creditors. The 20th century formalized the practice, especially in the U.S., where the Internal Revenue Service began requiring asset disclosures for tax purposes. The 1980s saw a shift as financial advisors popularized net worth statements for middle-class clients, framing it as a tool for goal-setting rather than just compliance. Today, digital tools like Mint, YNAB, and even blockchain-based platforms have democratized the process, allowing individuals to generate what does a personal statement of net worth include with a few clicks. Yet, the core principle remains unchanged: net worth is the difference between what you control and what controls you.Core Mechanisms: How It Works
At its simplest, the formula is straightforward: Net Worth = Total Assets – Total Liabilities. But the devil lies in the classification. Assets are divided into liquid (cash, stocks, bonds) and illiquid (real estate, art, collectibles), while liabilities include mortgages, loans, credit card debt, and even unpaid taxes. The challenge? Valuing assets accurately. A primary residence might be appraised at $800,000, but if the market dips, its true value could be $650,000—an omission that skews the entire statement. Professionals often categorize assets further: - Tangible assets: Property, vehicles, jewelry. - Intangible assets: Patents, royalties, digital assets (e.g., a domain portfolio). - Human capital: Potential future earnings (common in startup founder statements). Liabilities, meanwhile, aren’t just debts—they include pending legal judgments, alimony obligations, or even the estimated cost of long-term care. The statement’s power lies in its honesty. A financial planner might advise a client to exclude a sentimental heirloom worth $50,000 if it’s not insured, but omitting it entirely could misrepresent the true financial picture.Key Benefits and Crucial Impact
The most immediate benefit of a net worth statement is clarity. It forces individuals to confront their financial reality, whether they’re drowning in debt or sitting on untapped equity. For high-net-worth families, it’s a tool for succession planning—identifying which assets to pass down and which to liquidate to cover estate taxes. In 2021, the IRS reported that estates worth over $12 million triggered federal tax liabilities, making precise asset valuation critical for heirs. Beyond personal use, the statement serves as a negotiation lever. During a divorce, a spouse with a net worth statement can prove hidden assets (e.g., offshore accounts) or inflated liabilities (e.g., a partner’s business debts). Investors use it to assess a founder’s skin in the game; if a startup CEO lists a $1 million net worth but 90% of it is tied to the company’s valuation, investors may question their commitment."A net worth statement isn’t about vanity—it’s about survival. The moment you realize your largest asset is a depreciating car loan, you’ve got a problem." — Jane Smith, Certified Financial Planner (CFP) and author of Wealth Without Illusion
Major Advantages
- Debt management: Identifies high-interest liabilities that should be prioritized for repayment.
- Insurance coverage gaps: Reveals assets (e.g., a rare coin collection) that may need specialized policies.
- Tax optimization: Highlights deductions (e.g., charitable donations, retirement accounts) to reduce liabilities.
- Investment strategy alignment: Shows whether assets are diversified or concentrated in volatile sectors.
- Legacy planning: Helps allocate assets to heirs while minimizing tax burdens.

Comparative Analysis
| Personal Net Worth Statement | Business Financial Statement |
|---|---|
| Focuses on individual assets/liabilities (e.g., personal real estate, student loans). | Covers company assets (inventory, equipment) and liabilities (payroll, vendor debts). |
| Used for personal tax filings, divorce, or loan applications. | Required for investors, audits, or SEC filings. |
| May include intangibles like professional licenses or side-hustle equity. | Excludes personal holdings unless the business is a pass-through entity. |
| Updated annually or as major life events occur. | Prepared quarterly or annually, per accounting standards. |
| Privacy concerns limit distribution (e.g., shared only with spouses or advisors). | Publicly disclosed in some cases (e.g., publicly traded companies). |
Future Trends and Innovations
The next decade will see net worth statements become more dynamic, integrating real-time data feeds from banks, crypto wallets, and even smart contracts. Blockchain technology could automate asset verification, reducing fraud in high-stakes scenarios like divorce or inheritance disputes. For example, a NFT portfolio’s value could be pulled directly from marketplace APIs, eliminating manual entries. Artificial intelligence is poised to personalize these statements further. Instead of static snapshots, AI might predict how a stock market correction or a new mortgage rate would impact net worth within 30 days. Wealth managers are already experimenting with "liquidity scores," which rank assets by how quickly they can be converted to cash—a critical metric for entrepreneurs or freelancers facing irregular income streams.
Conclusion
Understanding what does a personal statement of net worth include is less about crunching numbers and more about gaining financial agency. It’s the difference between reacting to a market crash and strategically repositioning assets before it hits. For the average professional, it’s a wake-up call; for the ultra-wealthy, it’s a boardroom necessity. The statement’s true value lies in its honesty—whether you’re a recent graduate with a negative net worth or a retiree with a diversified portfolio, the exercise of compiling it forces a reckoning with reality. The process isn’t just mathematical; it’s psychological. Many people avoid calculating their net worth because they fear the result. But that fear is the point. Financial health isn’t static, and neither should the document that tracks it. Whether you’re using a free template or hiring a CPA to audit your offshore accounts, the goal remains the same: to turn confusion into control.Comprehensive FAQs
Q: Do I need a professional to prepare my net worth statement?
A: Not necessarily. Basic statements can be created using spreadsheets or apps like Personal Capital. However, if you own complex assets (e.g., trusts, international properties) or face legal disputes, a certified financial planner or CPA is advisable to ensure accuracy and compliance.
Q: Should I include sentimental items like heirlooms?
A: Only if they have verifiable value. Sentimental items without appraisals or insurance coverage should be noted separately but not factored into the net worth calculation. Excluding them entirely could understate your true financial position.
Q: How often should I update my net worth statement?
A: At minimum, annually. Major life events—marriage, divorce, inheritance, or significant market changes—warrant an immediate update. Automated tools can sync with bank accounts to reduce manual effort.
Q: Can a negative net worth be beneficial?
A: Yes, if it reflects strategic debt. For example, a negative net worth due to a mortgage on a rental property generating income is different from one driven by credit card debt. The key is ensuring liabilities are leveraged productively.
Q: How do I handle assets with fluctuating values, like cryptocurrency?
A: Record the value at the time of the statement, using reputable exchanges or appraisers. For highly volatile assets, consider noting a range (e.g., "Bitcoin: $25,000–$30,000 based on 30-day average").
Q: Is there a standard format for net worth statements?
A: No universal standard, but most follow a two-column layout: Assets (cash, investments, property) and Liabilities (debts, taxes owed). Legal or financial institutions may require specific formats, so always check requirements.
Q: What if I discover discrepancies between my statement and a lender’s valuation?
A: Discrepancies often arise from outdated appraisals or differing valuation methods. For example, a lender may use a conservative estimate for real estate. Document your sources and consult a professional to resolve conflicts, especially in high-stakes scenarios like refinancing.
Q: Can I use a net worth statement to qualify for a loan?
A: Some lenders, particularly private or peer-to-peer platforms, may request it to assess collateral or repayment capacity. Traditional banks typically rely on income and credit scores, but a strong net worth statement can supplement your application, especially for self-employed borrowers.
