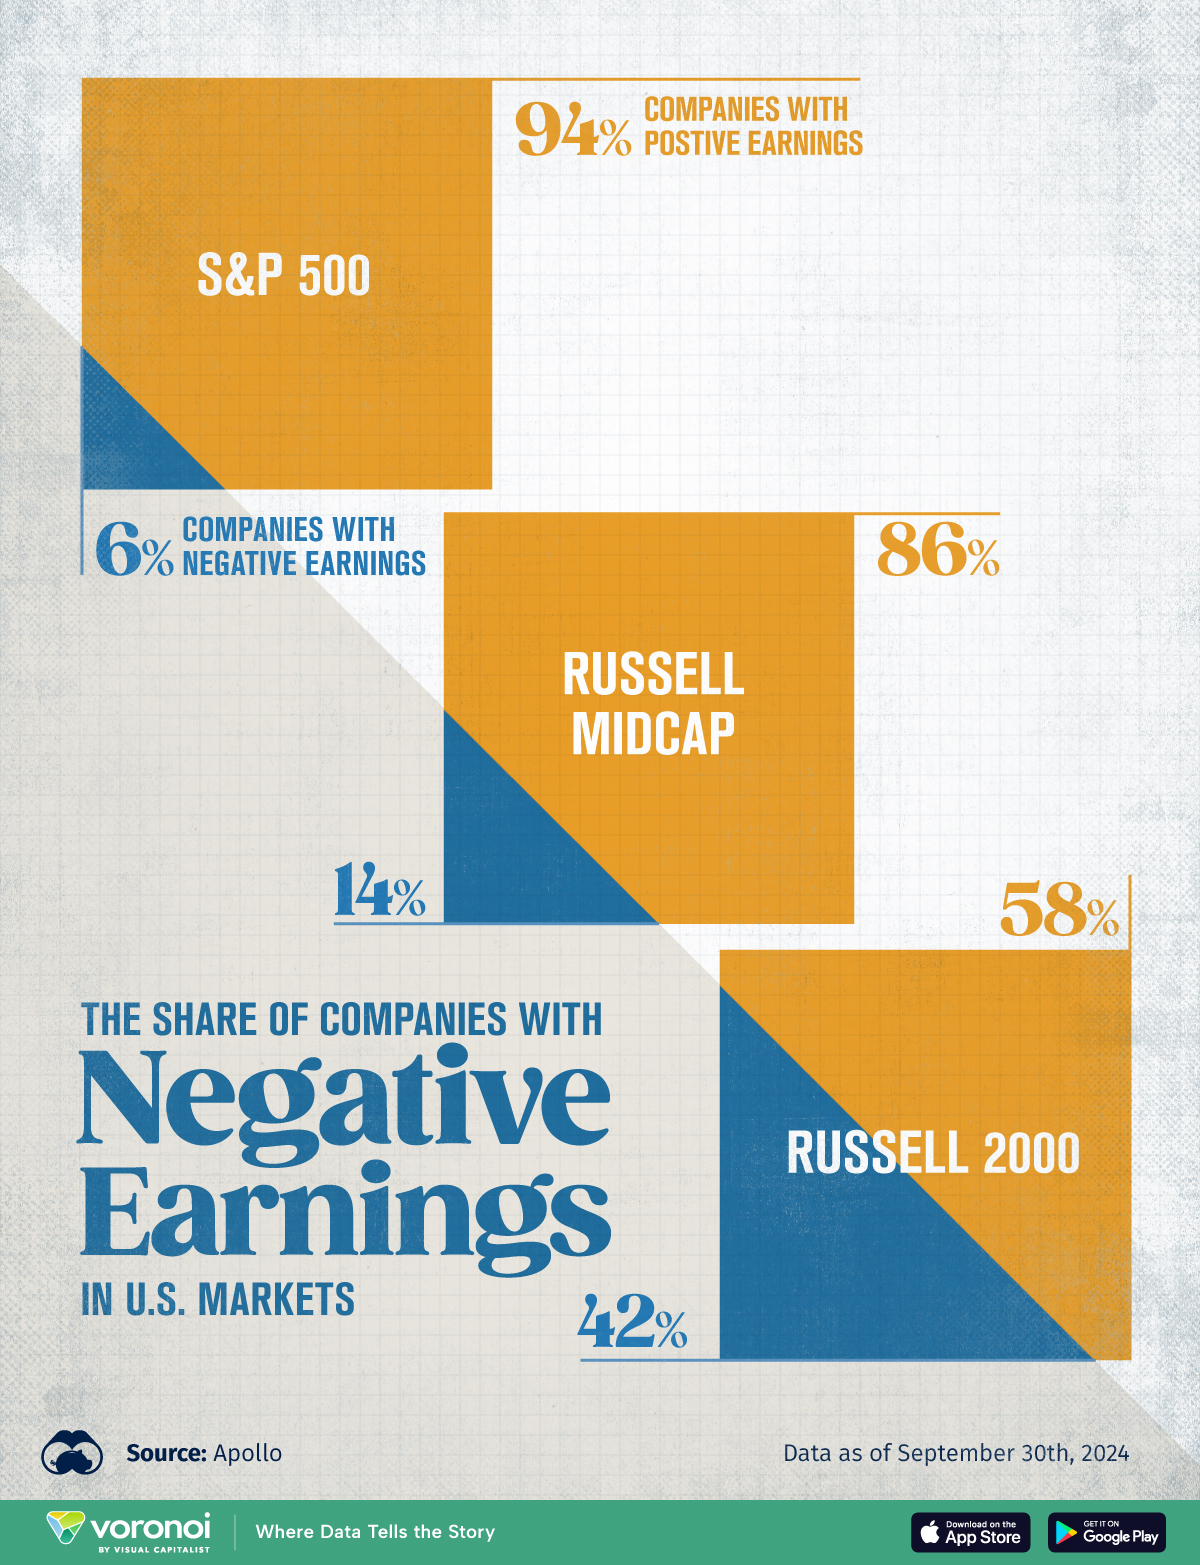
7 Things Worth Knowing About Large Companies With Negative Net Worth
The persistence of companies with negative net worth—particularly those of significant scale—reveals deeper truths about corporate finance, investor psychology, and regulatory oversight. These entities often defy conventional logic, yet their survival strategies offer critical lessons. Below are seven key insights into how and why they endure.1. Negative net worth doesn’t always mean insolvency
A negative net worth (liabilities exceeding assets) doesn’t automatically equate to bankruptcy. Many large companies with negative net worth remain solvent because they generate enough cash flow to service debt and fund operations. Consider WeWork, which at its peak had a net worth estimated in the negative billions yet continued to secure billions in funding. The distinction lies in operating cash flow vs. net worth: a company can bleed equity but still have the liquidity to pay bills, at least in the short term. This disconnect is why valuation metrics like price-to-earnings (P/E) ratios become unreliable for such firms—earnings may be negative, but revenue (and hype) can keep investors engaged. The danger arises when debt maturities outpace revenue growth. Companies like large companies with negative net worth in the energy sector (e.g., some oil majors) have historically relied on asset sales or commodity price spikes to bridge gaps. When those strategies fail, the result is often restructuring—or worse. The key variable is time: how long can a company sustain losses before creditors or shareholders force a reckoning?2. Accounting tricks and regulatory arbitrage
Public companies employ a range of accounting techniques to mask negative net worth, none more controversial than off-balance-sheet financing. Leases, joint ventures, and securitized assets can artificially inflate asset values while deferring liabilities. Enron’s collapse in 2001 exposed how aggressively firms could exploit such loopholes, but the practice persists in more subtle forms. For example, large companies with negative net worth in the tech sector often defer revenue recognition (e.g., multi-year software contracts) to smooth earnings reports, even if the underlying cash flow is weak. Regulators play a dual role here. On one hand, bodies like the Securities and Exchange Commission (SEC) enforce disclosure rules that require transparency about financial health. On the other, accounting standards (e.g., International Financial Reporting Standards, or IFRS) allow significant judgment calls in valuing assets like intellectual property or goodwill—areas where companies with negative net worth have ample room to manipulate figures. The result? A system where investors must sift through footnotes to uncover the true financial picture, often after the fact.3. The role of venture capital and speculative funding
Private equity and venture capital firms are among the most aggressive backers of large companies with negative net worth, betting that scale and market dominance will eventually translate to profitability. Consider Uber and Lyft, which for years operated at massive losses while burning through capital in a race to dominate ride-sharing. Their negative net worth was less a red flag than a feature: investors were willing to fund growth at any cost, assuming an exit strategy (IPO or acquisition) would materialize. This model thrives in sectors with network effects (where scale begets dominance) or regulatory barriers (limiting competition). The risk is that this speculative funding creates a zombie economy—companies that would collapse without constant infusions of capital. When funding dries up (as it did for many companies with negative net worth post-2022), the result is often fire sales or bankruptcy. The lesson? Negative net worth isn’t inherently fatal, but it is a signal that a company’s survival depends on external capital—not self-sustaining profitability.4. Government and industry subsidies as lifelines
Some of the most persistent large companies with negative net worth are propped up by implicit or explicit subsidies. Airlines like Delta and United have historically operated with negative equity but remain viable due to government bailouts, fuel subsidies, or infrastructure investments. Similarly, companies with negative net worth in the defense or aerospace sectors often rely on long-term contracts with guaranteed margins, allowing them to sustain losses on other ventures. The most extreme examples emerge in state-backed industries, where governments use subsidies to maintain strategic assets. Saudi Aramco, despite its massive revenue, has faced scrutiny over its reported net worth due to the way it accounts for oil reserves and sovereign wealth funds. The takeaway? For some large companies with negative net worth, solvency isn’t a financial question—it’s a political one.5. The illusion of "growth at all costs"
The tech industry has popularized the mantra that companies with negative net worth are simply "investing in growth." This narrative gained traction during the dot-com bubble and resurfaced in the 2010s with firms like large companies with negative net worth in the FAANG ecosystem (e.g., Amazon in its early years). The logic is seductive: if a company can grow revenue faster than it burns cash, the losses are temporary. But history shows this strategy has a shelf life. When growth slows (as it did for many companies with negative net worth in 2022–2023), the music stops—and the unsustainable becomes unsustainable. The danger is that this growth-at-all-costs mentality becomes self-reinforcing. Investors, fearing missing out on the next big thing, pour money into large companies with negative net worth even as fundamentals deteriorate. The result? A feedback loop where poor performance is rewarded with more capital, delaying the inevitable reckoning."Negative net worth is a feature, not a bug—if you’re playing the long game. The problem arises when the long game turns into a Ponzi scheme, and everyone’s counting on the next sucker to arrive." — A former CFO of a publicly traded tech firm with persistent losses
6. The employee and supplier ripple effect
While investors and executives may focus on balance sheets, the real-world impact of large companies with negative net worth falls on employees and suppliers. Layoffs, wage freezes, and delayed payments become inevitable when cash flow is strained. Consider large companies with negative net worth in retail (e.g., J.C. Penney, Sears) or manufacturing (e.g., some legacy automakers): their financial distress directly translates to job losses and supply chain disruptions. Even "healthy" firms with negative equity can create instability if their instability spills over into related industries. The irony is that some of these companies are too big to fail—yet too large to restructure cleanly. Their size makes bankruptcy messy, prolonging uncertainty for stakeholders. For employees, the risk isn’t just unemployment; it’s the erosion of pensions, benefits, and even community stability when a major employer collapses.7. The valuation paradox: Why markets ignore net worth
Public markets often price large companies with negative net worth based on future potential rather than current fundamentals. This disconnect is most pronounced in sectors like biotech, semiconductors, and green energy, where firms may have no revenue but are valued on the promise of a breakthrough. Tesla, for example, operated with negative equity for years yet traded at a premium based on its EV market dominance. The same logic applies to companies with negative net worth in AI or quantum computing—investors bet on "moonshot" potential, not today’s profits. The problem is that this valuation model assumes perpetual growth. When that growth stalls (as it has for many large companies with negative net worth post-2020), the correction can be brutal. The lesson? Markets may ignore net worth, but they don’t ignore cash flow. At some point, the music stops—and the companies that relied on hype over substance are the first to fall.How These Facts Connect
The persistence of large companies with negative net worth isn’t random; it’s the product of structural incentives in finance, technology, and governance. These firms thrive at the intersection of speculative capital, regulatory flexibility, and strategic subsidies—a trio that allows them to operate outside traditional profitability metrics. The result is a financial ecosystem where net worth becomes secondary to growth narratives, political influence, or market momentum. What’s revealing is how these factors interact. Accounting tricks and regulatory arbitrage delay the day of reckoning, while venture capital and government support provide oxygen. Meanwhile, employee and supplier costs are externalized, and market valuations are detached from reality—until they’re not. The system rewards short-term survival over long-term sustainability, creating a cycle where large companies with negative net worth become the norm rather than the exception. The table below compares the key drivers behind these firms’ survival:| Factor | Mechanism | Example | Risk |
|---|---|---|---|
| Speculative Funding | Venture capital bets on future dominance | Uber, Lyft (pre-profitability) | Funding drought triggers collapse |
| Regulatory Loopholes | Off-balance-sheet financing, deferred revenue | WeWork, Enron (pre-collapse) | Audit failures expose fraud |
| Government Subsidies | Industry bailouts, fuel/energy subsidies | Delta Airlines, Aramco | Policy shifts remove support |
| Market Hype | Valuation based on potential, not profits | Tesla (early years), AI startups | Correction wipes out paper wealth |
Conclusion
The existence of large companies with negative net worth is a symptom of a financial system that prioritizes momentum over fundamentals. These firms are not outliers; they are the product of accounting rules that reward growth over profitability, investors who chase hype, and regulators who turn a blind eye to creative balance sheets. The danger isn’t that these companies will disappear—it’s that their survival distorts market signals, inflates asset bubbles, and delays necessary corrections. For stakeholders, the lesson is clear: negative net worth isn’t a death sentence, but it is a warning sign. The companies that endure are those that can transition from burning cash to generating it—whether through innovation, cost-cutting, or strategic pivots. The rest are living on borrowed time, propped up by a combination of blind optimism, political will, and financial engineering. The day those supports fail will be the day the truth catches up to the balance sheet.Comprehensive FAQs
Q: Can a company with negative net worth still be profitable?
A: Not in the traditional sense. Profitability (positive earnings) and negative net worth can coexist if a company’s operating cash flow is strong enough to service debt and fund growth. However, true profitability—where earnings cover all expenses—is rare for large companies with negative net worth. Most rely on deferred revenue, asset sales, or subsidies to stay afloat. The key distinction is between accounting profit (which may be positive) and cash flow profit (which often isn’t).
Q: Are there industries where negative net worth is more common?
A: Yes. Sectors with high capital requirements, long sales cycles, or regulatory barriers are hotbeds for companies with negative net worth:
- Tech/Software: Firms betting on future dominance (e.g., AI, cloud computing).
- Biotech/Pharma: Companies with no revenue but expensive R&D pipelines.
- Energy/Oil & Gas: Legacy firms with high debt and volatile commodity prices.
- Retail/Airlines: Asset-heavy industries reliant on subsidies or scale.
Q: How do investors justify putting money into companies with negative net worth?
A: Investors use several rationales, though not all hold up under scrutiny:
- Growth Narrative: "We’re investing in future revenue streams." (Risk: Growth may never materialize.)
- Market Dominance: "First-mover advantage ensures long-term profits." (Risk: Competitors may disrupt the model.)
- Asset Fire Sale: "The company will be acquired before it runs out of cash." (Risk: No buyer may emerge.)
- Regulatory Moat: "Government contracts or monopolies guarantee cash flow." (Risk: Policy changes can remove protections.)
Q: What happens when a large company with negative net worth can’t raise more capital?
A: The options are grim, typically following this trajectory:
- Cost-Cutting: Layoffs, wage freezes, supplier delays (short-term relief).
- Asset Sales: Selling divisions or IP to raise cash (often at a discount).
- Restructuring: Bankruptcy filings (Chapter 11 in the U.S.) to reorganize debt.
- Liquidation: If restructuring fails, assets are sold piecemeal, and creditors take losses.
Q: Can a company with negative net worth ever recover?
A: Yes, but it requires three critical conditions:
- Revenue Growth: Sales must outpace burn rate (e.g., Tesla post-2018).
- Debt Reduction: Asset sales or equity raises to shrink liabilities.
- Profitability Shift: Moving from "growth at all costs" to cash flow positive operations.
Q: Why do regulators allow companies with negative net worth to operate?
A: Regulators face a trade-off between transparency and stability:
- Market Confidence: Forcing a large company with negative net worth into bankruptcy could trigger broader economic shocks (e.g., a major bank or airline collapsing).
- Accounting Flexibility: Rules like IFRS or GAAP allow judgment calls on asset valuation, giving firms room to "clean up" balance sheets.
- Political Pressure: Industries like defense, energy, or agriculture often have lobbying power to avoid strict oversight.
- Investor Protection Theories: Some argue that letting markets correct (via share price declines) is a softer form of regulation than forced liquidation.
Q: Are there red flags that a company with negative net worth is in trouble?
A: Yes. Watch for these warning signs:
- Rising Debt-to-Equity Ratio: Liabilities growing faster than assets.
- Negative Free Cash Flow: Even if earnings are positive, if the company isn’t generating cash, it’s unsustainable.
- Dependence on New Funding: Frequent equity raises or debt issuances to stay afloat.
- Executive Turnover: Sudden CFO or CEO changes often signal internal panic.
- Supply Chain Issues: Vendors or employees reporting delayed payments.
- Valuation Disconnect: Trading at a premium despite no path to profitability (e.g., meme stocks or hype-driven firms).
