
Breaking Down the Numbers
Publicly available data on tattoo parlours insurance costs is scarce, as insurers treat pricing as proprietary. However, industry reports and broker surveys reveal a pattern: liability insurance for tattoo studios typically costs between 1% and 3% of gross annual revenue, with equipment coverage adding another 0.5% to 1.5%. For a mid-sized parlour generating £200,000 yearly, that translates to insurance expenses in the £3,000 to £9,000 range, depending on claims history and coverage limits. Smaller operations or mobile artists often pay a flat fee, sometimes as low as £200, but with significantly lower payout caps. The most critical factor in determining premiums is the studio’s claims history and location. Urban centres with higher foot traffic—think London, Manchester, or Brighton—see premiums spike due to increased liability risks. Studios in areas with strict health regulations (e.g., California or parts of Europe) may also face higher costs for compliance-related coverage. Meanwhile, rural or low-traffic parlours might qualify for discounts, though the trade-off is often lower coverage limits that leave them vulnerable to catastrophic losses.The Verified Baseline
Every tattoo parlour in the UK must comply with Public Liability Insurance as a minimum legal requirement, with coverage typically starting at £2 million. This protects against third-party injuries or property damage, such as a client slipping on blood or ink spills damaging nearby equipment. The Health and Safety Executive (HSE) does not mandate specific insurance types for tattooing, but local councils may enforce additional rules, particularly around biohazard waste disposal and sharps handling. Failure to meet these can result in fines or forced closures, making insurance a non-negotiable operational cost. Equipment breakdowns are another verified risk. A single malfunctioning tattoo machine can halt operations for days, costing hundreds in lost revenue. Standard tattoo parlours insurance policies often include business equipment coverage, but exclusions for "wear and tear" or "electrical surges" are common. Studios that invest in high-end machines—such as those using rotary or coil systems—may need to supplement their policies with specialized equipment insurance, which can add £100 to £300 annually depending on the value of the gear.What the Estimates Suggest
Industry estimates suggest that tattoo parlours insurance for a single-artist studio in a low-risk area could run around £400 to £800 per year, while a three-artist shop in a high-traffic location might see premiums hovering near £2,000 to £4,000. These figures are fluid, however, as insurers adjust rates based on real-time claims data. For example, a surge in allergic reaction lawsuits—often tied to ink quality or aftercare advice—could push premiums upward in certain regions. Brokers report that professional indemnity insurance, which covers errors like botched tattoos or misrepresented designs, adds another £200 to £600 annually to the total. Speculation among insurers and studio owners also points to an emerging trend: cyber liability coverage is becoming more relevant as tattoo parlours adopt digital booking systems and store client data. While rare today, a data breach—such as a hacked appointment calendar exposing client addresses—could expose studios to £5,000 to £15,000 in fines under GDPR, depending on the scale. Some insurers are beginning to offer cyber add-ons for tattoo businesses, though uptake remains low due to the perceived low risk. The long-term impact of this shift could reshape tattoo parlours insurance packages, particularly as contactless payments and cloud-based client records become standard.
Case Study: A Closer Look
In 2021, a Brighton tattoo parlour with two artists faced a £120,000 lawsuit after a client developed a severe infection from a contaminated needle. The studio’s £2 million public liability policy covered the medical costs, but the £50,000 in lost revenue during the three-month investigation was not reimbursed under their basic plan. The owners had opted for a £600 annual premium to save money, only to realize their excess was set at £10,000—meaning they bore the first portion of any claim. The experience forced them to switch to a specialized tattoo insurance provider, increasing their annual cost to £1,800 but adding £50,000 in business interruption coverage. The incident also highlighted a gap in their professional indemnity insurance. The client argued the artist had misrepresented the tattoo’s longevity, leading to a separate £8,000 claim for "emotional distress." The studio’s initial policy excluded such claims, requiring them to purchase an additional £400 add-on to cover future disputes. This case underscores how tattoo parlours insurance must be tailored to the studio’s specific risks—not just checked as a box on an application."We thought £600 was cheap until we saw the fine print. The excess alone could’ve bankrupted us. Now we pay more, but we sleep better knowing we’re covered for the real risks." — James R., Brighton studio owner
| Factor | Estimated Impact |
|---|---|
| Contaminated needle lawsuit | £120,000 in medical/legal costs (covered), £50,000 in lost revenue (not covered) |
| High excess clause | £10,000 out-of-pocket before insurance kicks in |
| Misrepresented tattoo claim | £8,000 settlement (required additional coverage) |
| Annual premium increase | £1,200 additional cost for specialized coverage |
What This Means Going Forward
The Brighton case is not an outlier. As tattooing grows in mainstream acceptance, so does the legal scrutiny surrounding studios. Insurers are responding by tightening underwriting criteria, particularly for artists with limited experience or studios in shared spaces. New regulations—such as mandatory ink batch testing in some European countries—may also drive up compliance-related costs. Studios that fail to adapt risk higher premiums or denied coverage, forcing them into the uninsured market where a single claim could be financially devastating. For artists, the message is clear: tattoo parlours insurance is not an optional expense but a strategic investment. The cheapest policy may seem appealing, but the true cost of being underinsured can dwarf the annual premium. Studios should audit their risks annually, reviewing coverage limits, excess amounts, and emerging threats like cyber exposure. Collaborating with a specialized insurance broker—one familiar with the tattoo industry—can uncover savings and protections that generic policies miss.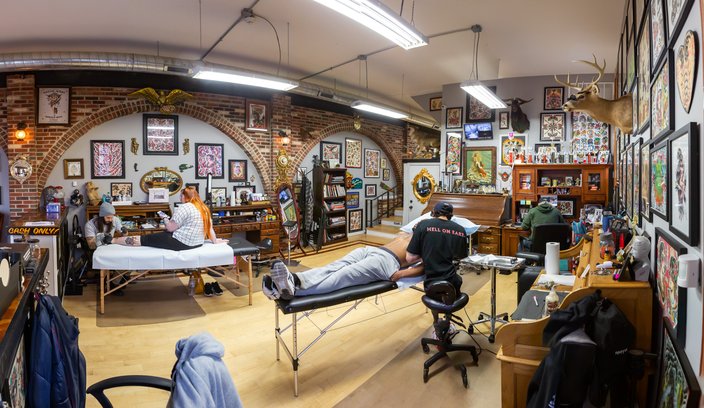
Conclusion
The tattoo industry’s rapid growth has outpaced its insurance infrastructure, leaving many studios exposed to avoidable risks. While tattoo parlours insurance remains a necessary evil, the key to managing costs lies in proactive risk assessment. Studios that treat insurance as a static line item—rather than a dynamic tool—will pay the price when claims arise. The Brighton example serves as a cautionary tale, but it also proves that smart coverage choices can turn a potential disaster into a manageable setback. The future of tattoo parlours insurance will likely see more niche products, such as coverage for custom ink formulations or social media-related disputes. As the industry professionalizes, insurers will follow, offering packages that reflect the unique liabilities of modern tattooing. For now, the onus is on studio owners to stay informed, ask tough questions, and never assume basic policies are enough.Comprehensive FAQs
Q: Is public liability insurance legally required for UK tattoo parlours?
A: Yes. While the UK government does not mandate specific insurance for tattooing, local council regulations and health and safety laws typically require at least £2 million in public liability coverage. Failure to comply can result in fines or forced closure. Always verify with your local authority, as rules vary by region.
Q: Can I get tattoo insurance if I work from home?
A: Some insurers offer home-based tattoo insurance, but coverage is often limited. Public liability policies may exclude home addresses, and equipment coverage might be restricted to professional-grade setups. If you operate from home, disclose this upfront—misrepresentation can void your policy. Expect to pay 10% to 20% more than a commercial studio for similar coverage.
Q: What’s the difference between professional indemnity and public liability insurance?
A: Public liability insurance covers third-party injuries or property damage (e.g., a client slipping on blood). Professional indemnity insurance protects against claims of negligence or errors in service (e.g., a botched tattoo or misrepresented design). Many tattoo studios need both—public liability as a legal minimum and professional indemnity to safeguard against artistic disputes. The latter can cost £200 to £600 annually, depending on your experience level.
Q: How do I lower my tattoo parlour insurance premiums?
A: Insurers consider several factors when setting rates. Reducing premiums often involves:
- Increasing excess amounts (e.g., raising from £2,500 to £5,000 can cut costs by 10–15%).
- Implementing strict health/safety protocols (e.g., autoclave sterilization records, staff training certifications).
- Bundling policies (e.g., combining public liability with professional indemnity through one provider).
- Choosing a higher excess for low-risk claims (e.g., allergic reactions vs. equipment theft).
Q: What should I do if my insurance claim is denied?
A: If your tattoo parlours insurance provider denies a claim, act immediately:
- Review the denial letter for specific reasons (e.g., "pre-existing condition," "excluded activity").
- Gather all documentation (contracts, incident reports, medical records, photos).
- Request a formal review—many insurers have an internal appeals process.
- Consult a specialist insurance lawyer if the denial seems unjust. Some brokers offer free claim reviews as part of their service.
- Consider switching providers if denial patterns suggest poor coverage for your industry.
