
The Complete Overview of the Biggest White-Collar Crimes
The term "biggest white-collar crimes" isn’t just about the largest dollar figures—though those are staggering. It’s about the structural damage inflicted on economies, the erosion of public trust in institutions, and the way these crimes redefine the boundaries of legality itself. Take the 2008 financial crisis, where toxic mortgage-backed securities became the financial equivalent of a house of cards. Banks like Lehman Brothers and Goldman Sachs engaged in practices that, while technically legal, were so predatory they triggered a global recession. The cost? Trillions in taxpayer bailouts, millions of jobs lost, and a decade of austerity measures that disproportionately punished the working class. The criminals? Many walked away with bonuses, while the architects of the crisis—like former Treasury Secretary Henry Paulson—were later praised for their "leadership." What makes these cases uniquely insidious is their normalization. Fraud schemes that would once have been prosecuted as racketeering are now dressed up as "innovative financial engineering" or "aggressive growth strategies." The 2016 collapse of Wirecard, a German fintech darling, revealed how easily a company could fabricate billions in revenue, secure listings on major exchanges, and evade scrutiny for years—until a whistleblower’s tip and a forensic audit exposed the fraud. By then, the damage was done: investors lost billions, employees faced unemployment, and the company’s auditors, KPMG, were left questioning their own due diligence. The pattern is clear: biggest white-collar crimes don’t just break the law; they exploit the law’s loopholes, often with the tacit approval of the very regulators meant to stop them.Historical Background and Evolution
The modern concept of white-collar crime emerged in the early 20th century, coined by sociologist Edwin Sutherland to describe crimes committed by "respectable" individuals in the course of their occupations. But it wasn’t until the 1970s, with the Watergate scandal and the rise of corporate lobbying, that the public began to grasp the scale of financial misconduct at the highest levels. The Savings and Loan crisis of the 1980s—where bankers like Charles Keating looted institutions with fraudulent loans—exposed how deregulation could turn greed into a blueprint for systemic collapse. Keating’s imprisonment in 1991 was a rare moment of accountability, but the damage had already been done: hundreds of billions in taxpayer funds were used to bail out his failed empire. The 1990s and 2000s saw an evolution in tactics. The rise of the internet and globalization allowed criminals to operate across borders with impunity. The Enron scandal of 2001 wasn’t just about accounting fraud—it was a masterclass in how to hide fraud behind a veil of corporate jargon. Enron’s executives used off-balance-sheet entities and "mark-to-market" accounting to inflate profits, while auditors like Arthur Andersen looked the other way. When the scheme collapsed, it took down one of America’s most iconic companies and led to the Sarbanes-Oxley Act—a law that, while well-intentioned, became another layer of bureaucracy that fraudsters would later learn to navigate. The lesson? Biggest white-collar crimes don’t just adapt; they co-opt the very reforms meant to stop them.Core Mechanisms: How It Works
At their core, the most devastating white-collar frauds rely on three pillars: obfuscation, leverage, and impunity. Obfuscation comes in many forms—complex financial instruments, shell companies in tax havens, or simply burying incriminating documents in legalese. The 2015 Panama Papers leak revealed how political and corporate elites used offshore entities to hide wealth, but the technique itself is decades old. Leveraging institutional trust is equally critical. When a CEO like Martin Shkreli—who famously hiked drug prices by 5,000%—faces prosecution, the public often reacts with outrage. But when a bank like JPMorgan Chase settles for $13 billion over fraudulent mortgage sales, the punishment feels abstract, detached from the human cost. Impunity is the final piece. Prosecutors often lack the resources to pursue cases that span multiple jurisdictions, and statutes of limitations can expire before evidence is fully uncovered. The 2020 conviction of Elizabeth Holmes, the Theranos founder, was rare because it involved a charismatic figure whose downfall was captured in real time by media scrutiny. Most fraudsters operate in the shadows. Consider the case of biggest white-collar crimes like the 2008 Madoff scheme: investigators initially dismissed it as a minor Ponzi operation before realizing it was one of the largest financial frauds in history. The delay in exposure wasn’t just a failure of oversight—it was a feature of the crime itself. Madoff’s victims included charities, universities, and individual retirees who never saw their money again. The system was designed to ensure that, by the time the truth came out, the trail would be cold.Key Benefits and Crucial Impact
The term "key benefits" might seem ironic when discussing crimes that destroy lives, but from the perspective of the perpetrators, the rewards are undeniable. For executives, the allure lies in short-term gains without proportional risk. A fraudulent loan scheme can yield millions in profits before collapsing, while the architect might already have stashed away personal wealth. The 2002 WorldCom scandal, where CFO Scott Sullivan inflated assets by $11 billion, allowed him to live a lifestyle far beyond his legitimate means—until the company filed for bankruptcy, wiping out shareholders and employees. The impact on society, however, is far more destructive. When confidence in financial markets erodes, businesses hesitate to invest, jobs disappear, and governments scramble to contain fallout. The 2008 crisis alone cost the U.S. economy an estimated $22 trillion in lost output, according to a 2018 study by the Levy Economics Institute. The psychological toll is equally severe. Victims of white-collar fraud often suffer from financial ruin, depression, and even suicide. The 2011 collapse of MF Global, where customers’ segregated funds were used to cover trading losses, left thousands of European investors stranded. Many lost their life savings overnight. As one affected trader told a congressional hearing, "You don’t just lose money—you lose your future." The ripple effects extend to entire industries. After the 2016 Wirecard fraud, German regulators faced a crisis of credibility, and the fintech sector lost billions in investor confidence. The message was clear: biggest white-collar crimes don’t just steal money—they steal trust, and trust is the foundation of any functioning economy."Fraud is like a virus. It mutates, it adapts, and it always finds a way to exploit the weakest link in the system. The problem isn’t just the criminals—it’s the system that lets them thrive." — Former SEC Chair Mary Jo White, 2017
Major Advantages
From the fraudster’s perspective, the biggest white-collar crimes offer distinct advantages: - Plausible deniability: Complex financial structures allow criminals to claim ignorance or miscommunication. The 2013 HSBC money-laundering scandal involved trillions in suspicious transactions, yet the bank argued it was merely following client instructions. - Delayed consequences: Many schemes take years to unravel, giving perpetrators time to enjoy their ill-gotten gains. The 1990s Bank of Credit and Commerce International (BCCI) fraud, which involved billions in embezzlement, wasn’t fully exposed until the bank collapsed in 1991—by which time many criminals had fled. - Regulatory capture: Fraudsters often infiltrate or influence the very agencies meant to regulate them. The 2008 financial crisis was partly enabled by the "revolving door" between Wall Street and Washington, where regulators who oversaw banks would later join them as executives. - Media manipulation: High-profile fraudsters like Bernie Madoff cultivated public personas as philanthropists or industry leaders, making their downfall all the more shocking. Madoff donated to charities and sat on boards, ensuring his crimes were viewed as an aberration rather than systemic. - Legal technicalities: Prosecutors often struggle to prove intent, especially when fraud is embedded in layers of corporate entities. The 2015 Volkswagen emissions scandal involved software designed to cheat tests, but proving criminal intent required years of litigation.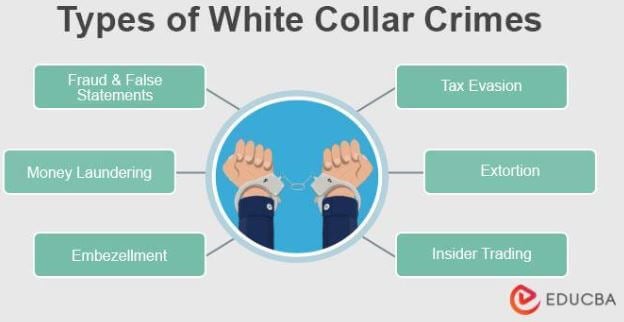
Comparative Analysis
| Crime | Impact and Key Features |
|---|---|
| Enron (2001) | Accounting fraud via off-balance-sheet entities; $65B in shareholder losses; led to Sarbanes-Oxley Act. Mechanism: Mark-to-market accounting, shell companies. |
| Madoff Ponzi (2008) | Ponzi scheme defrauding investors of $65B; victims included charities and pension funds. Mechanism: Fake trading statements, no actual investments. |
| Wirecard (2016) | Fraudulent revenue of €1.9B; collapse triggered by whistleblower and forensic audit. Mechanism: Fake bank accounts in Asia, forged documents. |
| 2008 Financial Crisis | Toxic mortgages and derivatives led to $22T in lost U.S. output; bailouts funded by taxpayers. Mechanism: Predatory lending, securitization, regulatory failure. |
Future Trends and Innovations
The next wave of biggest white-collar crimes will likely leverage two emerging trends: digital assets and AI-driven fraud. Cryptocurrency exchanges have already become magnets for money laundering, with schemes like the 2021 FTX collapse—where $8B vanished overnight—showing how easily decentralized finance can be exploited. The use of smart contracts and anonymous transactions makes it nearly impossible for regulators to trace illicit flows. Meanwhile, AI is being weaponized to generate fake documents, manipulate markets, and even impersonate executives in phishing scams. A 2023 report by the World Economic Forum warned that synthetic identity fraud—where criminals create entirely fake personas—could surpass traditional fraud in the next decade. The challenge for law enforcement lies in keeping pace. Blockchain forensics is still in its infancy, and many jurisdictions lack the expertise to prosecute crypto-related crimes. The European Union’s MiCA regulations are a step forward, but enforcement remains inconsistent. On the bright side, innovations like real-time transaction monitoring and machine learning for anomaly detection are giving regulators new tools. However, fraudsters are already adapting—using privacy coins like Monero or layering transactions across multiple exchanges to obscure trails. The arms race between criminals and investigators is intensifying, and the stakes couldn’t be higher. If history is any guide, the biggest white-collar crimes of the future will be the ones no one sees coming—until it’s too late.
Conclusion
The biggest white-collar crimes are more than financial crimes; they’re systemic failures that expose the fragility of trust in institutions. From Enron’s balance sheets to Madoff’s fake trades, these cases reveal how easily power can be weaponized against the public good. The irony is that many of these crimes wouldn’t have been possible without the very systems meant to prevent them—deregulation, complex financial instruments, and a culture that rewards short-term gains over long-term stability. The cost isn’t just monetary; it’s social, psychological, and economic. When a fraud like Wirecard collapses, it’s not just investors who lose—it’s the credibility of entire industries. The question of accountability remains unanswered. While a few high-profile cases—like the conviction of Elizabeth Holmes—make headlines, the vast majority of perpetrators face little more than fines or deferred prosecution agreements. The message is clear: biggest white-collar crimes are still too often treated as a cost of doing business rather than a criminal act. Without radical reforms in regulation, corporate culture, and enforcement, the cycle will continue. The next Enron, the next Madoff, is already being built—somewhere in the shadows, where complexity meets greed.Comprehensive FAQs
Q: What defines a "white-collar crime" compared to street crime?
A: White-collar crimes are non-violent, typically committed by professionals or corporations for financial gain. Unlike street crime, they often involve fraud, embezzlement, or regulatory violations rather than physical harm. The key difference is systemic exploitation—white-collar crimes thrive on trust and complexity, while street crimes rely on force or deception in the moment.
Q: Why do so many white-collar criminals avoid prison?
A: Factors include legal technicalities (proving intent is difficult), plea bargains (prosecutors often lack evidence for full trials), and regulatory capture (lawyers and lobbyists influence laws to favor the accused). Additionally, many cases involve statutes of limitations that expire before full investigations conclude.
Q: Can individuals protect themselves from white-collar fraud?
A: Yes, but it requires vigilance. For investors, diversifying assets and researching management teams can help. For employees, monitoring corporate transparency (e.g., unusual accounting practices) and reporting red flags can prevent internal fraud. However, biggest white-collar crimes often target institutions, making individual protection limited.
Q: What role do tax havens play in these crimes?
A: Tax havens enable anonymity and asset concealment. Shell companies in places like the Cayman Islands or Panama allow fraudsters to hide wealth, launder money, and evade prosecution. The Panama Papers (2016) and Pandora Papers (2021) exposed how political and corporate elites use these systems to operate beyond legal reach.
Q: Are there countries with stronger white-collar crime enforcement?
A: Yes, but enforcement varies widely. The U.S. SEC and UK’s Serious Fraud Office are among the most aggressive, with resources to pursue cross-border cases. However, jurisdictional challenges (e.g., extradition treaties) and corporate influence often limit outcomes. Switzerland and Singapore, despite strong financial sectors, have weaker prosecution records.
Q: How do cryptocurrencies change white-collar fraud?
A: Cryptocurrencies remove intermediaries, making transactions harder to trace. Ponzi schemes (e.g., OneCoin) and exit scams (e.g., FTX) exploit pseudo-anonymity and decentralization. Regulators are playing catch-up, but smart contracts and privacy coins (like Monero) continue to evade detection.
Q: What’s the biggest white-collar crime in history by financial loss?
A: The 2008 financial crisis—triggered by predatory lending and toxic derivatives—costs are estimated in the trillions, with global GDP losses reaching $22 trillion. Individually, Bernie Madoff’s Ponzi scheme ($65B) and Enron’s fraud ($65B) are among the largest single cases, but systemic crimes like the crisis dwarf them.
Q: Can whistleblowers really make a difference?
A: Absolutely. Cases like Wirecard (2016) and Theranos (2015) were exposed by insiders. Whistleblower protections (e.g., Dodd-Frank Act in the U.S.) encourage reporting, but retaliation remains a risk. Many frauds persist because internal dissent is silenced before it reaches authorities.
