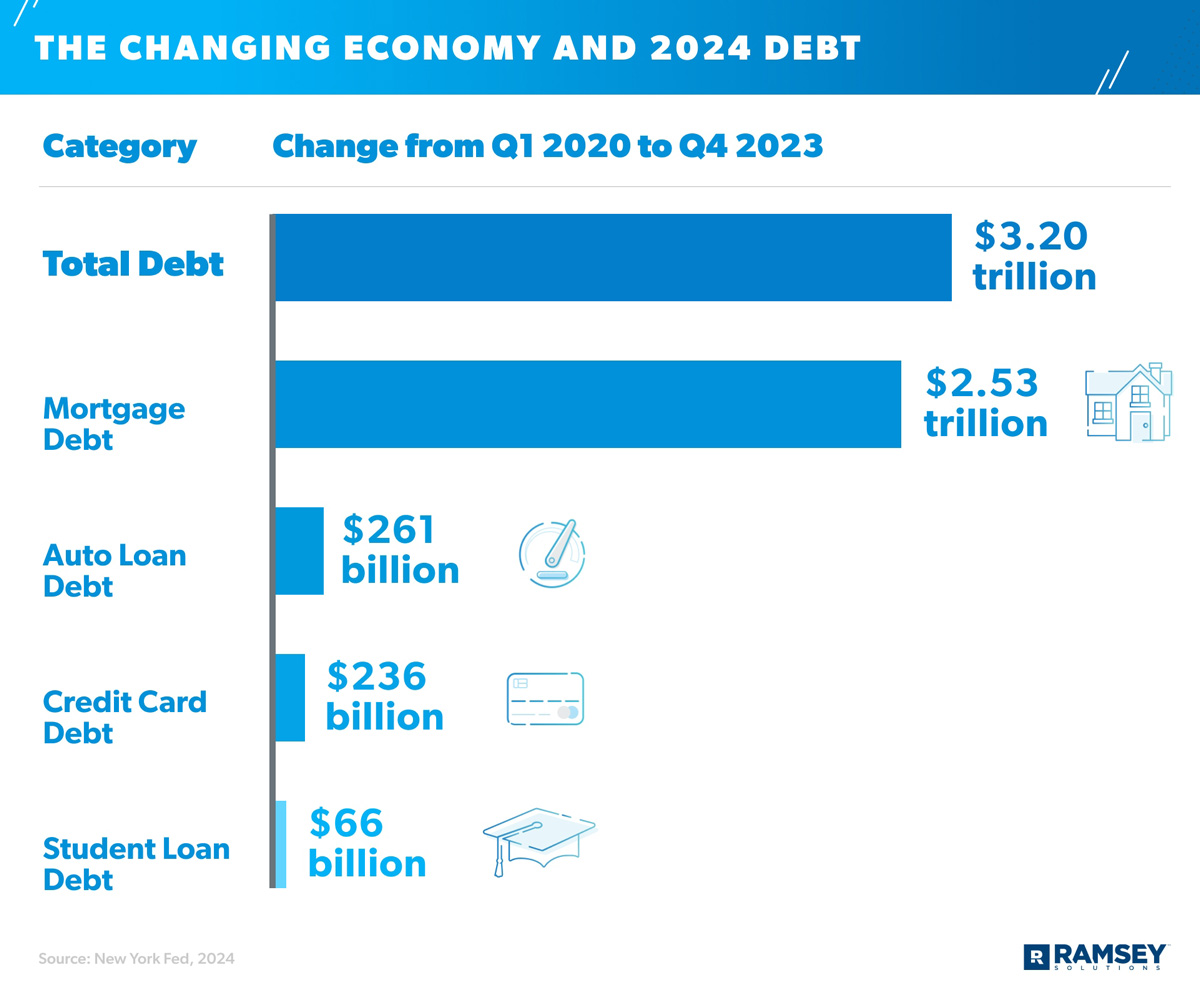
6 Things Worth Knowing About Average American Debt by Age
The patterns of average American debt by age follow predictable arcs, but the specifics vary wildly depending on economic conditions, policy changes, and personal circumstances. What’s clear is that debt isn’t distributed evenly—it’s concentrated in certain life stages, often with unintended consequences. Below are the most critical takeaways, backed by data and expert analysis.1. The Student Loan Crisis Begins Early
For Americans under 30, student debt is the dominant force shaping the average American debt by age. According to Federal Reserve data, borrowers in this group carry roughly $25,000 in student loans on average, though figures climb higher for graduate degrees. The burden isn’t just financial—it delays homeownership, marriage, and even parenthood. A 2023 study found that 40% of millennials with student debt reported putting off major life milestones due to loan payments. The problem isn’t just the size of the debt; it’s the intergenerational transfer of risk. Unlike past generations, who relied on family wealth or employer pensions, today’s young adults are entering adulthood with liabilities that previous cohorts didn’t face at the same scale. The long-term effects are still unfolding. While student loan forgiveness debates dominate headlines, the reality is more nuanced: default rates remain stubbornly high for low-income borrowers, and refinancing options are limited for those in public service or non-profit roles. The average American debt by age for this group isn’t just a personal failing—it’s a symptom of a system where higher education has become a prerequisite for middle-class stability, yet its cost outpaces wage growth.2. Credit Card Debt Peaks in the 30s
By the time Americans reach their early 30s, student loans start to taper off, but credit card debt takes center stage in the average American debt by age profile. This is the decade of major life expenses: weddings, home down payments, and sometimes unexpected medical bills. The Federal Reserve estimates that households in this age group carry around $6,000 in credit card debt, though balances can exceed $15,000 for those with lower credit scores. The danger lies in the compounding interest—unlike student loans, credit card debt isn’t fixed-term, meaning balances can grow indefinitely if not managed. What’s often overlooked is the psychological toll. Credit card debt in this life stage is frequently tied to lifestyle inflation—keeping up with peers, travel, or even emergency expenses. A 2022 survey by the American Psychological Association found that financial stress from credit card debt was a top contributor to anxiety among adults 25–34. The average American debt by age here isn’t just about numbers; it’s about the cultural pressure to "adult" on a timeline that often doesn’t align with financial reality.3. Mortgages Reshape the 40s and 50s
The average American debt by age in the 40s and 50s is dominated by mortgages, which become the largest liability for most households. According to the Urban Institute, homeowners in this age range carry an average mortgage balance of $200,000, though this varies sharply by region—urban areas like New York or San Francisco see balances exceeding $300,000. The shift from renting to owning introduces new financial risks: property taxes, maintenance costs, and the potential for negative equity in a downturn. For many, this decade is also when children’s education costs kick in, adding another layer of debt. The mortgage burden isn’t uniform. Older millennials entering their 40s often face sticker shock from home prices that have risen faster than their incomes. Meanwhile, Gen Xers in their 50s may still be paying off mortgages from the 2008 housing crash, when many refinanced at higher rates. The average American debt by age in these years reflects not just personal choices but also broader economic cycles—like the Fed’s interest rate hikes that made mortgages more expensive for first-time buyers in the 2010s.4. Medical Debt Strikes Later in Life
Contrary to the stereotype of medical debt affecting only the elderly, the average American debt by age reveals that hospital bills and uninsured care become a major issue starting in the late 40s and 50s. A Kaiser Family Foundation report found that 41% of Americans with medical debt are under 60, with an average balance of $2,000–$5,000. The culprits? Emergency room visits, prescription drugs, and procedures not fully covered by insurance. Unlike student loans or mortgages, medical debt is less predictable—a single accident or chronic condition can derail decades of savings. What makes this debt particularly insidious is its impact on credit scores. Medical debt is now treated like any other unsecured debt by credit bureaus, meaning delinquencies can follow borrowers for years. The average American debt by age here underscores a harsh reality: even with employer-sponsored health insurance, gaps in coverage can leave families vulnerable. For those nearing retirement, medical debt can force early withdrawals from 401(k)s or delay Social Security claims.5. Retirement Debt: The Silent Crisis
The average American debt by age for those 65 and older is often overlooked, but it’s a growing concern. While mortgages may be paid off, credit card debt, medical bills, and even outstanding loans persist into retirement. The Consumer Financial Protection Bureau estimates that 1 in 5 Americans over 65 carries some form of debt, with an average balance of $10,000–$15,000. The most alarming trend? Reverse mortgages and home equity loans, which can leave retirees house-rich but cash-poor. A 2023 study by the Center for Retirement Research found that 40% of retirees with debt have balances exceeding their annual income, making it impossible to dig out. The implications are severe. Retirees with debt are more likely to rely on Social Security, delay healthcare, or return to the workforce. The average American debt by age in this group isn’t just about spending habits—it’s about systemic failures in retirement planning, from inadequate Social Security benefits to the rising cost of long-term care. For many, debt doesn’t disappear with age; it evolves into a different kind of financial strain.6. The Gender Gap in Debt
When examining the average American debt by age, one critical variable is gender. Women consistently carry higher relative debt loads across all age groups, though the reasons vary by life stage. For example, women under 30 hold 20% more student debt on average than men, partly due to longer lifespans in college and higher enrollment in lower-paying fields like education and healthcare. By their 40s, women’s mortgage debt is 15% higher than men’s, reflecting both solo homeownership and the wage gap that makes it harder to qualify for larger loans. The gap widens in retirement: women over 65 are twice as likely as men to carry medical debt, largely due to longer life expectancies and lower savings rates. The average American debt by age for women isn’t just a statistical footnote—it’s a reflection of structural inequalities. From pay disparities to caregiving responsibilities, women’s financial trajectories are shaped by factors beyond their control. Yet, the data often gets overshadowed by aggregate numbers. As economist Diane Lim Rogers notes:"Debt isn’t neutral. It amplifies existing inequalities—whether by race, gender, or geography. The average American debt by age tells one story for a college-educated white man in Silicon Valley and another entirely for a single Black woman in Detroit. Ignoring those differences means missing the real drivers of financial distress."

How These Facts Connect
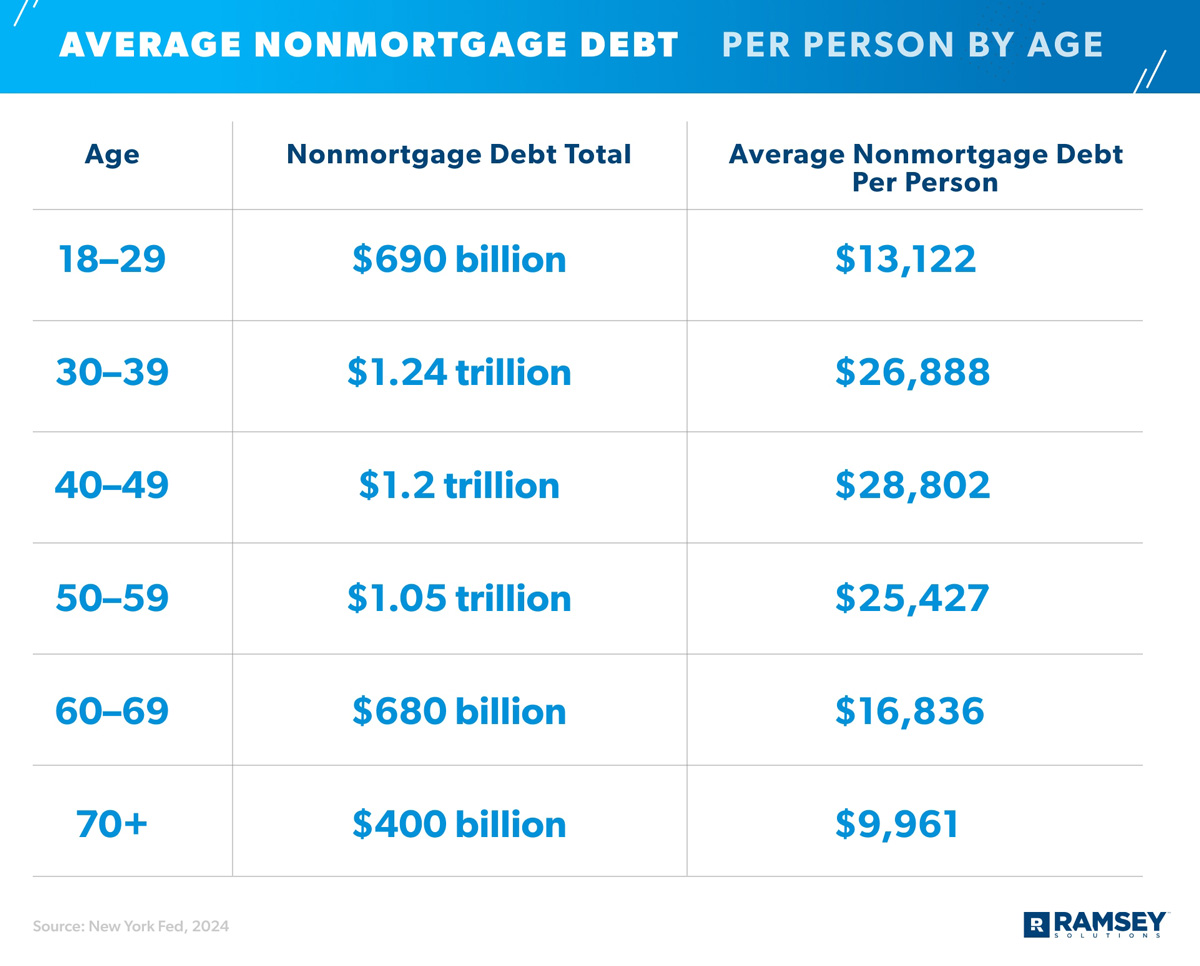
The average American debt by age isn’t a series of isolated snapshots—it’s a cumulative narrative of economic participation. From student loans that delay adulthood to mortgages that define middle age, each debt type serves as a marker of societal expectations. The data reveals a three-act structure: accumulation (student loans and credit cards), consolidation (mortgages and family expenses), and legacy (medical debt and retirement shortfalls). What’s striking is how little mobility exists between these stages. A missed payment in your 20s can haunt your credit score in your 50s. A high-interest credit card balance in your 30s might force you to take on a riskier mortgage later. The average American debt by age also exposes the myth of the American Dream’s accessibility. Homeownership, once the cornerstone of wealth-building, now requires decades of debt servitude for many. The table below compares the four most critical debt types across life stages, highlighting how obligations shift—and how they rarely disappear.| Life Stage | Dominant Debt Type | Average Balance | Key Risk Factor |
|---|---|---|---|
| Under 30 | Student Loans | $25,000–$40,000 | Delayed career milestones |
| 30–40 | Credit Cards & Auto Loans | $6,000–$15,000 | Lifestyle inflation |
| 40–55 | Mortgages | $200,000–$300,000 | Negative equity risk |
| 65+ | Medical & Credit Card Debt | $10,000–$20,000 | Retirement savings depletion |
Conclusion
The average American debt by age isn’t a static metric—it’s a living indicator of how financial systems reward or punish different generations. The data tells a story of delayed gratification: young adults defer homeownership, middle-aged families stretch their budgets to cover education, and retirees face the prospect of outliving their savings. Yet, for all its weight, debt isn’t an inevitable fate. Policy changes—like student loan reform, medical debt protections, or expanded retirement benefits—could reshape these trajectories. So too could cultural shifts, like prioritizing financial literacy over consumerism or redefining success beyond homeownership. The most important takeaway? Debt is a tool, not a sentence. Understanding the average American debt by age isn’t about resignation—it’s about recognizing patterns to break them. For individuals, it means planning for the next stage of debt, not just the current burden. For policymakers, it’s a call to address the structural inequities that make debt a generational curse. The numbers may be daunting, but they’re not destiny.Comprehensive FAQs
Q: How does the average American debt by age differ between urban and rural areas?
The average American debt by age varies significantly by geography. Urban areas, particularly coastal cities, see higher mortgage and student loan balances due to housing costs and higher education demand. Rural areas often have lower mortgage debt but higher credit card debt, as healthcare access and wage stagnation force reliance on unsecured credit. For example, a 30-year-old in San Francisco may carry $350,000 in mortgage debt, while a peer in rural Mississippi might owe $150,000 but face higher medical debt risks from lack of local healthcare.
Q: Can the average American debt by age be reduced without drastic lifestyle changes?
Yes, but it requires strategic refinancing and policy leverage. For student loans, income-driven repayment plans or public service forgiveness can lower monthly burdens. Credit card debt can be tackled with balance transfer offers or debt consolidation loans, though discipline is key. Mortgage refinancing during low-interest periods can save thousands. The most effective long-term strategy? Building emergency savings to avoid relying on high-interest debt. Policy changes—like capping medical debt collections or expanding credit counseling—could also ease the burden without requiring individuals to overhaul their lives.
Q: Does the average American debt by age vary significantly by race or ethnicity?
Absolutely. Black and Hispanic households consistently carry higher average American debt by age across all categories, with student loans and mortgages showing the largest disparities. For example, Black borrowers with bachelor’s degrees hold $7,400 more in student debt on average than white peers, partly due to historical redlining and lower family wealth. Mortgage gaps are even starker: Black homeowners are three times more likely to face foreclosure risk due to higher loan-to-value ratios. These differences aren’t accidental—they reflect centuries of economic exclusion compounded by modern financial systems.
Q: How does the average American debt by age affect mental health?
The link between debt and mental health is well-documented. A 2023 study in JAMA Psychiatry found that Americans with high debt loads—particularly credit card or medical debt—were 50% more likely to report symptoms of depression or anxiety. The stress isn’t just about the numbers; it’s about loss of control. For young adults, student loan anxiety correlates with lower life satisfaction. Middle-aged families with mortgage stress often experience marital strain. Retirees with lingering debt report higher rates of loneliness, as financial insecurity limits social and recreational spending. The average American debt by age isn’t just a financial metric—it’s a public health issue.
Q: Can parents legally protect their children from inheriting their debt?
Generally, yes—but with critical exceptions. Federal student loans, credit card debt, and most personal loans cannot be passed to heirs unless co-signed. However, mortgages and co-signed loans may transfer to estates, forcing heirs to settle balances. Medical debt is another risk: if a parent’s bills go to collections, credit reporting agencies may list the debt against the deceased, affecting surviving family members’ credit scores. The safest strategy? Estate planning—using trusts or payable-on-death accounts to shield assets. For student loans, federal discharge programs (like Total and Permanent Disability discharge) can relieve burdens before passing debts on.
Q: How does the average American debt by age compare to other developed nations?
The U.S. stands out for its high levels of household debt relative to income, particularly in student loans and medical bills. In Canada or Australia, student debt is lower due to government subsidies, while mortgage debt is more manageable thanks to stronger social housing programs. European nations fare better: Germany’s average household debt is less than 50% of disposable income, compared to over 100% in the U.S. The key difference? Universal healthcare and education systems reduce reliance on private debt. Even South Korea, often criticized for its work culture, has lower credit card debt due to cultural norms around frugality and stronger corporate welfare for education.
Q: What’s the most underreported factor in the average American debt by age?
The role of employer benefits—or lack thereof. Many Americans assume healthcare and retirement savings are personal choices, but the average American debt by age is heavily influenced by employer-sponsored plans. Workers at small businesses or gig economy jobs often lack 401(k) matches or health subsidies, forcing them to rely on high-interest debt. A 2022 Brookings Institution report found that employees without retirement benefits are 40% more likely to carry credit card debt in retirement. Similarly, COBRA healthcare gaps after job loss can lead to medical debt spirals. The most overlooked lever? Workplace financial wellness programs—companies that offer student loan repayment assistance or HSAs see lower employee debt stress and higher retention.
Q: Is there an age where the average American debt by age starts to decline?
For most Americans, debt peaks in the late 50s to early 60s, then begins a gradual decline—but rarely disappears entirely. Mortgages are often paid off by retirement, but credit card and medical debt can persist. The average American debt by age 70 is estimated at $10,000–$15,000, with 20% of retirees still carrying balances. The decline isn’t linear: some see debt drop sharply after selling a home, while others take on new loans (like reverse mortgages) to cover expenses. The critical factor? Retirement savings. Those with sufficient 401(k)s or pensions can pay down debt aggressively; those without often prioritize survival over debt repayment, leading to a second wave of financial stress in old age.
