Common Myths About How to Value a Pension in Net Worth
Pensions are frequently misrepresented in financial discussions, often reduced to simplistic rules of thumb that fail to account for their unique structures. The most persistent myth is that how to value a pension in net worth can be boiled down to a single formula—whether it’s "multiply your annual benefit by 20" for defined benefit schemes or "just add the current balance" for defined contribution plans. In truth, these shortcuts ignore critical variables like inflation, longevity risk, and tax efficiency. Another widespread error is assuming all pensions are liquid assets, when many come with strict withdrawal penalties or age-based access rules. Even professionals sometimes conflate pension valuations with other retirement accounts, overlooking how pension-specific regulations (such as the UK’s pension lifetime allowance or US required minimum distributions) alter their financial impact. The confusion extends to how pensions interact with other assets. Some advisors treat them as "locked-in" wealth that shouldn’t factor into net worth at all, while others inflate their value by projecting unrealistic growth scenarios. For example, a defined contribution pension growing at 7% annually might seem like a safe bet—but if the investor withdraws early or faces market downturns, that projection becomes a liability. Similarly, defined benefit pensions are often undervalued because their worth isn’t tied to a single market snapshot but to a series of future payments, which are sensitive to economic conditions and employer solvency.Myth 1: "A Defined Benefit Pension’s Value Is Just the Annual Payout × 20"
This rule of thumb—derived from early actuarial tables—assumes a static 5% discount rate and ignores modern longevity trends. In practice, a £30,000 annual pension might be worth £600,000 under this method, but if inflation erodes purchasing power or life expectancy extends, the true present value could be closer to £450,000. Actuarial firms now use dynamic models that factor in inflation expectations, mortality improvements, and even career longevity. For instance, a teacher retiring at 60 with a £25,000 annual pension might see their pension’s net worth value drop by 15% if they live to 90, due to the time-value of money and potential inflation adjustments. The error compounds when comparing pensions across borders. In the UK, the Pensions Regulator’s valuation guidelines now require pensions to be discounted at rates closer to 3–4%, reflecting lower long-term bond yields. Meanwhile, in the US, the IRS uses a uniform lifetime table that doesn’t account for regional cost-of-living differences. The result? A pension that appears generous in one country may be underwhelming in another when adjusted for local economic realities.Myth 2: "Defined Contribution Pensions Are Like Any Other Investment—Just Sum the Balance"
While it’s true that a defined contribution pension’s balance is a starting point, its net worth contribution depends on how and when it will be accessed. A £500,000 pot isn’t the same as £500,000 in an ISA because withdrawals are taxed as income (in the UK) or subject to required minimum distributions (in the US). Additionally, annuity rates—critical for converting the pot into income—fluctuate with bond yields. In 2023, a £100,000 annuity might buy £5,000 annually, but if rates drop to 3%, that same pot yields just £3,500. Ignoring these variables can lead to overconfidence in pension wealth, especially for those planning early retirement. Another pitfall is assuming the pension’s growth will mirror broader market returns. Many defined contribution schemes cap employer contributions or impose investment restrictions (e.g., limiting equity exposure). A pension growing at 5% annually might underperform a self-directed portfolio earning 7%. For high earners, this discrepancy can mean missing out on tax-efficient reinvestment opportunities or failing to hedge against inflation.Myth 3: "Public-Sector Pensions Are Risk-Free and Always Valuable"
Public-sector pensions—often seen as "guaranteed"—are vulnerable to political and economic shifts. The UK’s 2015 pension reforms, for example, reduced benefits for new public-sector workers, while US state pension funds have faced funding crises due to underestimation of liabilities. A £1,500 monthly civil service pension might sound secure, but if the scheme’s funding ratio drops below 80%, future benefits could be cut. Similarly, early retirement options (common in teaching or healthcare) may offer attractive lump sums, but these are often calculated using outdated life expectancy data. The valuation challenge is further complicated by survivor benefits. A pension that provides 50% to a spouse after death might seem valuable, but if the spouse is much younger, the present value of those payments could be overestimated. Actuaries now use "joint-life expectancy" tables to adjust for these scenarios, but many individuals rely on simplistic assumptions.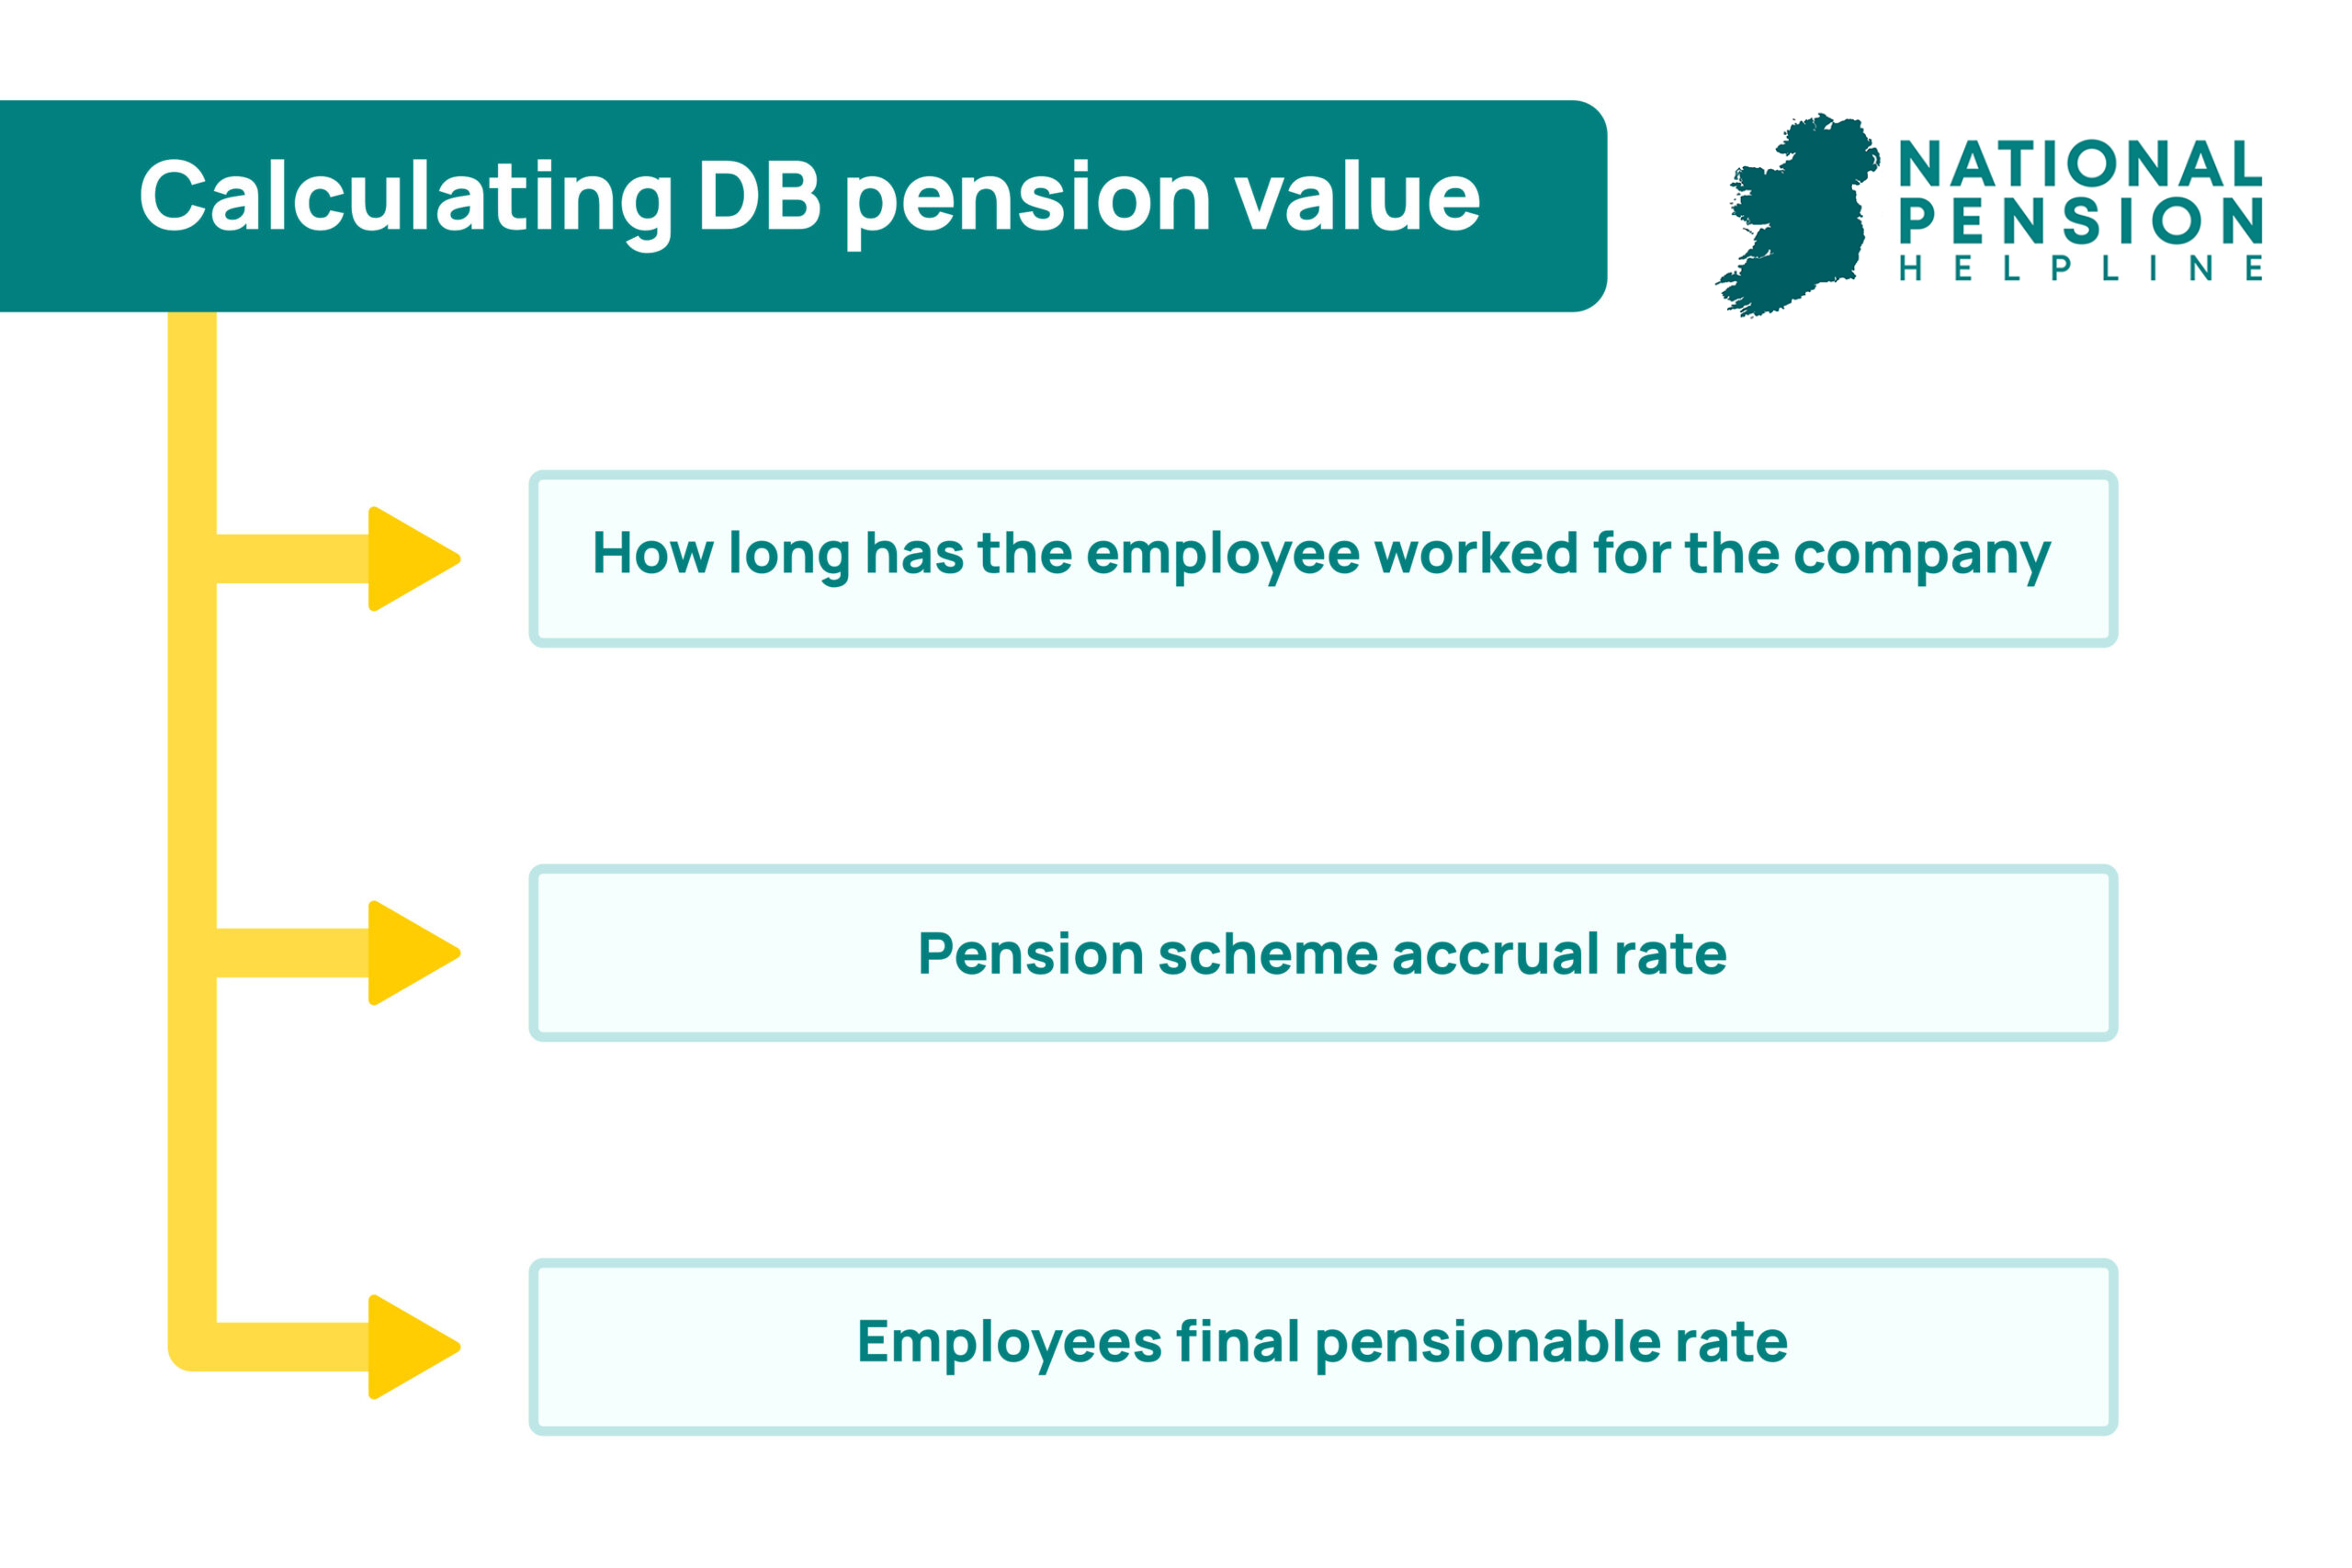
What Holds Up to Scrutiny
At the core of how to value a pension in net worth lies actuarial science—specifically, the interplay between discount rates, inflation, and longevity. Defined benefit pensions, for instance, are valued using present value calculations that account for the time between retirement and death, adjusted for expected inflation. The UK’s Pensions Regulator now recommends using a 3–4% discount rate for these calculations, reflecting lower long-term interest rates. For defined contribution pensions, the focus shifts to withdrawal strategies: annuitization, phased drawdown, or lump-sum access, each with distinct tax and liquidity implications. The most robust approach combines three pillars: 1. Actuarial valuation for defined benefit schemes, using up-to-date mortality tables and inflation assumptions. 2. Dynamic modeling for defined contribution pensions, simulating various withdrawal scenarios under different market conditions. 3. Tax-efficiency analysis, accounting for income tax, capital gains, and inheritance tax implications."Pensions are the only asset class where the valuation isn’t just about today’s balance—it’s about tomorrow’s income stream. A £1 million pension isn’t worth £1 million; it’s worth whatever it buys you in retirement, adjusted for risk." — Simon Evans, Head of Pensions at London Wealth Management| Common Belief | What the Evidence Says | |----------------------------------|---------------------------------------------------------------------------------------------| | "Multiply annual pension by 20." | Overstates value; modern actuarial tables use 25–30x for lower discount rates. | | "Defined contribution = current balance." | Understates tax drag and withdrawal constraints. | | "Public-sector pensions are safe." | Funding risks and reform exposure require stress-testing. | | "Annuities are the best option." | Not always—flexible drawdown may suit those with other income sources. | | "Pensions don’t count in net worth." | They do, but their valuation requires specialized methods distinct from other assets. |
Why the Confusion Persists
The lack of standardization is the primary culprit. Unlike stocks or property, pensions are governed by a patchwork of regulations that vary by country, employer, and plan type. In the UK, the Pensions Act 2023 introduced new valuation rules for defined benefit schemes, but many advisors still rely on outdated tools. Meanwhile, the US lacks a unified framework, leaving individuals to navigate IRS rules, state laws, and employer-specific policies. Even within a single country, public-sector and private-sector pensions are valued differently, creating inconsistency. Another barrier is the psychology of pensions. Because they’re deferred wealth, people struggle to assign them a tangible value. A £20,000 annual pension feels abstract until it’s compared to other income streams—yet most net worth calculators treat it as a static figure. Financial literacy programs often gloss over pension valuation, assuming it’s too complex for laypeople. The result? A generation of retirees making critical decisions based on oversimplified advice.
Conclusion
The accuracy of how to value a pension in net worth isn’t just a technicality—it’s a cornerstone of financial planning. Undervaluing a pension can lead to premature spending, while overvaluing it may lock individuals into suboptimal strategies. The key is to move beyond rules of thumb and adopt a multi-layered approach: actuarial precision for defined benefit schemes, dynamic modeling for defined contribution plans, and tax-aware adjustments for all. For high-net-worth individuals, this might involve consulting specialist actuaries or using software like PensionBee’s valuation tools or Vanguard’s retirement planning calculators. The good news? Tools and expertise are improving. Regulators are tightening valuation standards, and fintech platforms are demystifying pension assessments with interactive models. But the onus remains on individuals to ask the right questions—starting with whether their pension is being valued correctly in the first place.Comprehensive FAQs
Q: Should I include my entire pension pot in my net worth, or just its annual value?
A: Neither is fully accurate. For how to value a pension in net worth, the ideal approach is to calculate the present value of future payments (for defined benefit) or simulate withdrawal scenarios (for defined contribution). A simple balance or annual payout ignores inflation, taxes, and longevity risks. For example, a £30,000 annual pension might be worth £500,000 today, but its real value depends on how long you live and how much inflation erodes its purchasing power.
Q: How do I adjust for inflation when valuing a pension?
A: Actuaries use inflation-adjusted discount rates (typically 2–3%) to project future pension payments in today’s money. For instance, if your pension rises with inflation and you expect 2.5% annual increases, the present value calculation should reflect that. Tools like the UK Government Actuary’s Department (GAD) tables or Society of Actuaries’ mortality projections can help refine these estimates. Without adjustment, a pension’s net worth value can be overstated by 10–20% over a 20-year retirement.
Q: Does taking a pension lump sum reduce my net worth more than phased withdrawals?
A: Almost always, yes—but it depends on your tax bracket and investment strategy. A lump sum is taxed as income (up to 45% in the UK or ordinary income rates in the US), while phased withdrawals spread the tax burden. However, if you invest the lump sum poorly, its growth may not offset the tax hit. For how to value a pension in net worth, a lump sum should be discounted for taxes and potential underperformance compared to a well-managed drawdown plan.
Q: Can I treat my pension like a bank account for net worth purposes?
A: No. A bank account’s value is liquid and certain, but a pension’s value is contingent—it depends on future events like market returns, annuity rates, and your lifespan. For example, a £400,000 pension pot might be worth £300,000 after taxes and fees if withdrawn early. Even in drawdown, its value fluctuates with investment performance. The closest analogy is a restricted asset: it’s part of your wealth, but not fully liquid or guaranteed.
Q: How do I value a pension inherited from a spouse?
A: Inherited pensions (e.g., a spouse’s defined benefit or defined contribution pot) are valued based on survivor benefits and tax implications. For defined benefit, the present value of the survivor’s pension is calculated using joint-life expectancy tables. For defined contribution, the inherited pot is subject to inheritance tax rules (e.g., UK’s 45% rate on deaths before age 75) and may require accelerated withdrawals. The net worth impact is lower than the gross balance due to these liabilities.
Q: What’s the biggest mistake people make when valuing their pension?
A: Assuming it’s worth its face value without accounting for taxes, inflation, or access restrictions. Many treat a £500,000 pension as £500,000 in net worth, but in reality, it’s a stream of future income subject to erosion. The second biggest error is ignoring pension freedom rules—e.g., the UK’s 25% tax-free lump sum or US RMDs—which can turn a pension into a tax liability if mismanaged. For precise how to value a pension in net worth, consult an actuary or use pension-specific valuation tools.
