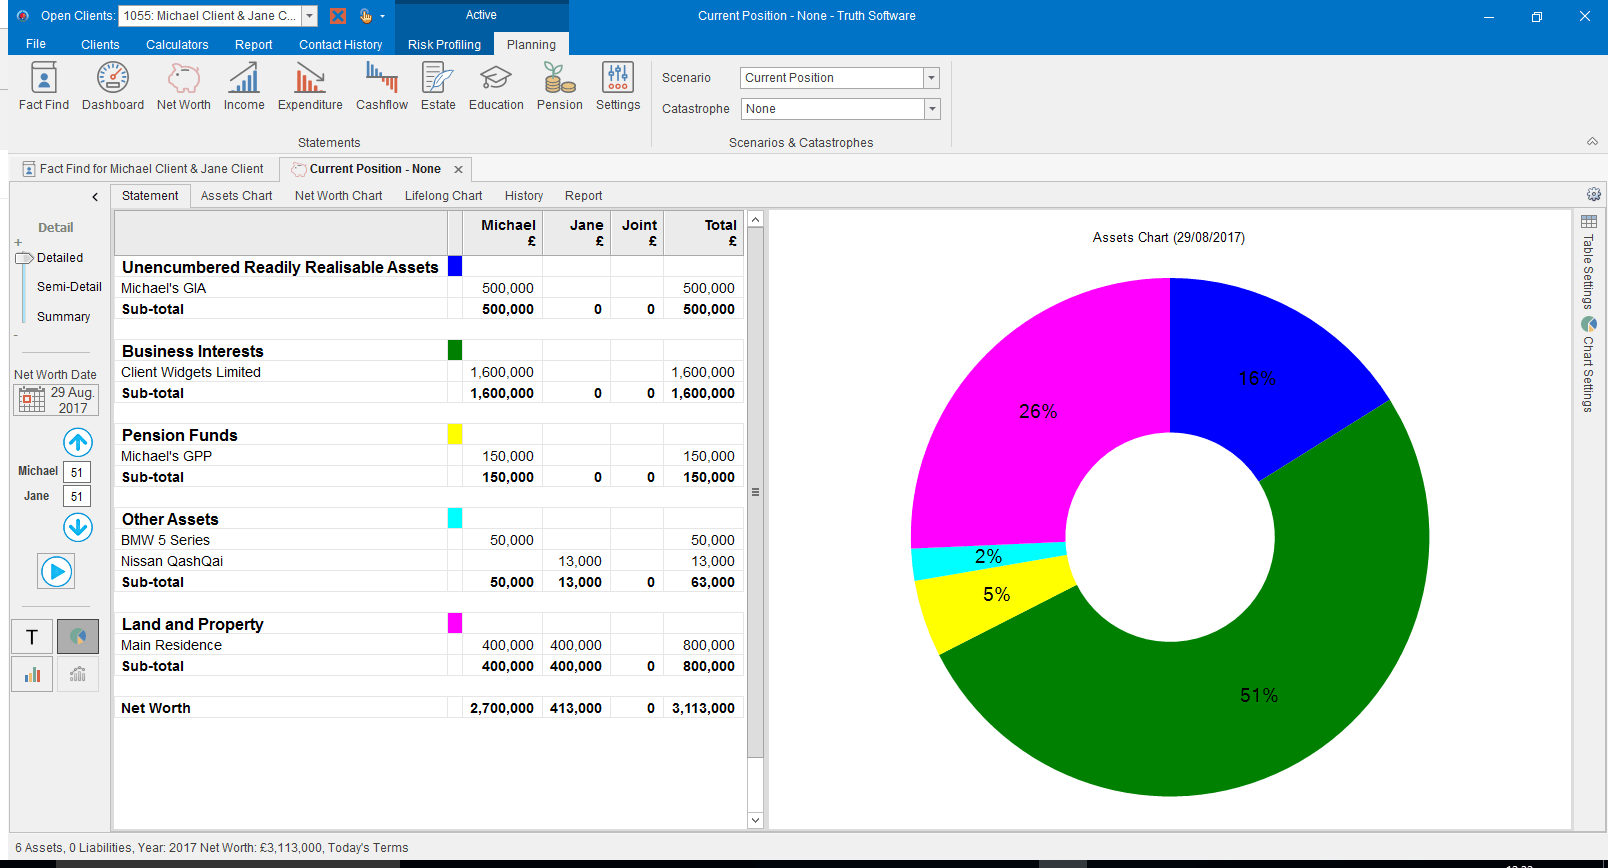
Breaking Down the Numbers
Net worth planning starts with the numbers, but the real work happens in the gaps between them. Publicly disclosed net worth figures—whether from Forbes lists or SEC filings—are rarely the full story. They omit illiquid assets like private equity stakes, intellectual property, or non-marketable real estate. They also ignore liabilities that aren’t on balance sheets, such as contingent legal risks or unfunded obligations. The most accurate net worth planners don’t rely on surface-level data; they build layered financial models that account for hidden exposures and non-linear risks. The challenge lies in reconciling transparency with privacy. High-net-worth individuals often face pressure to disclose assets for tax or regulatory purposes, but doing so can invite scrutiny from competitors, ex-spouses, or opportunistic creditors. Effective net worth planning requires a balance: enough disclosure to satisfy legal requirements, but enough opacity to protect against strategic leaks. This is where professional advisors earn their fees—not just in tax optimization, but in structuring holdings so that the most sensitive data remains shielded.The Verified Baseline
For publicly traded companies or individuals with SEC filings, the baseline is relatively clear. Take Warren Buffett’s Berkshire Hathaway: its annual reports provide a granular breakdown of cash, equivalents, and long-term investments, allowing for a verified net worth calculation (excluding Buffett’s personal holdings). The company’s Class A shares, trading around $600,000 per share, offer a liquid benchmark, but the true net worth of Berkshire’s conglomerate includes non-marketable assets like insurance float and private business stakes—figures that require deeper analysis. For private individuals, verified data is scarcer. The most reliable sources are court filings, property records, and verified business registrations. For instance, a real estate developer’s net worth might be estimated at $1.2 billion based on publicly traded REIT holdings, but their actual liquidity could be far lower if most assets are tied up in development projects. The key takeaway: verified net worth is a floor, not a ceiling. The real planning begins when you factor in what’s not on the balance sheet.What the Estimates Suggest
Industry estimates often inflate net worth figures by assuming full liquidity or unrealized gains. A tech founder’s net worth might be estimated at $500 million based on a recent funding round, but if that valuation is based on pre-money terms and the company hasn’t yet achieved profitability, the true usable wealth could be a fraction of that. Similarly, hedge fund managers’ reported net worths sometimes exclude carried interest that hasn’t yet vested or been realized. The estimates also ignore behavioral factors. A family with a $100 million trust might see that number shrink significantly if the trustee makes conservative, low-return allocations to preserve capital—while a more aggressive investor could see the same trust grow faster but with higher volatility. Net worth planning at this level isn’t just about numbers; it’s about aligning risk tolerance with generational goals. A parent might prioritize capital preservation for their children, while a single professional might accept higher risk for faster growth.
Case Study: A Closer Look
Consider the case of a mid-career physician who, after a decade of practice, finds their net worth sitting at $8 million—mostly in a mix of real estate, retirement accounts, and a small private practice. On paper, this appears secure, but a closer look reveals cracks. The practice generates steady income, but it’s undervalued in the current market, and the physician’s age means they’re approaching peak earning potential. Meanwhile, their real estate holdings are concentrated in a single city, exposing them to local economic downturns. The turning point came when they engaged a net worth planner who modeled three scenarios: 1. Status quo: Maintain current allocations, assume 3% annual growth, and retire at 60. 2. Aggressive diversification: Sell the practice, reinvest in low-volatility assets, and relocate to a lower-cost region. 3. Hybrid approach: Partially liquidate the practice, diversify internationally, and establish a holding company for tax efficiency. The physician chose the hybrid model, which required recalibrating their risk profile and accepting a temporary dip in liquidity. The key insight? Net worth planning isn’t about maximizing the number—it’s about maximizing flexibility."The biggest mistake is treating net worth like a scorecard. It’s not about the final tally; it’s about the moves you make along the way to ensure the number means something when it matters." — Financial planner to a high-net-worth client, 2023
| Factor | Estimated Impact |
|---|---|
| Practice liquidation timing | Delayed by 2 years due to market conditions; reduced net worth by ~$1.5M in opportunity cost. |
| International diversification | Added ~5% annualized growth but introduced currency risk; hedged via forward contracts. |
| Holding company structure | Reduced taxable income by ~30%; required legal fees of ~$250K upfront. |
| Psychological adjustment | Initial resistance to selling the practice led to a 6-month delay; cost ~$800K in lost equity appreciation. |
What This Means Going Forward
The future of net worth planning lies in adaptive frameworks—systems that can pivot in response to external shocks without requiring constant manual intervention. Machine learning is already being used to predict asset revaluations, but the most effective tools combine quantitative models with human judgment. For example, a planner might use AI to simulate 1,000 market scenarios, but the final decisions are made by humans who understand the client’s non-financial priorities—whether that’s legacy planning, philanthropy, or maintaining a certain lifestyle. Another shift is the rise of modular planning. Instead of treating net worth as a single monolith, the next generation of planners breaks it into components: liquidity, legacy, risk tolerance, and lifestyle sustainability. This modular approach allows for granular adjustments. A client might prioritize liquidity in one phase of life (e.g., funding a child’s education) while accepting illiquidity in others (e.g., holding private equity for long-term growth).
Conclusion
Net worth planning is not a destination but a continuous process of refinement. The planners who succeed are those who treat their portfolios like living organisms—pruned, nurtured, and adaptable. The numbers are the foundation, but the real art lies in the strategic decisions that turn those numbers into resilience. The most valuable lesson? Net worth planning isn’t about the size of the number—it’s about the control you have over it. Whether you’re managing a multi-billion-dollar portfolio or a six-figure nest egg, the principles remain the same: clarity, adaptability, and an unrelenting focus on the variables you can influence.Comprehensive FAQs
Q: How often should I revisit my net worth plan?
A: At a minimum, conduct a full review annually, but adjust for major life events—divorce, inheritance, career changes—or market disruptions. Quarterly check-ins for high-net-worth individuals are common, but even then, the depth of analysis should scale with volatility.
Q: Can net worth planning help during a market downturn?
A: Absolutely, but only if the plan was stress-tested beforehand. The key is having predefined triggers for rebalancing, liquidity buffers, and asset classes that historically perform well in downturns (e.g., gold, cash, or defensive stocks). Reacting emotionally is the fastest way to lock in losses.
Q: Is it ever too late to start net worth planning?
A: No, but the later you start, the more aggressive your approach must be. Someone in their 50s with modest savings can still build significant wealth through tax-efficient structures, asset protection, and disciplined spending. The goal shifts from accumulation to preservation and optimization—but that’s still planning.
Q: What’s the biggest mistake people make in net worth planning?
A: Overestimating their own discipline. Even the best-laid plans fail when emotions override strategy—whether it’s chasing "hot" assets, holding losing positions too long, or failing to adjust for inflation. The solution? Automate as much as possible and build in safeguards (e.g., stop-loss orders, spending freezes during volatility).
Q: How do I account for non-financial assets in net worth planning?
A: Start by assigning a conservative liquidation value to illiquid assets (e.g., a family business might be worth 50% of its appraisal in a forced sale). Then, factor in opportunity cost—what you could earn by selling vs. holding. For intangibles like intellectual property, work with valuation experts to estimate fair market value under different scenarios.
Q: Should I involve my family in net worth planning?
A: Yes, but strategically. Transparency builds trust, but too much detail can create unnecessary stress or conflicts. A phased approach works best: start with high-level goals (e.g., "We’re targeting $X by retirement"), then gradually introduce specifics as the family aligns on priorities. For blended families or complex estates, a neutral third-party facilitator (like a financial mediator) can help navigate sensitive discussions.
