
7 Things Worth Knowing About the hhousehold net worth median
The hhousehold net worth median is a deceptively simple concept with profound implications. It’s the financial midpoint of a nation’s households, where half sit above and half below. But beneath its simplicity lies a web of influences—from inheritance patterns to housing markets—that shape its trajectory. Here’s what the data reveals, and why it matters.1. The hhousehold net worth median is far more volatile than most realize
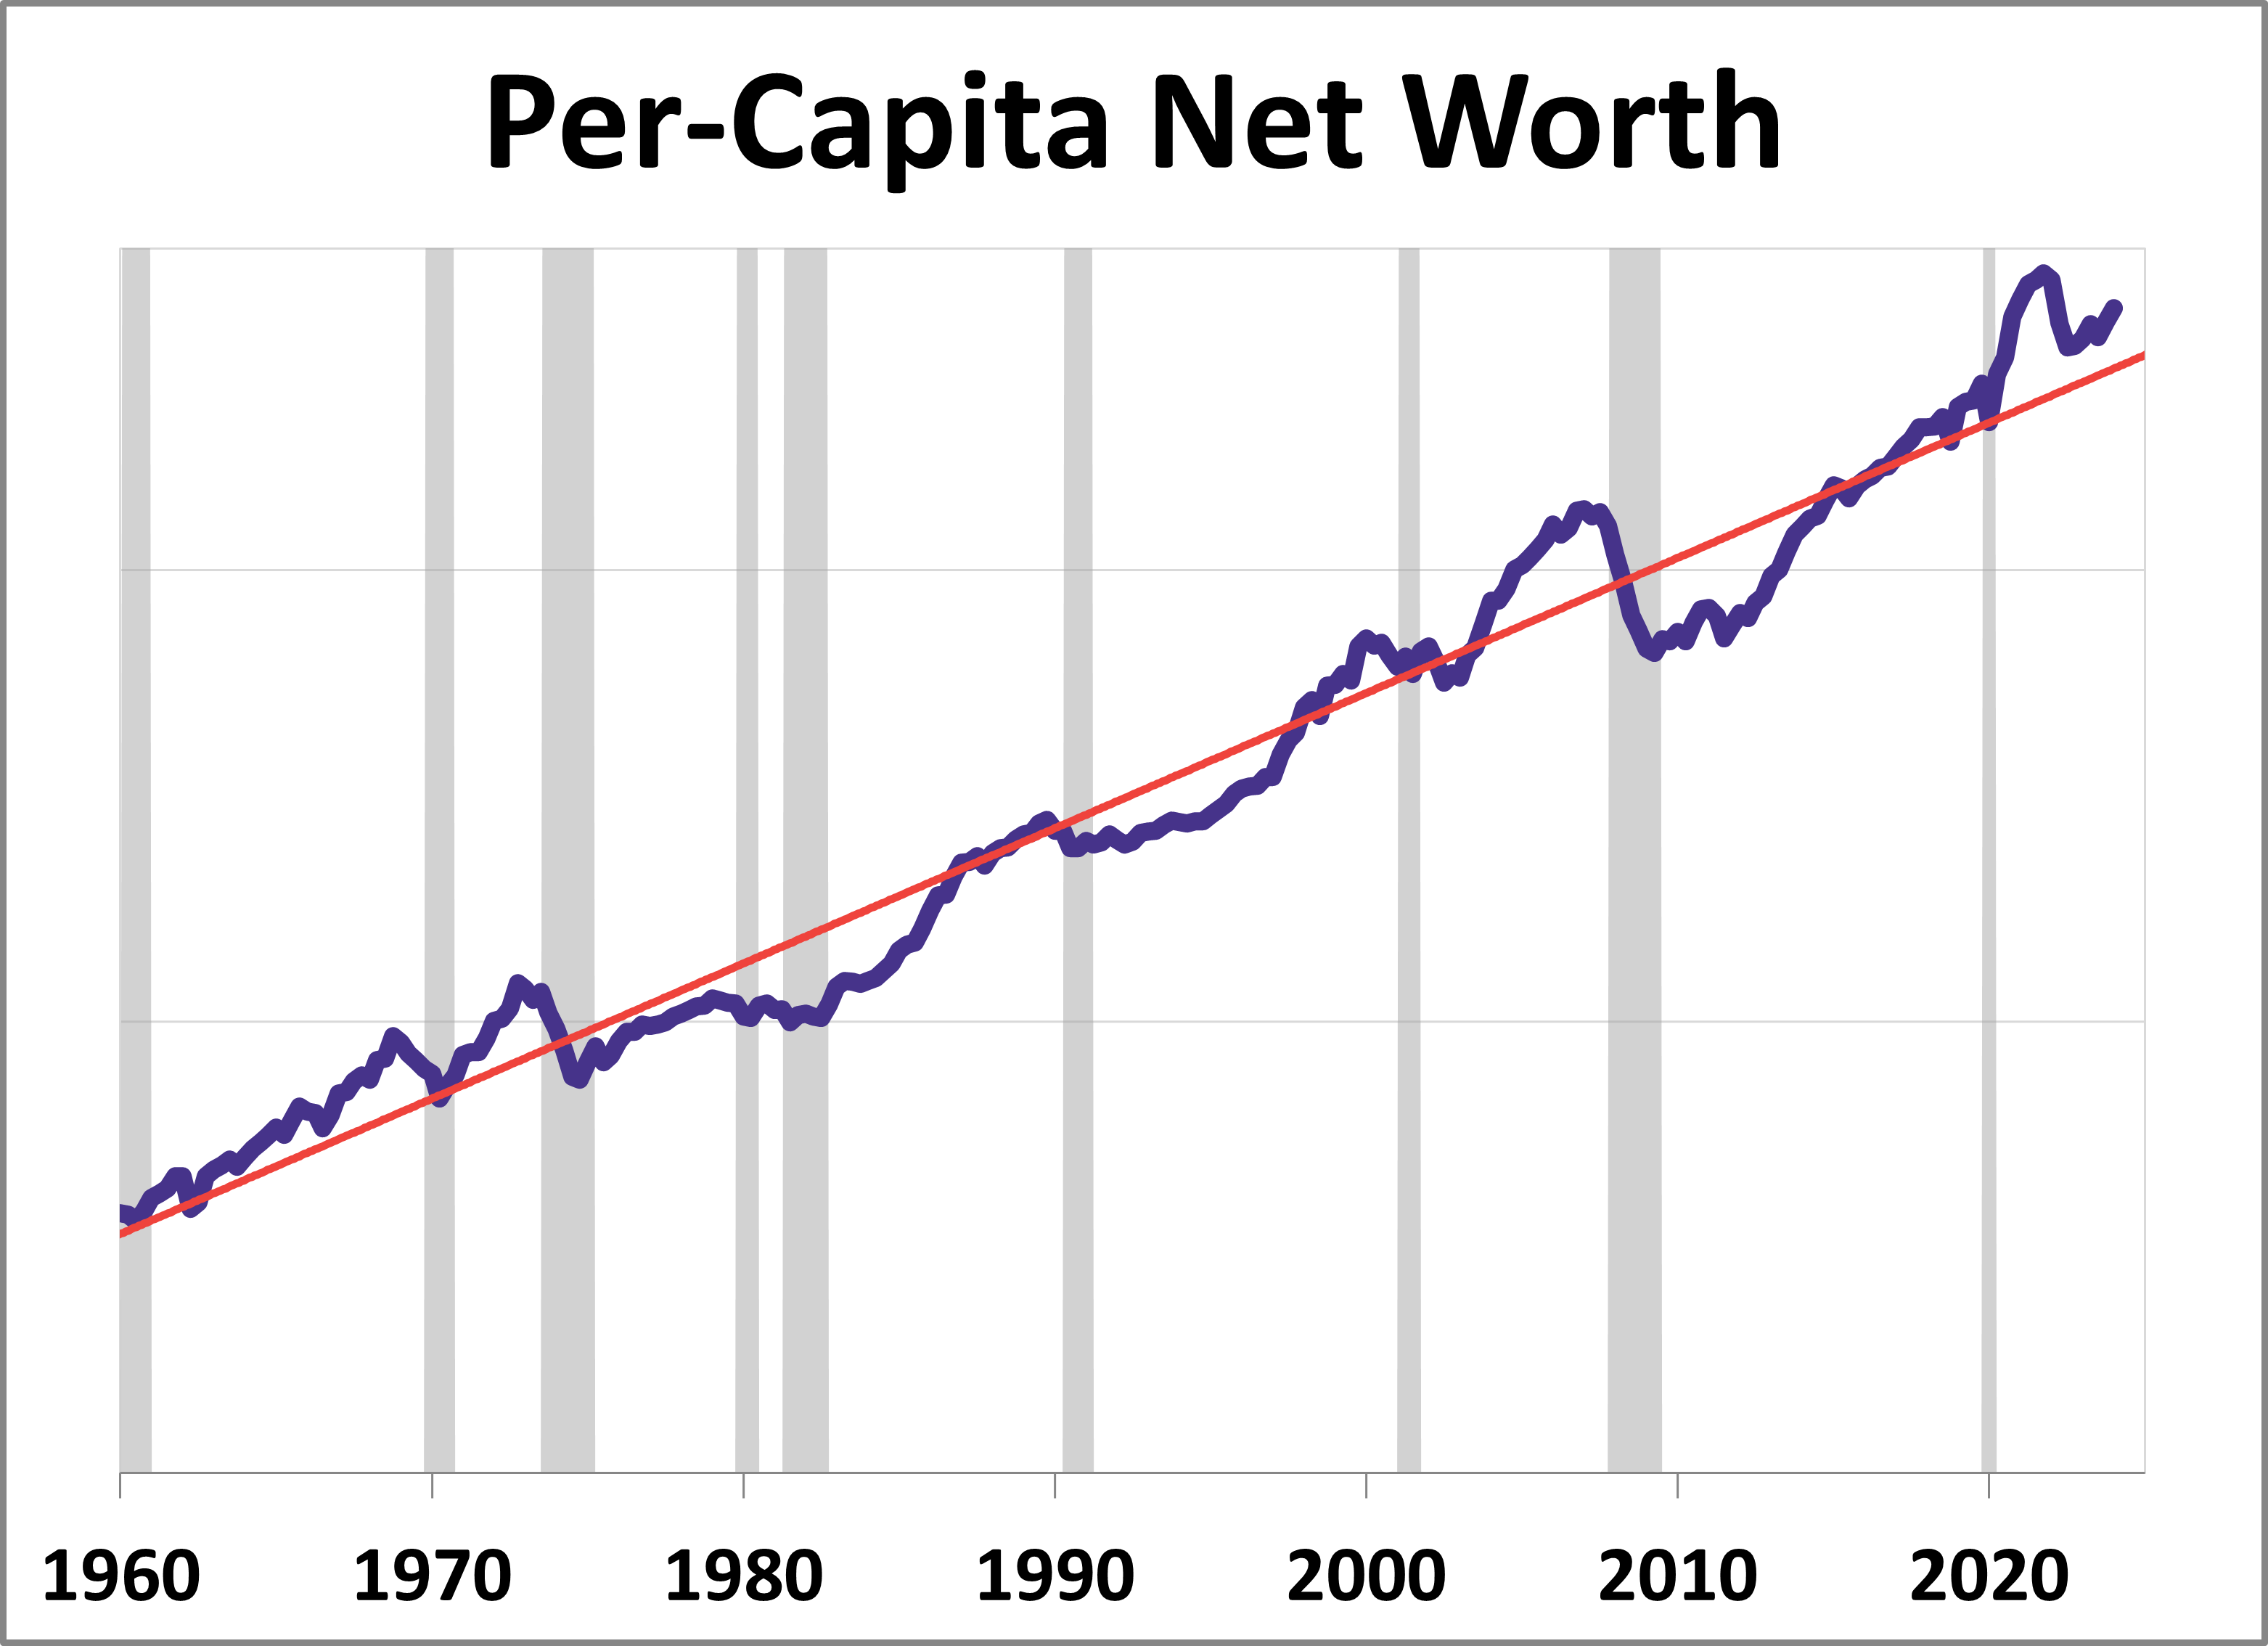
Economic downturns don’t just dent household wealth—they can obliterate it. The 2008 financial crisis wiped out roughly one-third of median net worth for American households, according to Federal Reserve data. Recovery took over a decade. The pandemic’s initial shock in 2020 saw median net worth drop by $35,000 in a single quarter, though it rebounded sharply thanks to asset price surges and stimulus checks. The volatility isn’t just about recessions; it’s about how quickly households can rebuild after setbacks. For renters or those with high debt loads, the median can feel like a moving target, never quite stable enough to plan around. What’s less discussed is how these swings vary by age. Younger households, still accumulating assets, see their median net worth rise more slowly. Older households, with decades of home equity and investments, recover faster. The median becomes a lagging indicator—it tells us where we’ve been, not always where we’re headed.2. Geography dictates the hhousehold net worth median more than income does
A household in San Francisco will have a vastly different median net worth than one in Detroit, even if their incomes are similar. Housing costs alone can swallow up decades of savings. In high-cost coastal cities, the median net worth is often inflated by home equity—meaning the typical household might own a $1.2 million property but have little liquid wealth. In Rust Belt cities, where home values stagnate, the median reflects lower asset accumulation despite comparable incomes. This geographic divide explains why national median figures can feel abstract: they mask deep regional disparities. The Fed’s Survey of Consumer Finances shows that the top 10% of households by net worth hold 70% of all liquid assets, but the median tells a different story. It’s not about the ultra-rich; it’s about the typical household’s ability to weather a job loss, medical emergency, or market downturn. In states with strong social safety nets—like Denmark or Sweden—the median net worth is less volatile because public policies act as buffers. In the U.S., where such protections are weaker, the median becomes a stress test for economic resilience.3. Student debt has reshaped the hhousehold net worth median for an entire generation
Before the 1980s, student loan debt was rare. Today, it’s the second-largest household liability after mortgages. For Gen Z and Millennials, student loans don’t just reduce disposable income—they drag down net worth. A household with $50,000 in student debt entering their 30s will have a median net worth 20% lower than a similar household without that debt, according to Brookings Institution research. The median net worth for households headed by someone under 35 has grown far slower than for older cohorts, partly because of this burden. The effect isn’t just immediate. Student debt delays homebuying, retirement savings, and even family formation. When the median net worth stagnates for younger households, it’s not just a financial issue—it’s a generational one. Policymakers often focus on average debt levels, but the median net worth tells a clearer story: this is how much wealth the typical young adult can realistically expect to accumulate by age 40.4. Homeownership remains the single biggest driver of the hhousehold net worth median
Owning a home isn’t just about shelter—it’s the primary way most households build wealth. The median net worth of homeowners is 40 times that of renters, according to the Fed. That gap explains why housing policy matters so much. When home prices surge, as they did post-pandemic, the median net worth ticks up not because incomes rose, but because home equity did. Conversely, when housing markets stall—like in the early 2010s—the median net worth stagnates even as wages grow. The catch? Homeownership isn’t equally accessible. Discriminatory lending practices, rising down payment requirements, and urban gentrification have locked out entire groups. The median net worth for Black households is just 15% of that for white households, largely due to historical barriers in homeownership. When the median rises, it often reflects who can access housing wealth—not who deserves it.5. The hhousehold net worth median is a lagging indicator of economic inequality
Inequality metrics like the Gini coefficient or CEO-to-worker pay ratios get more attention, but the median net worth is a blunt measure of whether the middle class is shrinking or growing. When the median rises, it suggests the typical household is faring better—but it doesn’t say whether the gains are shared. In the 1990s, the median net worth grew steadily, even as inequality widened. Today, the median has recovered from 2008 levels, but the top 1% now holds more wealth than the entire bottom 90% combined. The median’s lagging nature is its weakness. By the time it reflects a downturn, households are already struggling. But its strength lies in its simplicity: it’s the one number that cuts through the noise of averages and outliers to show what’s normal in a given year. That’s why central banks and policymakers watch it closely—it’s the canary in the coal mine of economic health.6. Retirement savings are increasingly tied to the hhousehold net worth median
For decades, defined-benefit pensions were the backbone of retirement security. Today, 90% of workers rely on 401(k)s and IRAs—accounts whose value swings with the stock market. When the median net worth rises, it’s often because retirement accounts have appreciated. But when markets dip, as they did in 2022, the median takes a hit. A household nearing retirement with a median net worth of $200,000 could see that drop by 15% in a bad year, erasing a decade of savings. The problem? The median net worth for near-retirees hasn’t kept pace with rising healthcare costs or longer lifespans. Social Security alone isn’t enough to maintain living standards. This is why the median isn’t just about current wealth—it’s a predictor of future financial security. If today’s median is stagnant, tomorrow’s retirees may face harder choices."The median net worth isn’t just a snapshot—it’s a report card on whether society is setting up the next generation to do better than the last. And right now, the grades are mixed." — Edward N. Wolff, Professor of Economics at NYU
7. Government policy can move the hhousehold net worth median—but it’s a slow process
From the New Deal to the GI Bill, policies that expanded homeownership and education boosted median net worth. Today, proposals like student debt relief, wealth taxes, or expanded child tax credits are debated precisely because they could shift the median. The American Rescue Plan’s stimulus checks temporarily lifted the median net worth by $28,000 in 2021, showing how direct transfers can work. But structural changes—like reforming zoning laws to lower housing costs—take years to affect the median. The challenge is political. Policies that help the median often require trade-offs—like higher taxes on the wealthy or subsidies for first-time buyers. The median net worth doesn’t move dramatically from year to year, which is why its shifts are usually the result of decades-long trends, not quick fixes. But when it does move, it signals whether the economy is working for the majority—or just the few.How These Facts Connect
The hhousehold net worth median isn’t just a number—it’s a story told through seven key dynamics: volatility, geography, student debt, homeownership, inequality, retirement risks, and policy. Together, they reveal that wealth accumulation isn’t random; it’s shaped by systemic forces. The median doesn’t lie, but it doesn’t tell the whole truth either. It hides the struggles of renters, the windfalls of homeowners, and the generational divide between those who inherited wealth and those who had to build it from scratch. What the median does show is the fragility of middle-class wealth. A single crisis—whether a job loss, a medical bill, or a market crash—can push a household below the median. That’s why tracking its movements is critical. When the median rises, it suggests the economy is lifting boats. When it falls, it’s a warning that the foundation of financial security is cracking.| Factor | Impact on Median Net Worth | Policy Leverage |
|---|---|---|
| Homeownership | +40x higher for owners vs. renters | Housing subsidies, zoning reform |
| Student Debt | -20% median for debt-holders under 35 | Debt relief, income-based repayment |
| Geographic Disparity | SF median vs. Detroit median: 3x difference | Regional economic incentives |
Conclusion
The hhousehold net worth median is a measure of economic health, but it’s also a measure of opportunity. It tells us whether the typical household can save for retirement, send a child to college, or weather an emergency. When the median stagnates, it’s not just a financial issue—it’s a sign that the social contract is unraveling. The data doesn’t lie, but interpreting it requires context: knowing that a rising median might hide growing inequality, or that a falling median could signal deeper structural problems. For individuals, the median is a benchmark—not a goal, but a reality check. If your net worth is below the median, it doesn’t mean you’re failing; it means you’re in the majority. The real question is whether the system is rigged against you—or whether you can navigate it. For policymakers, the median is a tool, not a target. It should guide decisions on taxes, education, and housing, but only if leaders recognize that wealth isn’t just about dollars—it’s about dignity, security, and the chance to build a better future.Comprehensive FAQs
Q: How often is the hhousehold net worth median updated?
The Federal Reserve’s Survey of Consumer Finances—the gold standard for U.S. median net worth data—is released every three years, with the most recent update in 2022. Quarterly estimates from the Fed’s Flow of Funds report provide rough trends, but the three-year survey is the most comprehensive. Other countries (like the UK’s ONS) release median wealth data annually, but methodologies vary widely.
Q: Why does the median matter more than the average net worth?
The average (mean) net worth is skewed by billionaires and top earners. For example, if one household has $10 million and the other nine have $50,000, the average is $1 million—but the median is $50,000. The median shows what’s typical, not exceptional. It’s the number economists and policymakers rely on to assess whether the economy is working for ordinary families.
Q: Can the hhousehold net worth median ever be "good enough"?
There’s no universal "good enough" threshold, but benchmarks exist. The St. Louis Fed suggests a median net worth of $120,000 for a middle-class household (adjusted for inflation) is a rough target for financial stability. However, this varies by region, age, and debt levels. The key is whether the median is growing faster than inflation—if not, households are treading water.
Q: How does inflation affect the hhousehold net worth median?
Inflation erodes purchasing power, but its impact on the median depends on asset types. Cash and bonds lose value, but homes and stocks often appreciate over time. In 2022, inflation hit 9.1%, but the median net worth still rose because housing and equities outperformed. However, for households with little liquid wealth, inflation can feel like a wealth tax—reducing savings and delaying retirement.
Q: Are there countries where the hhousehold net worth median is higher than the U.S.?
Yes, but context matters. Switzerland and Norway have higher median net worths per capita due to strong currencies and asset ownership. However, these figures often include pension funds and real estate, which aren’t liquid. The U.S. median is higher than in Japan or Italy, but lower than in Canada or Australia when adjusted for cost of living. The gap reflects differences in housing markets, tax policies, and wealth distribution.
Q: Can the hhousehold net worth median ever decline for an entire generation?
Historically, yes. Gen X’s median net worth grew slower than Boomers’ due to stagnant wages and the 2008 crash. Millennials face similar risks: student debt, housing costs, and slower wage growth. If current trends continue—with high interest rates and inflation—Gen Z could see its median net worth stagnate or decline relative to past generations, marking the first time in modern history that wealth accumulation reverses.
Q: How does the hhousehold net worth median compare for single vs. married households?
Married households have a median net worth 2-3x higher than single-person households, largely due to dual incomes and combined assets. However, this gap is shrinking as cohabitation and single-parent households grow. The Fed’s data shows that single women have the lowest median net worth, while married couples (especially with children) have the highest. Divorce and remarriage further complicate these trends.
Q: What’s the biggest misconception about the hhousehold net worth median?
The biggest myth is that it reflects individual effort alone. In reality, the median is shaped by inheritance, housing markets, and policy. A child born into wealth will always have a higher median net worth than one born into poverty—no matter how hard they work. The median isn’t a measure of merit; it’s a measure of systemic advantage. Understanding this is key to debating how to make the median rise for everyone, not just the lucky few.
