Common Myths About the Top 2 Percent Net Worth
The top 2 percent net worth is often reduced to a binary wealth check—either you’re in or you’re not. This oversimplification ignores the fluidity of thresholds and the contextual factors that determine entry. For instance, a couple in their 40s with a combined net worth of $1.8 million might qualify in the U.S., but in Switzerland, the same figure would place them in the top 10 percent. The confusion deepens when people conflate gross income with net worth. A CEO earning $50 million annually could still have a net worth below the threshold if most of that income is deferred or tied to illiquid assets. The reality is that the top 2 percent net worth is less about raw earnings and more about asset concentration, timing, and structural advantages. Another persistent myth is that luck or inheritance is the primary driver. While dynastic wealth plays a role—particularly in Europe and Asia—studies from institutions like Credit Suisse show that self-made fortunes dominate in the U.S. and emerging markets. The difference lies in compounding strategies: a hedge fund manager reinvesting carried interest over decades vs. a family trust preserving capital through generations. Even then, the top 2 percent net worth isn’t just about money—it’s about control. Access to private equity, real estate syndications, or family offices allows this cohort to de-risk their portfolios in ways unavailable to the broader market.Myth 1: It’s All About High Salaries
The assumption that the top 2 percent net worth is synonymous with executive compensation ignores the asset-side equation. A surgeon or lawyer with a $300,000 salary could still amass a net worth exceeding $2 million through frugality, real estate, and early retirement strategies. Conversely, a Silicon Valley executive with a $10 million stock grant might see that wealth erode if the company underperforms. Net worth isn’t just about what you earn—it’s about what you own, what you owe, and how you deploy capital. The data underscores this disconnect. A 2022 study by the Urban Institute found that only 30% of ultra-high-net-worth individuals in the U.S. derive their wealth primarily from employment income. The rest come from business ownership, investments, or inherited assets. Even within the top 2 percent net worth bracket, subcategories emerge: passive investors (those relying on dividends and capital gains), active entrepreneurs (who reinvest profits), and legacy holders (who manage inherited portfolios). The myth of the "high-earner" obscures the diversity of pathways to this financial tier.Myth 2: You Need to Be a Genius to Get There
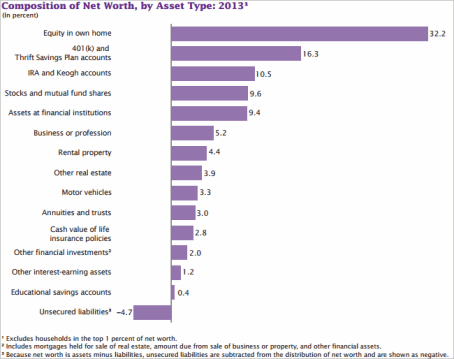
Financial acumen matters, but systemic advantages often outweigh individual skill. Consider the homeownership gap: a family that bought a $500,000 home in 1990 and held it for 30 years would see that asset appreciate to $2 million+ in many U.S. markets—without any active management. Similarly, tax-deferred accounts like 401(k)s or ISAs allow middle-class earners to compound wealth silently over decades. The top 2 percent net worth isn’t reserved for quant traders or hedge fund managers; it’s accessible to those who leverage structural opportunities. That said, scaling beyond the top 2 percent net worth does require advanced financial literacy. The difference between a $2 million and a $20 million portfolio often lies in asset allocation, risk management, and exit strategies. A dentist who invests in rental properties might reach the threshold, but a dentist who also structures a private equity fund could accelerate into the next wealth bracket. The myth of the "self-made genius" ignores the infrastructure—legal, tax, and advisory—that amplifies even modest financial decisions.Myth 3: Once You’re In, You’re Safe
The top 2 percent net worth offers buffer against volatility, but it’s not a firewall against risk. The 2008 financial crisis saw net worth declines of 20-30% for many in this cohort, particularly those overconcentrated in financial assets. More recently, the tech correction of 2022 wiped out billions for early-stage investors in private equity. Even blue-chip assets aren’t immune: the Japanese real estate bubble collapse in the 1990s left some ultra-high-net-worth families with illiquid, depreciating holdings for decades. What distinguishes the permanent top 2 percent net worth from the temporary is diversification and liquidity. A family that holds only private company stock or undiversified real estate remains vulnerable. Those who hedge with gold, sovereign bonds, and global equities can weather downturns. The myth of permanence stems from survivorship bias—we hear about the $100 million fortunes but not the $50 million that evaporated. The top 2 percent net worth is a threshold, not a destination.
What Holds Up to Scrutiny
At its core, the top 2 percent net worth is defined by three verifiable pillars: asset concentration, generational transfer, and tax optimization. The first pillar—asset concentration—means holding illiquid, high-growth assets like private equity, farmland, or intellectual property. These assets don’t just appreciate; they reinvest profits internally, accelerating wealth accumulation. The second pillar—generational transfer—accounts for 40% of ultra-high-net-worth wealth in countries like Germany and Italy, where family trusts and dynastic structures preserve capital across centuries. The third pillar—tax optimization—involves legal structures like offshore entities, charitable trusts, and strategic residency planning to minimize liabilities. What doesn’t hold up is the one-size-fits-all narrative. The top 2 percent net worth in Singapore looks different from that in Texas. In Singapore, it’s tied to sovereign wealth funds and real estate; in Texas, it’s energy sector stakes and farmland. The global median for this cohort is $1.9 million, but the U.S. median is higher due to stock market exposure, while Europe’s is lower due to higher tax burdens. The scrutiny reveals that location, timing, and asset class matter more than raw numbers."Wealth isn’t about how much you make—it’s about how much you keep and how you deploy it. The top 2 percent net worth isn’t a finish line; it’s a platform for the next phase." — James Henry, economist and former chief economist at McKinsey
| Common Belief | What the Evidence Says |
|---|---|
| The top 2 percent net worth is static. | Thresholds adjust with inflation and market cycles. A 2019 threshold may require 20% more by 2025. |
| Most in this group are CEOs or Wall Street traders. | Only 15% of U.S. ultra-high-net-worth individuals are in finance or tech; the rest are doctors, lawyers, and entrepreneurs. |
| Inheritance is the primary driver. | Inherited wealth accounts for ~30% of U.S. top 2 percent net worth; the rest is self-generated. |
| You need to be aggressive with investments. | Passive strategies (index funds, real estate) dominate for 60% of this cohort; active trading is rare. |
| Once you’re in, you’re immune to risk. | 2008 and 2022 saw net worth declines of 15-25% for many, even with diversified portfolios. |
Why the Confusion Persists
The top 2 percent net worth remains obfuscated by two forces: data opacity and cultural stigma. Governments rarely publish granular wealth distribution data, leaving analysts to rely on proxy metrics (tax filings, credit reports). Even when numbers exist, they’re aggregated, hiding regional and demographic variations. The U.S. Federal Reserve’s SCF survey is the gold standard, but it underreports illiquid assets like art and private equity, skewing perceptions. Cultural stigma plays an equal role. In Asia, discussing wealth is taboo, so self-made billionaires downplay their fortunes. In Europe, old money families disguise holdings through trusts and foundations. The result? A feedback loop of misinformation where anecdotal stories (e.g., "My uncle made it all in crypto") overshadow structural realities. The confusion isn’t just about numbers—it’s about who gets to tell the story.
Conclusion
The top 2 percent net worth isn’t a mystical threshold but a measurable outcome of strategic decisions. It rewards those who understand asset classes, tax arbitrage, and generational planning—not just those with high incomes. The biggest misconception is that it’s exclusive to a select few. In reality, systemic advantages (homeownership, tax-deferred accounts, inheritance) can democratize access to an extent. What separates the temporary top 2 percent from the permanent is discipline: the ability to preserve capital during downturns and reinvest during opportunities. For those outside this bracket, the takeaway isn’t envy—it’s strategy. The same principles that preserve wealth at the top can accelerate growth for middle-class earners: diversification, tax efficiency, and long-term horizon. The top 2 percent net worth isn’t a privilege—it’s a result. And like any financial outcome, it can be influenced, but not guaranteed.Comprehensive FAQs
Q: How is the top 2 percent net worth calculated?
The threshold varies by country. In the U.S., it’s ~$2.2 million for a household, but in Switzerland, it’s ~CHF 2.5 million. Calculations include liquid assets (cash, stocks), illiquid assets (real estate, private equity), and liabilities (debts, mortgages). Governments use household surveys (e.g., Federal Reserve’s SCF) or tax filings to estimate these figures.
Q: Can you lose your top 2 percent net worth status?
Yes. Market downturns, poor asset allocation, or unexpected liabilities (divorce, lawsuits) can push individuals below the threshold. The 2008 crisis saw ~15% of U.S. ultra-high-net-worth individuals dip below the top 5 percent temporarily. Diversification and liquidity are key to retaining status during volatility.
Q: Is the top 2 percent net worth the same globally?
No. Cost of living, tax laws, and asset valuations create wide disparities. For example:
- U.S.: ~$2.2M (median)
- UK: ~£3M (~$3.8M)
- Germany: ~€2.5M (~$2.7M)
- Singapore: ~S$3M (~$2.2M)
Q: Do most in the top 2 percent net worth work in finance?
No. Only ~15% of U.S. ultra-high-net-worth individuals are in finance, tech, or real estate. The rest are:
- Professionals (doctors, lawyers, consultants)
- Entrepreneurs (small business owners, franchisees)
- Legacy holders (inherited wealth managers)
Q: How do people in the top 2 percent net worth protect their wealth?
They use a mix of:
- Legal structures: Trusts, family limited partnerships (FLPs), offshore entities (where permitted).
- Asset diversification: 10-20% in private equity, 30% in real estate, 20% in cash equivalents, 30% in public markets.
- Tax optimization: Charitable trusts, residency planning, and strategic gifting to reduce liabilities.
- Insurance: Umbrella policies, cyber liability, and key-person insurance for business owners.
Q: Can you achieve the top 2 percent net worth on a middle-class salary?
Yes, but it requires decades of disciplined saving and strategic investing. For example:
- A $100,000 salary with 20% savings rate and 7% annual returns could reach $2M in ~30 years (assuming no major setbacks).
- Real estate (rental properties, REITs) and tax-advantaged accounts (401(k), IRA) accelerate the process.
- Avoiding lifestyle inflation and leveraging compounding are critical.
Q: What’s the biggest mistake people make when trying to reach the top 2 percent net worth?
Overconcentration in a single asset class (e.g., company stock, crypto, or a single property). The 2022 crypto crash and 2008 housing bubble both exposed this risk. Other mistakes include:
- Ignoring taxes: High earners often underestimate capital gains or estate taxes.
- Lack of liquidity: Holding only illiquid assets (e.g., private equity) can create cash-flow problems.
- Emotional investing: Chasing trends (meme stocks, NFTs) instead of long-term fundamentals.
